

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Nylon-MXD6 Market to Grow at 5.85% CAGR, Reaching USD 749M by 2032
By pmarketresearch, 2026-07-30

Nylon‑MXD6 Market — 2026 Strategic Outlook and Decision‑Grade Intelligence
As companies set their 2026 strategic plans, Nylon‑MXD6 has moved from a niche performance polymer to a commercially strategic material across packaging, automotive, and select engineering markets. PW Consulting’s latest Nylon‑MXD6 Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes quantitative forecasting, supply‑chain mapping, and actionable strategy frameworks to convert material science advantage into commercial value. The market reached approximately USD 506 million in 2025 and, under our central scenario, is projected to expand at a 5.85% CAGR through the 2026–2032 forecast window — reaching the high‑hundreds million range by 2032. This report is designed as an operational roadmap for procurement leads, product managers, and corporate strategy teams who must make investment decisions in 2026 with a 3–7 year horizon.
Nylon-MXD6 Market
Why Nylon‑MXD6 matters for 2026 decisions
-
Performance economics: MXD6’s unique semi‑aromatic backbone delivers barrier performance and thermal stability that bridge commodity nylons and engineering polymers — enabling downsizing, weight savings, and sustainability claims without compromising shelf life or mechanical integrity.
Nylon-MXD6 Market -
Commercial inflection: The market has matured from early adopters to supply‑constrained mainstream buyers. Historical growth from the early 2020s through 2025 demonstrates both demand elasticity and capacity responses, creating a window where timely strategic moves (sourcing, licensing, or co‑development) can materially change cost and market positioning.
Nylon-MXD6 Market -
Regulatory and sustainability vectors: Certification pathways (notably ISO 22095 mass‑balance routes) now permit bio‑content nylon variants without performance tradeoffs, opening packaging end‑markets that prize renewable content while maintaining barrier integrity.
What this study delivers (practical, decision‑ready contents)
-
Robust market model: A bottom‑up revenue model covering 2020–2025 historicals and 2026–2032 forecasts. The model quantifies demand drivers and sensitivity to feedstock and end‑market cycles. High‑granularity time series are provided for subscribers (note: detailed segment revenue tables are available within the full report).
-
Scenario packs: Three executable scenarios (Base, High‑Adoption, Supply‑Shock) with trigger matrices that translate macro inputs—feedstock price volatility, regulatory shifts, and capacity additions—into P&L and EBITDA impacts for manufacturers and converters.
-
Supply‑chain maps and risk heatmaps: Upstream monomer flows, critical dependencies on MXDA synthesis pathways, and exposure diagnostics for feedstock swings—essential for procurement and hedging strategies.
-
Commercial playbooks: Go‑to‑market options for polymer producers, compounders, and converters including licensing models, tolling partnerships, and joint R&D structures to enable faster market entry or margin protection.
-
Deal and M&A compass: A prioritized list of acquisition archetypes and red flags for corporate development teams, alongside valuation sensitivity to capacity additions and certification premiums.
-
Competitor intelligence dossiers: Strategic positioning, technology licensing footprints, and product portfolios for the industry’s active players — enabling benchmarking and counter‑strategy development.
Key market dynamics every executive must factor into 2026 plans
-
Feedstock volatility is not academic: MXD6 production relies on MXDA monomer (synthesized from m‑xylene and ammonia). Historical analysis shows crude‑linked feedstock swings that can exceed 30% in short cycles; procurement strategies that ignore hedging, vertical integration, or alternative feedstocks risk margin erosion during pricing spikes.
-
Certification changes are creating premium pockets: Mass‑balance certification (ISO 22095) has enabled the commercial launch of bio‑sourced MXD6 blends. Newly announced grades with certified renewable content convert technical sustainability claims into procurement‑eligible specs for large consumer packaged goods companies.
-
Domestic capacity shifts alter bargaining power: New pilot and ramp projects targeting local supply (particularly in China) are changing traditional trade flows and shortening lead times—an important consideration for firms looking to lock inbound supply or negotiate long‑term offtake.
-
Market concentration is material: The industry shows a moderate concentration at the top; incumbent technology owners and their licensed producers retain preferred access to specialized film‑grade and barrier‑enhanced variants, shaping pricing and co‑development dynamics.
Competitive landscape — strategic implications
The competitive map blends entrenched licensors and nimble compounders. A few firms hold core technology and brand cachet for MXD6 production, with additional licensed and regional producers closing the supply gap or competing on cost‑engineered compounds.
-
Technology owners and licensors: Established licensors with proprietary MXDA polymerization technology possess IP that creates high barriers for full‑performance grade replication. Their strategic options include licensing expansion, co‑branding for specialty grades (e.g., barrier‑enhanced films), and premium pricing for certified bio blends.
-
Regional compounders and long‑fiber suppliers: Compounders offering LFT‑reinforced MXD6 and filled compounds enable new engineering use cases (structural automotive, durable consumer goods) where material substitution can create value through part count reduction or weight savings.
-
New domestic entrants: Recent pilot capacity approvals and ramp announcements evidence a pivot toward import substitution in some markets. These entrants will focus on volume, cost competitiveness, and local certification to win contracts with domestic converters or converters seeking de‑risked supply chains.
For corporate strategists, these dynamics imply three tactical vectors for 2026: (1) secure differentiated feedstock pathways and certification to capture sustainability premiums, (2) pursue selective partnerships with licensed technology owners or licensed producers to access high‑value grades, and (3) hedge near‑term demand via flexible sourcing agreements or tolling arrangements while evaluating capex for longer‑term vertical integration.
Recent developments that change the 2026 calculus
-
Commercial bio‑graded launch: A leading technology owner recently launched an MXD6 grade with approximately 25% bio‑sourced MXDA via an ISO 22095 mass‑balance-certified pathway. This product shifts the certification barrier and enables adoption by CPGs with strict renewable content thresholds.
-
Pilot‑to‑scale pushes: Several suppliers have announced pilot capacity projects with fast‑track plans to scale. Early pilot approvals demonstrate regulatory support in targeted jurisdictions and indicate a near‑term increase in available supply that could pressure regional premiums.
How to use the report in 2026 planning cycles
-
Procurement: Use the report’s price sensitivity and feedstock exposure models to design multi‑tier contracts (indexation + floor, strategic corridors, or options) that limit upside cost exposure while maintaining supply security for 2026 launches.
-
Product development: Leverage the material substitution matrix and barrier performance banding to prioritize MXD6 trials for packaging lines where shelf life or downgauging unlocks margin expansion.
-
Capex and M&A: Apply the scenario outputs to capex timing decisions; evaluate bolt‑on buys in compounders or licensed producers when projected regional supply tightness exceeds acceptable risk thresholds.
-
Sustainability and regulatory: Integrate certification pathways into your supplier evaluation checklist; ISO 22095‑compliant mass‑balance products can reduce time‑to‑market for renewable claims.
What PW Consulting’s Nylon‑MXD6 Market report does not publish here
To preserve the strategic sensitivity of core segment economics and to follow our “trailer” principle, this introduction outlines the modeling approach and the strategic implications without publishing granular segment‑level revenue breakdowns or unit pricing matrices by region and application. The full study includes downloadable excel models, granular regional and application segment tables, vendor scorecards, and bespoke scenario outputs — all accessible via the report landing page.
Call to action for 2026 leaders
If you are evaluating raw material sourcing, product reformulation, capital allocation or M&A in 2026, this report converts market noise into decision rules. Our clients use these outputs to: (a) quantify the value of early licensing agreements, (b) decide between capacity investment and long‑term offtake, and (c) price sustainability premiums into bids. For teams that need workshop support, PW Consulting offers scenario rehearsals and bespoke modeling to integrate the Nylon‑MXD6 forecast directly into your 2026 budgeting and strategic planning cadence.
PW Consulting’s Nylon‑MXD6 Market study is the operational intelligence pack for 2026: it provides the market context, risk controls, and competitive insight you need — without exposing the proprietary segment detail here. Access the full report for the datasets, models, and playbooks that will make your 2026 decisions defensible and actionable.
For detailed analysis of this topic, please visit the official page: Nylon-MXD6 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wedding Ring Market to Reach USD 158.38B by 2032 at 6.5% CAGR
By pmarketresearch, 2026-07-30
Wedding Ring Market — 2026 Strategic Preview
Executive snapshot
PW Consulting's latest Wedding Ring Market study (base year 2025) equips executives with the commercial intelligence required to make high-conviction decisions in 2026. The market has expanded steadily through the 2020–2025 period, rising from a mid‑teens USD billion base in 2020 to a USD 103.0 Billion market in 2025. Our forecast (2026–2032) projects continuation of this trajectory under a central case CAGR of 6.5%, reaching roughly USD 158.4 Billion by 2032. The market displays meaningful concentration at the top; the three largest groups account for a clear majority of industry revenue and the top five approach three‑quarters of the market — a structural fact that shapes competitive tactics and M&A returns.
Wedding Ring Market
Why this matters for 2026 corporate planning
-
Growth remains attractive but binary: steady headline expansion masks bifurcation between premiumization and volume-led segments. Brands that can combine premium storytelling (heritage, cut performance, provenance) with scalable distribution will capture outsized value.
Wedding Ring Market -
Input-cost volatility has moved from background risk to strategic determinant. Raw material dynamics — including record price movements in precious metals and the ongoing cost pressure on diamonds — will materially affect gross margins, inventory policies, and pricing cadence in 2026.
Wedding Ring Market -
Ethical sourcing and transparent provenance have migrated from CSR checkbox to purchase driver, particularly among high-value cohorts. Brands without credible traceability will find margin compression as consumers increasingly pay premiums for responsibly sourced goods.
-
Channel economics are evolving: digital first‑touch conversion improvements reduce acquisition costs, but physical retail remains essential for high-ticket closure and post‑sale services. The optimal 2026 model is omnichannel, calibrated by cohort-specific conversion economics.
-
Market concentration creates fertile ground for M&A and strategic alliances. Acquirers who can integrate manufacturing scale, distribution reach and brand exclusivity stand to accelerate roll‑up synergies in 2026 and beyond.
Key dynamics shaping strategy in 2026
-
Material price pressure and hedging: 2025 volatility has pushed procurement to the top of the agenda. Leading firms are combining longer-term supplier contracts, financial hedges and a calibrated mix of recycled/reclaimed metals to stabilize input costs and preserve margin elasticity.
-
Provenance and ESG integration: Ethical sourcing initiatives are no longer optional. Certification, blockchain-enabled provenance, and direct-sourcing partnerships with responsible mines and refiners are now strategic investments to protect brand equity and command price premiums.
-
Product modularity and personalization: Consumer preferences are skewing towards customizable and stackable designs. Operationally, this trend favors modular manufacturing and configurable SKUs that allow personalization at scale without proportional increases in lead time or cost.
-
Digitally-enabled product experience: Investment in high-fidelity visualization tools (light‑return simulators, AR try-ons, cut‑performance dashboards) materially increases conversion, especially for digitally native cohorts who prioritize objective quality signals.
-
Channel orchestration: Optimizing the interplay between online discovery, virtual consultations and in-store fulfillment will determine customer acquisition economics and lifetime value in 2026. Firms should measure and iterate the omni funnel with closed-loop attribution.
What the PW Consulting report delivers (practical, on-the-ground content)
This report is designed as an operational toolkit for 2026 planning cycles. Highlights include:
-
Scenario-led financial models: three demand scenarios (base, upside, downside) across 2026–2032 with sensitivity to material prices, channel mix and average selling price (ASP) movement.
-
Price elasticity and packaging frameworks: empirically validated elasticities by product tier and recommended promotional strategies that protect brand equity while improving conversion.
-
Supply‑chain risk matrix and sourcing playbook: supplier segmentation, traceability checklists, inventory policy recommendations and hedging protocols tailored to wedding rings.
-
Omnichannel commercial playbooks: cost-to-serve models, store-vs-digital margin trade-offs, localized assortment tactics and pilot blueprints for click‑to‑collect and virtual‑reservation services.
-
Product and assortment roadmaps: modular SKU architecture templates, launch calendars for stackable and customizable collections, and unit-economics tests for DTC versus wholesale placements.
-
M&A and partnership scorecards: acquisition screening filters, integration checklists and expected synergies for manufacturing, distribution and IP-focused targets.
-
Customer segmentation and LTV models: cohort definitions, acquisition benchmarks, retention levers and lifetime value uplift scenarios for personalization and aftercare services.
-
KPIs and implementation dashboards: executive dashboards and organizational change templates to operationalize strategy into QBRs and 12‑18 month roadmaps.
Competitive landscape — strategic takeaways from incumbent behavior
The report examines marquee incumbents and their strategic postures. Below is a concise reading of how leading firms in the wedding ring space are positioning — and what that implies for competitors and potential investors.
-
Artcarved (New York) — Heritage craftsmanship and comfort-centric design are Artcarved’s differentiators. Strategic implication: heritage brands can monetize provenance and differentiated fit, but must modernize supply-chain transparency and digital merchandising to connect with younger buyers. Recommendation: pair limited-edition heritage runs with robust DTC storytelling and aftercare subscriptions.
-
Brilliant Earth (San Francisco) — Market leader on ethical sourcing and traceability. Strategic implication: sustainability creates a defensible premium; rivals must decide whether to match via certification or compete on price/scale. Recommendation: companies seeking share in premium segments should fast-track traceability pilots and certification partnerships, or risk margin erosion.
-
Tacori (California) — Known for customizable, American-made designs. Strategic implication: customization drives differentiation but elevates operational complexity. Recommendation: adopt a modular manufacturing approach to reduce lead-times while preserving bespoke value, and explore in-store configurators that convert higher-AOV customers.
-
Whiteflash (New York) — Focus on cut performance and measurable light return. Strategic implication: technical differentiation appeals to quality‑sensitive buyers; translating technical advantage into accessible messaging is the gap. Recommendation: invest in visualization tools and third‑party validations to convert technical superiority into purchase intent.
-
Shane Co. (Minneapolis) — Family-owned omnichannel operator with broad inventory. Strategic implication: physical scale drives convenience and trust for high-ticket purchases, but inventory financing and working-capital are critical levers. Recommendation: optimize SKU rationalization and inventory turns; explore subscription-style maintenance and upgrade programs to increase LTV.
-
JewelPin (USA) — Global manufacturer/wholesaler of ready-to-ship rings. Strategic implication: supply-side scale positions this player as an attractive partner for private-label programs and fast-fulfillment needs. Recommendation: brands should evaluate strategic supplier relationships to capture cost advantages, while protecting brand exclusivity through design IP and selective distribution.
Recommended 2026 playbook — five tactical moves
-
Institute a two‑track pricing strategy: protect premium SKUs with provenance narratives while deploying value-led assortments optimized for rapid inventory turns.
-
Implement a raw-materials risk dashboard: combine contractual coverage, recycled metals and selective hedging to smooth cost pass-through to consumers.
-
Scale modular customization: reduce bespoke costs with pre‑configured modules, improving margins and reducing lead times.
-
Operationalize provenance: move from marketing claims to auditable supply chains (certificates, trace logs, digital provenance) to protect pricing power.
-
Pursue targeted consolidation: use the current concentration dynamics to acquire complementary manufacturing or distribution assets that accelerate profitable growth.
What we intentionally withhold in this preview
To preserve actionable value for decision-makers, this preview omits the granular regional, material and channel breakdowns (detailed tables with regional splits, per‑material revenue bands and channel economics are available in the full report). The report also includes downloadable financial models, country-level forecasts and executable pilot templates that are not reproduced here.
Next steps
For market-entry analysis, capex planning, or M&A screening in 2026, PW Consulting’s full Wedding Ring Market report provides the granular intelligence and tools required to move from insight to execution. Access the complete dataset, scenario models and playbooks on PW Consulting’s report page or contact our industry leads for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Wedding Ring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EMI Absorber Sheets & Tiles Market to Reach USD 1,102M by 2032 (5.1% CAGR)
By pmarketresearch, 2026-07-30
EMI Absorber Sheets & Tiles Market — Strategic Perspectives for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a succinct, decision-focused introduction to our new market study on EMI absorber sheets and tiles. This market is transitioning from niche materials play to a strategic systems component, and the choices organizations make in 2026 will determine competitive position through the next investment cycle. Our view is grounded in a consolidated market model (base year 2025, historical window 2020–2025, forecast horizon 2026–2032) that projects a compound annual growth rate (CAGR) of 5.1% across 2026–2032. The industry recovered from mid-decade volatility, with global reported market value around USD 778 million in 2025 and a projected trajectory toward roughly USD 1.10 billion by 2032.
EMI Absorber Sheets & Tiles Market
Why this study matters to C-suite and BU leaders in 2026
- Validate product and market bets: the study translates macro demand drivers (telecom densification, automotive electrification, miniaturization in consumer electronics, medical device reliability) into implications for absorber material choices and form factors.
- Prioritize capital allocation: our scenario-based forecasts identify when to scale capacity, automate converting/die-cutting, or defer CAPEX to avoid overcapacity.
- Derisk sourcing and pricing: we quantify the sensitivity of margins to raw-material swings (ferrites, conductive polymers) and labor inputs in adhesive converting.
- Shape M&A and partnership agendas: concentration metrics and capability maps reveal what capabilities are most accretive (broadband formulations, thin elastomer converters, ferrite tile manufacturing).
- Fast-track regulatory readiness: EMC compliance up to 10 GHz, RoHS, and UL94V-0 flame-retardancy requirements are central to product acceptance in core verticals.
What you will practically get from the full report
- Executive dashboard: concise market sizing, validated growth curves, and scenario outputs to support board-level decisions.
- Demand-by-dimension model: a dynamic engine combining end-market adoption curves, device BOM penetration rates, and replace/retrofit cycles (regional and application decompositions available in the full report).
- Competitive playbooks: capability matrices, go-to-market positioning, product portfolios and channel strategies for leading and emerging suppliers.
- Supply-chain risk map: tiered supplier intelligence for ferrites, conductive polymers, adhesives and converting partners, with contingent sourcing blueprints.
- Pricing and margin sensitivity tool: run “what-if” scenarios on raw-material spikes, freight dislocations, and labor rate shifts to quantify P&L exposure.
- Regulatory and testing checklist: mandatory EMC/EMI test bands, certification pathways, and time-to-market implications for different verticals.
- Actionable recommendations and a 12–36 month implementation playbook tailored to three archetypes: OEMs, component manufacturers, and specialty converters.
Macro trends and constraints shaping 2026 decisions
Three structural themes will dominate strategy in 2026:
EMI Absorber Sheets & Tiles Market
- Standards-driven complexity: EMC requirements increasingly require absorption solutions to perform across broader frequency ranges—designs must be validated to tens of GHz in product test plans. This drives demand for broadband absorber formulations and hybrid solutions that combine ferrites and conductive polymers.
- End-market consolidation and technological substitution: automotive electrification and advanced driver-assistance systems (ADAS) introduce more stringent EMI requirements, increasing per-vehicle absorber content. Simultaneously, telecom densification (including 5G and emerging mmWave deployments) reallocates absorber demand between form factors—sheet, tile, and dispensable materials.
- Cost-to-serve pressure from material and processing inputs: ferrites and conductive polymers represent the majority of raw-material cost in sheet/tile manufacturing, while converting operations (adhesive lamination, die-cutting) introduce labor and precision-costs that materially affect unit economics. Strategic choices—automation of converting, supplier consolidation, or vertical integration—will determine margin trajectories.
Overlaying these themes are regulatory constraints: EMC compliance up to 10 GHz is increasingly expected, and materials must meet RoHS and UL94V-0 flame-retardancy standards for many applications. These requirements affect sourcing, lead times, and qualification cycles.
EMI Absorber Sheets & Tiles Market
Competitive landscape — who matters and how
The market exhibits a moderate concentration profile: the top three global players account for roughly two-thirds of reported industry revenue, and the top five approach three-quarters of the market. This structure creates both barrier and opportunity: established incumbents control scale advantages and deep customer relationships, while focused specialists and regional producers can win on technical differentiation or cost agility.
- 3M Company (St. Paul, Minnesota) — A technology stalwart with a broad portfolio (including multi-frequency absorbers) and deep relationships across electronics and automotive OEMs. Their advantage is integrated material science, strong formulation IP, and global go-to-market coverage. Strategic implication: competing with 3M requires either a technical niche (ultra-thin form factors, tailored adhesive stacks) or superior cost-to-serve in targeted verticals.
- Laird Performance Materials (United States) — Focused on thin elastomer absorbers, ferrite sheets and dispensable absorbers for near-field and cavity-resonance suppression. Laird’s playbook emphasizes application-specific engineering and close OEM collaboration. Strategic implication: partnerships or licensing of niche formulations can accelerate time-to-market for OEMs seeking quick qualification cycles.
- Fair-Rite Products Corp. (Wallkill, NY) — A ferrite-component specialist delivering absorber and shielding components integrated into sheets and tiles. Their capabilities matter where ferrite performance dominates, particularly in constrained geometries and cavity solutions. Strategic implication: securing ferrite supply or co-development agreements is a defensive move for manufacturers reliant on ferrite performance.
- KITAGAWA INDUSTRIES (Japan) — A regional supplier with a deep product catalogue tailored for EMC use cases. Kitagawa’s strengths are engineering support and localized supply chains in Asia. Strategic implication: for players targeting Asia Pacific, regional alliances or distribution agreements are pragmatic short-cuts.
- Henkel AG & Co. KGaA (Düsseldorf) — Known for adhesives and shielding films, Henkel has leaned into automotive electronics with recent product introductions designed to combine shielding and adhesion in cost-effective formats. Strategic implication: adhesives and films are adjacent levers—OEMs should evaluate integrated film+adhesive offers to simplify assembly and certification burdens.
Recent vendor activity underscores the pace of product development and catalogue refresh: Henkel launched a targeted shielding film at Productronica 2025; KITAGAWA updated its absorber product range in April 2025; Fair-Rite refreshed its ferrite components catalogue in late 2025. These moves signal that incumbents are optimizing portfolios for automotive and smart-home applications while trying to capture retrofit and retrofit-replacement windows.
Strategic playbook for 2026 (practical recommendations)
- Segment with intent: prioritize a limited set of end-markets (e.g., high-value automotive modules, telecom infrastructure, or medical devices) where technical differentiation or regulatory moats allow premium pricing. Use the report’s demand engine to stress-test your selection under three scenarios.
- Lock critical raw-material access: establish multi-sourced agreements for ferrites and conductive polymers, include price collars or indexation clauses, and explore toll-processing partnerships to reduce inventory buffers.
- Optimize converting economics: audit converting steps (adhesive lamination, die-cutting) and quantify ROI on automation. For many players, a hybrid approach—capex-light regional converting hubs paired with centralized bulk compounding—offers best trade-off between lead time and cost.
- Invest selectively in integration: vertical moves into ferrite compounding or adhesive laminating can be accretive if you capture >X% of internal demand (see detailed thresholds in the report). Otherwise, pursue strategic alliances and tight co-development agreements.
- Design for certification early: embed EMC test requirements (up to 10 GHz), RoHS, and UL94 planning into product roadmaps to avoid late-stage redesign costs and delayed time-to-market.
- Prepare M&A playbooks: target niche specialists in broadband formulations or high-precision die-cutting; run rapid technical diligence against supplier scorecards we provide.
- Differentiate on service: offer design-assist, prototype-to-qualification services, and inventory-managed programs to OEMs—these can convert technical value into sustainable margin expansion.
Supply-chain levers and cost management
Two cost buckets deserve programmatic attention in 2026: raw materials and converting labor. Ferrites and conductive polymers account for the majority of material cost; adhesive converting and die-cutting are the principal labor and precision-cost drivers. Practical levers include formula reformulation to reduce expensive fillers, moving low-variance converting to automated cells, implementing vendor-managed inventory for adhesives, and negotiating freight and lead-time guarantees with upstream suppliers.
How PW Consulting’s analysis de-risks your pathway
- Transparent scenario modelling: three adoption trajectories and sensitivity matrices tied to raw material moves and regulatory timelines.
- Supplier scorecards and capability heatmaps: technical capacity, qualification timelines, geographic footprint, and price bands—designed for rapid procurement decisions.
- Case studies and playbooks: real-world rollouts in automotive and telecom contexts that translate to certification time, costs, and expected absorption rates per device class.
- Negotiation-ready templates: commercial terms, sample SOWs for co-development, and recommended risk-sharing clauses for supply agreements.
Closing — what this preview leaves deliberately unsaid
This article intentionally focuses on strategic implications, the competitive topology, and operational levers for 2026. To preserve the “trailer” purpose—illustrating depth while reserving the core forensic inputs—we have omitted the granular regional and application-level revenue breakdowns, detailed segment-by-segment CAGR overlays, and specific pricing curves. These elements are central to tactical execution (e.g., targeted capacity investments, SKU rationalization, and regional sales plays) and are contained in the full PW Consulting report and the downloadable analytical models.
If you are preparing capital plans, supplier strategies, or product roadmaps for 2026 and beyond, the full report will provide the numeric precision (regional and application allocations, unit economics, and supplier-level financial proxies) needed to convert the strategic directions above into executable programs.
Contact PW Consulting to access the full EMI Absorber Sheets & Tiles Market study, the interactive model, and a tailored briefing that maps our insights to your organization’s decision calendar for 2026.
For detailed analysis of this topic, please visit the official page: EMI Absorber Sheets & Tiles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Lyons Magnus Market: A Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting presents a focused industry preview built to accelerate executive decision cycles in 2026. The category we profile has demonstrated steady expansion through the post-pandemic window, growing from a resilient base in 2020 to an estimated USD 380.0 Million in 2025 (base year). Our modeling indicates continued momentum into the next decade, with the market projected to reach approximately USD 566.0 Million by 2032 at a compound annual growth rate (CAGR) of 5.75% over the 2026–2032 forecast period. These macro levers — a clear upward trajectory and mid-single-digit expansion — create a strategic runway for revenue growth, portfolio moves, and supply-chain redesigns in the near term.
Lyons Magnus Market
Why this preview matters for 2026 planning
-
Timing and allocation: With predictable, above-inflation growth, 2026 is a year for firms to convert volume tailwinds into margin expansion. Market participants should prioritize investments that scale quickly (e.g., modular production lines, plug-and-play co-manufacturing capacity, and SKU rationalization) over long-lead, high-capex projects that miss the growth window.
Lyons Magnus Market -
Risk-adjusted M&A: The market shows moderate concentration (CR3 ~32.5%; CR5 ~38.0%), pointing to an industry that is neither highly consolidated nor atomized. This structure favors targeted bolt-ons and platform plays — buyers can acquire meaningful increments of share without triggering immediate regulatory friction, but must still execute integration to realize synergies.
Lyons Magnus Market -
Demand-side sophistication: End-users across foodservice, beverage manufacturing, and healthcare are becoming more discerning on traceability, functionality, and format. Companies planning product launches or channel expansions in 2026 should embed proof points (supply-chain transparency, clinical or sensory validation, and operational flexibility) into both commercial and technical specifications.
What we include in the full Lyons Magnus Market report (practical, executable tools)
The full report is organized around decision-support, not just data. It delivers actionable outputs that enable leadership teams to translate market trends into initiatives within 90–180 days.
-
Integrated financial model: A base-case P&L and sensitivity model calibrated to the report’s macro forecast. Scenario toggles allow you to test volume, price/mix, and raw-material volatility to quantify EBIT levers under realistic 2026 operating plans.
-
Channel and go-to-market playbooks: Tactical roadmaps for foodservice, beverage OEMs, and institutional healthcare buyers — covering commercial construct, pricing frameworks, and pilot-to-scale timelines that preserve margin while accelerating adoption.
-
Supplier and production scorecards: Operational templates for assessing co-manufacturing partners, with metrics on traceability, yield, throughput, CAPEX intensity, and contract levers to align incentives.
-
M&A & partnership screening matrix: A prioritized short-list methodology and diligence checklist that helps you identify targets or white-space partners, estimate integration effort, and model combined entity economics.
-
Commercial segmentation toolkit: A playbook to convert demand-side segmentation into sales territories and SKU architecture — the toolkit details experiments and KPIs but intentionally omits raw segmentation tables in this preview to preserve the strategic advantage available in the full report.
-
Risk & mitigation matrix: Scenario-based stress tests for raw-material shocks, labor events, and regulatory shifts, together with recommended contingency actions and estimated P&L exposure.
Competitive landscape — where Lyons Magnus fits and why it matters
Lyons Magnus LLC occupies a distinct position in this market as a fully integrated fruit supplier and co-manufacturer, headquartered in Fresno, California. Their vertical integration—from ingredient sourcing to finished beverage and mix solutions—gives them structural advantages in traceability, formulation speed, and operational control that are increasingly valuable to large foodservice and healthcare customers.
Recent company activity reinforces this strategic posture. Lyons Magnus published a Food & Beverage Trend Forecast at the end of 2025 that identifies emergent menu and formulation categories that can materially influence customer purchase decisions. In early 2026 they expanded their consumer-facing and B2B offerings with new SKUs in their Maui Pumpable Fruit line, signaling a push to translate trend insights into rapid product introductions. These moves typify a capability set that combines market sensing with swift commercialization — a template other suppliers may seek to emulate or acquire.
For incumbents and newcomers, Lyons Magnus’ playbook suggests two imperatives for 2026: (1) shorten concept-to-shelf time through tighter supplier integration, and (2) invest in translational marketing that converts menu trends into measurable order pipelines within existing channel agreements.
Market dynamics and forward signals to watch in 2026
-
Format innovation: Demand is shifting toward formats that reduce kitchen labor and simplify back-of-house operations without sacrificing quality. Companies that can offer pumpable, concentrated, or ready-to-serve formats with robust shelf-life will win share.
-
Ingredient transparency and provenance: Buyers, especially in healthcare and premium foodservice, are elevating provenance claims from marketing to procurement criteria. Investments in traceable sourcing, certifications, and digital traceability will be table stakes.
-
Value chain modularity: Given the industry’s mid-single-digit CAGR, flexibility trumps scale in many segments. Modular, contract-friendly manufacturing arrangements — and the ability to scale capacity up or down — will be more valuable than rigid large-scale assets for several market participants.
-
Consolidation rhythm: The market’s concentration metrics indicate room for consolidation-driven M&A but with careful target selection. Expect strategic acquisitions that provide either geographic fill-in, capability augmentation (e.g., specialized blends or frozen-dessert solutions), or customer-account leverage.
Scenario snapshots — three plausible 2026 strategic postures
-
Defensive Optimizer: Prioritize margin protection through SKU rationalization, supplier renegotiations, and modest capex to automate low-margin tasks. Appropriate for firms with constrained balance sheets seeking to convert volume growth into cash.
-
Aggressive Expander: Use bolt-on M&A and channel partnerships to accelerate market access, backed by an integration playbook focused on rapid SKU rationalization and cross-selling. Best for firms with acquisition firepower and a clear integration roadmap.
-
Innovative Challenger: Invest in product development and traceability to command premium pricing in healthcare and high-end foodservice segments. Emphasize pilot commercialization with marquee clients and outcome-based contracting.
How to use this preview in your 2026 playbook
-
Immediate (30–60 days): Run a health-check against the report’s supplier scorecard and commercial playbook to identify one operational improvement and one pricing action that can be implemented within two months.
-
Near term (90–180 days): Adopt the financial model to stress-test your 2026 plan under three scenarios (baseline, upside, supply-shock) and identify the top two capital allocation moves that change projected ROIC.
-
Strategic (6–12 months): Use the M&A screening matrix to prioritize targets by strategic fit and integration complexity; lock in exclusivity dialogues where the combination yields immediate channel synergies.
Where this preview intentionally stops — and why
This article is designed as a strategic teaser: it demonstrates the analytical rigor and the practical outputs you can expect, while preserving the granular segmentation tables, regional and application breakdowns, and detailed financial models for the full Lyons Magnus Market report. Those granular datasets are central to precise pricing and market-entry tactics and are therefore only available in the paid report to preserve their competitive value for subscribers.
Concluding guidance
The market’s profile — steady historical expansion, predictable near-term growth, and a moderate degree of fragmentation — creates a landscape where disciplined execution wins. In 2026, leaders should be decisive: align capex to modular flexibility, move fast on product-market fit validated by customer pilots, and use targeted M&A to buy capability rather than just capacity. Lyons Magnus’ recent activity provides a contemporary case study of how vertical integration and fast trend-to-product cycles can create advantage; whether you replicate, partner, or compete with that model will be a defining choice for your 2026 strategy.
For the full dataset, the operational playbooks, and the downloadable financial model referenced here, visit the Lyons Magnus Market study page to access the complete Lyons Magnus Market report and supporting annexes.
For detailed analysis of this topic, please visit the official page: Lyons Magnus Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Plate-fin Heat Exchanger Market: USD 142.0M in 2025, 4.9% CAGR to 2032
By pmarketresearch, 2026-07-30
Plate-fin Heat Exchanger Market: Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a forward-looking synthesis of our Plate-fin Heat Exchanger (PFHE / brazed aluminum plate-fin heat exchangers — BAHX) market study designed to equip executives, procurement leaders, and investors with the strategic context they need for 2026. This briefing highlights the research’s strategic value, the operating dynamics that will shape near-term choices, and the competitive vectors that matter — while deliberately omitting granular segment tables and confidential split data to preserve the report’s proprietary value. For the full quantitative detail and downloadable modeling assets, please consult the PW Consulting report landing page.
Plate-fin Heat Exchanger Market
Why this study matters now
-
A maturing growth profile: Our analysis uses 2025 as the base year and projects the global plate-fin heat exchanger market to grow at a compound annual growth rate (CAGR) of 4.9% through the forecast window (2026–2032). That trajectory reflects steady expansion driven by industrial recovery, rising demand in cold-chain and cryogenics, energy transition projects, and near-term investments in domestic supply chain resilience.
Plate-fin Heat Exchanger Market -
Decision-making inflection in 2026: Companies planning CAPEX cycles, vendor consolidation, or regional manufacturing footprints in 2026 must synthesize regulatory updates, raw-material exposure, and supplier concentration into their procurement and engineering timelines. Our study converts those inputs into actionable scenarios and investment lenses.
Plate-fin Heat Exchanger Market -
Practical utility: This is not a high-level narrative. The report is rooted in a consolidated dataset and pragmatic tools — procurement scorecards, vendor due-diligence templates, integrity and safety checklists aligned to industry standards, and scenario-based cash-flow implications for design and material choices.
What the report delivers — operational content you can act on
-
Market sizing & trajectory: A reconciled market-size series calibrated to industry shipment and supplier-revenue data, with forecasts under three demand scenarios (baseline, accelerated energy-transition, downside macro shock).
-
Methodology transparency: Detailed forecasting assumptions, sensitivity matrices, and an explanation of the drivers behind our 4.9% CAGR. This lets teams re-run the model with proprietary inputs (e.g., plant-level load growth, project timelines).
-
Procurement playbook: Supplier selection criteria, total cost of ownership (TCO) templates, contract clauses for warranty and integrity, and a supplier-risk heat map keyed to material supplies and trade policy exposure.
-
Supply-chain mapping: Practical diagrams showing common raw-material routes, choke points for brazed-aluminum fabrication, and strategies that large OEMs and EPCs use to de-risk lead times and maintain quality.
-
Standards & compliance pack: An easy-reference digest of ALPEMA guidance, API alignment issues, and recommended internal checkpoints for integrity operating windows — framed as checklists for engineering and safety teams.
-
Case-driven guidance: Project-level case studies illustrating trade-offs (material selection, brazing processes, repairability, lifecycle costs) and a short-list of mitigation measures that preserve thermal performance while lowering lifecycle risk.
-
Investment and M&A intelligence: A tactical view of buyer-seller dynamics, valuation drivers, and likely consolidation vectors — for corporate development teams and private equity looking at mid-market BAHX specialists.
Key dynamics shaping supplier and buyer strategy
-
Standards evolution and operational implications: ALPEMA’s active role in clarifying its 4th edition standards — and its formal responses to the 2nd edition of API 668 — have immediate implications for engineering acceptance criteria, vendor qualification, and post-installation integrity programs. Buyers who internalize these updates early can shorten acceptance cycles and reduce retrofit exposure.
-
Raw-material and tariff pressure: Aluminum remains a medium-influence input for the BAHX value chain. Tariff tensions and policy-driven sourcing shifts are prompting manufacturers and large end-users to localize critical fabrication steps or hold strategic buffer inventories. Our supply-chain scenarios quantify the trade-offs between localized capacity build-out and incremental unit-costs.
-
Concentration and competitive tension: The market displays moderate concentration; the top tier of global suppliers accounts for a material share of industry revenue, but a broad long tail of specialist fabricators remains active. This balance favors sophisticated buyers who can leverage competitive bidding while maintaining technical prerequisites for performance and integrity.
-
Technology and application cross-currents: Advances in brazing processes, materials science, and quality-testing technologies are reducing failure modes and expanding feasible operating envelopes. Simultaneously, opportunities in LNG, industrial gas, and energy-efficiency applications are catalyzing demand for higher-specification units — with procurement consequences for cycle time and capital intensity.
Competitive landscape — who sets the technical baseline
The competitive map is anchored by established global players and a distributed base of regional specialists. Our report provides a vendor framework that reconciles technology capability, geographic reach, and service models. Below is a high-level synopsis of the primary global actors discussed in the study (profiles in the full report include capability matrices and vendor scorecards):
-
Linde Engineering (Munich, Germany): A leading manufacturer of brazed aluminum plate-fin heat exchangers with a long operational history. Linde’s installed base and ALPEMA participation underpin its engineering leadership and cross-border project execution capability.
-
Chart Energy & Chemicals, Inc. / Chart Industries (La Crosse, Wisconsin, USA): A major producer of vacuum-brazed aluminum PFHEs, with strong positioning in cryogenic and process applications. Chart’s product family is frequently specified for industrial gas and cryogenic systems.
-
Kobe Steel, Ltd. (Takasago, Hyogo, Japan): Known for high-performance PFHEs tailored to petrochemical, LNG, and industrial gas processing, Kobe Steel brings manufacturing scale and application-specific engineering.
-
Sumitomo Precision Products Co., Ltd. (Takarazuka, Osaka, Japan): A specialist with decades of experience in aluminum plate-fin heat exchangers, focused on cryogenic and precision industrial applications.
-
Alfa Laval (Lund, Sweden): Broadly recognized for compact PFHEs across HVAC, refrigeration, food processing, and industrial thermal management, Alfa Laval’s portfolio is oriented toward modularity and serviceability.
-
Eaton Corporation (Dublin, Ireland): Supplies custom vacuum-brazed aluminum PFHEs for liquid-to-liquid and liquid-to-air applications across automotive, aerospace, and industrial segments, with emphasis on lightweight and high-performance designs.
Strategic implication: The competitive set blends heavy-industrial incumbents (with deep project experience and large installed bases) and engineering-centric firms offering specialized product platforms. For buyers, this means evaluating suppliers on three axes: thermal performance, supply-chain risk (including material sourcing), and aftermarket integrity services.
Recent events and regulatory signals to watch
-
Industry convenings continue to accelerate dissemination of innovations and buyer-supplier matchmaking. Regional trade shows and technical expos in 2025–2026 offered early previews of next-generation PFHE architectures and testing protocols.
-
ALPEMA updates in late 2025 — including addenda and FAQs to the 4th Edition and a formal response to API 668’s second edition — elevate the importance of documented integrity operating windows and manufacturer-authorized maintenance regimes. Organizations that do not align inspection and acceptance processes to these standards will face higher operational friction and insurance scrutiny.
-
Supply-chain localization trends, driven by tariff conflicts and strategic sourcing policies, are creating selective opportunities for nearshore fabrication and aftermarket service providers. Our report quantifies the cost-per-unit of de-risking strategies versus the latency impact on project execution.
How to use the report in 2026 strategic planning
-
Procurement & supply-chain teams: Use the PW Consulting procurement templates to reconfigure RFQs around TCO and integrity risk, not just capex price. The report’s vendor scorecards help prioritize supplier trials and pre-qualification windows to align with upcoming projects.
-
Engineering & operations: Integrate the ALPEMA compliance checklists and integrity operating window guidance into commissioning and maintenance protocols. Our scenarios help quantify the trade-off between higher-specification units and lifecycle maintenance exposure.
-
Corporate development & investors: The M&A chapter isolates valuation levers (installed-base service revenue, proprietary fabrication capability, geographic access to key end-markets) and highlights likely consolidation targets and timing windows.
What we intentionally withhold here — and why
In line with our “trailer” principle, this briefing intentionally omits detailed segment-level splits by region, type, and application — and it does not disclose proprietary unit-level revenue tables embedded in the full model. Those datasets are part of the PW Consulting report package and are available through our web portal for licensed subscribers. This approach preserves the strategic advantage for decision-makers who need replicable numbers and downloadable financial models.
Closing guidance — three tactical moves for 2026
-
Short-term procurement: Recast RFQs to include integrity and lifecycle clauses aligned with ALPEMA and API expectations; quantify the premium for local fabrication versus extended lead times.
-
Operational resilience: Establish material hedging or strategic vendor partnerships focused on aluminum component continuity; expect modest cost increases tied to localization but measurable reductions in delivery risk.
-
Strategic scanning: Monitor M&A activity among mid-market fabricators and OEMs; these will be the most likely consolidation targets for companies seeking to build regional service networks and aftermarket revenues.
For the full dataset, downloadable forecasting model, vendor scorecards, and a step-by-step procurement playbook tuned for 2026 execution, visit the PW Consulting Plate-fin Heat Exchanger Market report page. The full report is structured to be both a strategic primer and an operational workbench for teams executing CAPEX, sourcing, or M&A activities this year.
For detailed analysis of this topic, please visit the official page: Plate-fin Heat Exchanger Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Video Intercom Market to Reach USD 36.67M by 2026 at 12.45% CAGR
By pmarketresearch, 2026-07-30
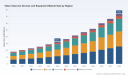
Video Intercom Devices and Equipment Market: Strategic Imperatives for 2026 Decision-Makers
As organizations finalize budgets and roadmaps for 2026, the video intercom market is at an inflection point. Our PW Consulting market study—anchored on a 2025 base year, tracking 2020–2025 historicals and forecasting through 2032—shows the sector expanding from a market size of USD 32.47 Million in 2025 to an estimated USD 73.82 Million by 2032, implying a compound annual growth rate of 12.45%. That trajectory reflects not only steady demand for basic ingress/egress solutions but a rapid compositing of cloud services, AI-enabled features, and systems integration that reframe intercom devices as nodes in broader security, building-management and tenant-experience platforms.
Video Intercom Devices and Equipment Market
Why this study matters for 2026 strategy
-
Timing: 2026 is the year many enterprises and public-sector procurement teams will operationalize multi-year digital infrastructure programs initiated during the pandemic recovery and smart-building pushes. Decisions made this year determine 3–5 year platform lock-in and long-tail operational costs.
Video Intercom Devices and Equipment Market -
Scale and pace: With a mid-teens CAGR, the market is large enough to attract both incumbents and new entrants but still fragmented enough to leave meaningful share and margin opportunities for bold players.
Video Intercom Devices and Equipment Market -
Regulatory pivot points: New and incoming regulations around procurement security, energy reporting and data-center obligations are already influencing vendor eligibility and platform design choices—making compliance a primary procurement filter in 2026.
-
Commercial impact: Video intercoms are transitioning from single-purpose devices into integrated security and tenant-engagement touchpoints; this reclassification changes procurement criteria from unit price to lifecycle total cost and data governance.
What the macro picture tells us (without revealing the confidential splits)
The headline growth and multi-year market sizing underscore a market that is expanding both in unit demand and in average revenue per device, as higher-value features—cloud subscriptions, AI analytics, and enterprise-grade integrations—become standard options. Market concentration is moderate: the top three vendors account for a meaningful share of industry revenues, and the top five expand that presence further. That configuration creates two strategic realities for 2026: first, scale and channel reach will continue to matter for large enterprise and government deals; second, differentiated feature sets and go-to-market models (e.g., fully mobile cloud vs. SIP-native and on-prem variants) can still deliver outsized growth for focused challengers.
Competitive landscape — what to watch in 2026
-
Incumbents with platform plays: Firms building integrated platform stacks—combining video, access control and cloud management—are shifting procurement conversations. These vendors emphasize operational simplicity and data consolidation, which appeals to enterprise customers seeking to reduce vendor sprawl.
-
Cloud-native disruptors: Mobile-first, no-wiring installation models are accelerating deployments in multifamily and retrofit commercial spaces. These providers lower installation friction and create recurring revenue via subscription models, but need to prove enterprise-grade reliability and integration breadth to win larger institutional customers.
-
Specialists focused on critical communications: Vendors delivering hardened, standards-based intercoms for industrial, broadcast and critical infrastructure retain a defensible niche—particularly where regulatory mandates and reliability requirements exclude consumer-grade alternatives.
-
Chinese OEM dynamics: Manufacturers with vertically integrated supply chains continue to compete on price and scale, but geopolitical and regulatory pressures in select procurement channels are materially reshaping their near-term addressable markets.
Across these archetypes you will find the companies profiled in our study. Each exhibits distinct strategic plays: cloud remote management and IP-series product lines from established hardware vendors; mobile-cloud propositions from emergent entrants; integrated AI and access-control convergence from enterprise-focused firms; and SIP-native offerings favored by systems integrators. These differences are not just marketing—they determine channel, pricing and integration strategies for 2026 contracts.
Regulatory and infrastructure headwinds (and opportunities)
-
Procurement security rules: Legislative measures that restrict certain vendors from government procurement in some jurisdictions force buyers and integrators to embed compliance criteria into RFPs. For vendors, achieving diversification and compliance attestations will be table stakes to access public-sector pipelines.
-
Energy and data-center constraints: New energy-reporting and power-usage obligations for infrastructure that supports cloud-based intercom services are increasing the effective cost of cloud operations in regulated regions. This creates demand for energy-efficient edge processing and hybrid cloud architectures that minimize data-center burdens.
-
Supply-side volatility: Component price swings—especially in displays, optics and polymer parts—are creating 15–20% cost fluctuation risks on bills of materials. Procurement teams must plan for buffer strategies such as dual-sourcing, longer-term contracts, and modular product designs to avoid margin erosion.
-
Local infrastructure policy: Regional electricity and transmission rules can materially change the TCO of cloud-first offerings where data-center obligations accrue to platform operators or their customers.
Recent vendor moves that foreshadow 2026 priorities
-
AI and usability innovations such as live translation, AI-powered voice directories and deterrence features are moving from pilot to productized releases—changing buyer expectations for what a modern intercom must do.
-
Modular integration modules and protocol adapters are being released to bridge touchscreen and third-party access-control ecosystems—reflecting demand for interoperability without wholesale rip-and-replace.
-
New mobile-directory and cloud-directory solutions for multi-tenant buildings show how software-as-a-service revenue and tenancy models are growing in importance alongside hardware sales.
Actionable recommendations for 2026 planning
-
Adopt a compliance-first vendor matrix: Build procurement scorecards that prioritize regulatory eligibility, energy reporting capability and supply-chain transparency over unit price alone. For public buyers, enforce vendor whitelisting and contract clauses tied to compliance milestones.
-
Model hybrid architectures: Require vendors to present hybrid cloud/edge deployment options and quantify delta-TCO over 3–7 year horizons under different energy and data-center cost scenarios. This will reveal true operating exposure and potential migration costs.
-
Stress-test supply chains: Mandate dual-sourcing for critical components or inventory hedging for greenfield deployments in 2026. Negotiate fixed-price or indexed contracts for volatile components when possible.
-
Insist on open integrations: For enterprise and multi-tenant deployments, require SIP and API compatibility, published SDKs and third-party integration references to reduce future lock-in and enable richer tenant services.
-
Prioritize lifecycle and service revenue: Shift procurement evaluation to include subscription economics, software roadmap alignment and service-level guarantees. Vendors with recurring-revenue models are more likely to invest in continuous feature upgrades relevant to tenant experience.
-
Look for partnership and M&A opportunities: Moderate concentration and differing vendor specializations mean strategic acquisitions or partnerships can deliver rapid capability expansion—particularly for players seeking AI or cloud competencies.
What the full PW Consulting report delivers
-
Comprehensive market-sizing (base year and forecast) and scenario modeling that captures energy, regulatory and supply-chain contingencies.
-
Vendor scorecards and positioning maps that evaluate product portfolios, go-to-market models, integration breadth and customer support maturity.
-
Action-oriented playbooks for procurement, systems integrators and product teams: migration roadmaps, contract clauses, integration checklists and three-year migration budgets.
-
TCO calculators and sensitivity analyses for cloud vs. edge strategies, including energy reporting impacts and component-cost shock tests.
-
Go-to-market strategies for challengers and incumbents: channel expansion tactics, partnership templates and M&A targets tailored to different regional and vertical priorities.
-
Primary research syntheses: interviews with integrators, end-users and vendor executives that ground our forecasts and vendor assessments.
Concluding strategic takeaways
2026 will be a decision-heavy year for both buyers and sellers in the video intercom market. The sector’s strong mid-teens CAGR and projected near-term doubling in market size make it an attractive arena for investment—but the path to sustained value depends on more than product specs. Compliance posture, energy-aware architectures, resilient supply chains and interoperable platforms will determine winners. Organizations that embed these criteria into procurement and product roadmaps in 2026 will avoid costly rework, capture recurring revenue opportunities and secure longer-term strategic advantage.
PW Consulting’s full research package contains the granular forecasts, vendor matrices and executable playbooks that procurement leaders, product strategists and M&A teams need to act with confidence. This executive preview intentionally omits confidential granular splits to preserve the analytical value of the full report. For the complete dataset, vendor scorecards and the customizable TCO models you will use to make 2026 decisions, refer to the full report.
For detailed analysis of this topic, please visit the official page: Video Intercom Devices and Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
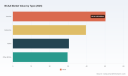
BCAA Market 2026 Outlook: Strategic Imperatives from PW Consulting’s New Market Research
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a concise, action-oriented preview of our new BCAA Market study — designed to inform C-suite decisions in 2026. The market for branched-chain amino acids (BCAAs) has shown steady expansion through the 2020–2025 period and is forecast to continue growing over 2026–2032. Anchored to a 2025 base year, our analysis synthesizes commercial, regulatory, and technological dynamics into a pragmatic roadmap for market entry, portfolio optimization, and M&A prioritization.
BCAA Market
Headline Macro View
Our modeling — based on historical activity from 2020 to 2025 — places the global BCAA market at approximately USD 150 Million (base year 2025). Under a central-case trajectory, the market expands to roughly USD 206 Million by 2032, reflecting a compound annual growth rate (CAGR) of about 4.6% over the 2026–2032 forecast period. This steady growth masks differentiated pockets of acceleration and deceleration driven by downstream demand shifts, manufacturing capacity moves, and evolving regulatory guards around novel ingredients and ingredient provenance.
BCAA Market
Why This Study Matters for 2026 Decisions
-
Timing capital allocation: The market’s moderate CAGR signals that value in 2026 will accrue from strategic positioning (product premiumization, supply-chain control, regulatory certainty) rather than from capturing a rapidly expanding volume market. Organizations must prioritize high-return uses of capital: targeted acquisitions, fermentation and purification upgrades, and regulatory dossiers for premium-grade products.
BCAA Market -
Portfolio reconfiguration: Nutrition brands face a bifurcation between commodity-driven supply (feed, bulk ingredients) and specialty pharmaceutical/nutraceutical pathways. The most resilient strategies will combine a core commodity foothold with differentiated, claimable product lines backed by clinical evidence or proprietary fermentation processes.
-
Regulatory and market access: Recent regulatory signals — including FDA NDI notifications and shifting data-privacy landscapes in the US — mean that market access and go-to-market timing require proactive compliance budgeting and structured risk mitigation. Companies that invest early in regulatory clarity will reduce time-to-market for premium, high-margin formulations.
Key Thematic Drivers Through 2026
-
Demand-side segmentation: Sports nutrition remains the largest end-market driver for BCAAs, followed by medical and functional food applications. However, the fastest value accrual is occurring where clinical substantiation and clean-label fermentation credentials intersect. Expect buyers to pay a premium for ingredients with documented bioavailability or sustainable fermentation sourcing.
-
Supply and manufacturing: Fermentation-based production continues to scale, with several producers integrating downstream purification to serve pharmaceutical-grade requirements. Capacity additions and technology transfers are reshaping supplier power; vertically integrated producers are better positioned to capture margin uplift and to respond to traceability demands.
-
Regulatory complexity: Ingredient classification, NDI pathways, and cross-jurisdictional regulatory compliance are non-trivial gating factors. Notably, FDA NDI notifications and other approvals have begun to alter competitive dynamics, giving first-movers a window to entrench premium claims in regulated markets.
-
Commercial consolidation: The market concentration metrics indicate a moderately consolidated landscape — top-three and top-five supplier groups hold meaningful share. That concentration creates both barriers for new entrants and opportunities for bolt-on acquisitions to achieve scale and downstream access.
Competitive Landscape — What to Watch in 2026
Our report provides an actionable competitor map highlighting technology strengths, channel focus, and strategic initiatives. Below are strategic takeaways about leading players that will shape near-term competition:
-
Ajinomoto Co., Inc. (Tokyo) — AjiPure® and aminoVITAL® position Ajinomoto at the premium intersection of pharmaceutical-grade and sports nutrition. Their differentiated branding and clinical orientation make them a natural partner or competitor for firms seeking high-margin, claimable products.
-
Kyowa Hakko Bio (Tokyo) — Historically strong in fermented, branded amino acids, Kyowa’s recent business transfer of amino acids and human milk oligosaccharides to another strategic player reflects a corporate refocus and creates an acquisition-led redistribution of advanced fermentation assets across the market.
-
Evonik Industries AG (Essen) — Evonik’s fermentation portfolio and precision feeding solutions underscore its influence in animal nutrition and industrial applications. Recent trade-show visibility and a strategic pricing move for certain amino acids signal active demand management and margin defense tactics in 2026.
-
Meihua Holdings Group (Beijing) — The acquisition of fermentation assets and regulatory approvals positions Meihua as a consolidator with ambitions to advance into higher-value nutraceutical and pharma-grade segments, leveraging scale and regulatory licenses to expand market reach.
-
Fufeng Group, CJ CheilJedang, Daesang, Amino GmbH — These firms collectively represent the manufacturing backbone and regional specialization in feed-grade and food-grade amino acids, while selectively moving toward premium or regulated applications through partnerships, showcases, and acquisition strategies.
Recent Market Moves That Alter 2026 Playbooks
-
Strategic asset transfers and acquisitions in late 2025 have reallocated advanced fermentation technologies and regulatory dossiers, making certain regional supply chains more vertically integrated and changing counterparty risk for buyers and OEMs.
-
Industry participants have intensified trade-show and showcase activity to secure distribution and regulatory footholds; this front-loaded commercial activity is likely to translate to tightened product availability windows through 2026.
-
Selective price adjustments and NDI recognitions highlight that suppliers are actively managing margin with short-term pricing levers while betting on sustained demand for premium and feed applications.
What’s Inside the Full PW Consulting Report (Operational Highlights)
The full BCAA Market study is built for executives and transaction teams. It contains:
-
Detailed market-size history and modeled forecasts (2026–2032) with sensitivity scenarios and downside contingencies tied to regulatory shocks.
-
Go-to-market playbooks by product purity tier (commodity, nutraceutical, pharmaceutical), including price elasticity estimates, channel margin waterfalls, and recommended promotional strategies.
-
Supplier due diligence templates and manufacturing upgrade scorecards — fermented vs. synthetic production economics, capital expenditure benchmarks, and typical lead times.
-
Regulatory pathway maps for major markets, with checklist items to accelerate NDI/novel ingredient submissions, labeling strategies, and pharmacovigilance expectations.
-
M&A and partnership roadmaps: prioritized targets by capability, valuation heuristics, and integration risk matrices — framed to capture synergies in purification, regulatory dossiers, and distribution.
-
Commercial scenarios and stress tests to inform contract structures, inventory buffers, and hedging strategies under constrained supply.
Practical Recommendations for 2026 Executives
-
Prioritize regulatory clarity: Allocate resources to secure pre-market confirmations and NDI pathways where applicable. The first cohorts gaining clear regulatory status will command premium placement in major retail and clinical channels.
-
Target high-margin adjacencies: Pursue premiumization (clinical claims, branded fermentation) over volume growth alone. Incremental margin from specialty applications outpaces volume-driven gains in the near term.
-
Structure M&A with integration-first KPIs: Given market concentration dynamics, bolt-on acquisitions that fill purification, regulatory, or channel gaps deliver faster ROI than greenfield capacity additions.
-
Lock down supply agreements with flexibility: Use multi-year framework contracts with indexed pricing and capacity reservations to hedge against short-term supply tightening and price volatility.
-
Invest in traceability and sustainability narratives: Buyers increasingly demand provenance and fermentation transparency; these investments materially support premium positioning and mitigate regulatory/reputational risk.
Why PW Consulting’s Intelligence Is Different
Our analysis combines transaction-grade financial modeling with commercial channel economics, regulatory foresight, and plant-level production economics. We balance market-level forecasting (with the 2025 base year and 2026–2032 horizon) against pragmatic, near-term operational checklists that leaders can execute within 6–18 months.
Next Steps — Accessing Full Insights
This preview highlights the strategic contours you need to define competitive plans in 2026. For detailed regional, type- and application-level analytics, granular supplier scorecards, and transaction-ready valuation ranges, access the full PW Consulting BCAA Market report. The in-depth segment tables and downloadable financial models are intentionally reserved for the full publication to support confidential decision-making and prioritized outreach.
PW Consulting stands ready to translate these insights into a tailored 90-day action plan for your executive team — from regulatory gap assessments to prioritized acquisition targets and rapid commercial pilots.
For detailed analysis of this topic, please visit the official page: BCAA Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Detonator Market to Hit USD 12,029M by 2032 at 3.42% CAGR
By pmarketresearch, 2026-07-30
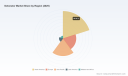
Detonator Market — 2026 Strategic Outlook (PW Consulting)
As companies make capital allocation and portfolio decisions for 2026, clarity about where the detonator market is headed is non‑negotiable. PW Consulting’s Detonator Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes validated market sizing, technology trajectories, and supplier economics into a decision-grade roadmap. The global market has expanded from roughly USD 7.9 billion in 2020 to about USD 9.6 billion in 2025 and — at a compounded annual growth rate of 3.42% across our forecast horizon — is projected to approach the low‑teens billion USD range by 2032. Market structure is moderately concentrated: the top three players collectively hold roughly 30% of value, and the top five about 40% — a dynamic that shapes competitive strategy and partnership calculus.
Detonator Market
Why this study matters for 2026 decisions
-
Timing: 2026 is the inflexion point for product and manufacturing investments. Several leading suppliers completed capacity and automation investments in 2024–2025; entrants and incumbents must decide whether to follow, differentiate, or consolidate.
Detonator Market -
Capital deployment: Firms that wait for perfect certainty will pay a premium in lost share or higher unit costs when demand re‑accelerates. Our analysis turns uncertain signals into explicit investment thresholds and staging plans.
Detonator Market -
Regulatory and customer pull: Lead‑free and precision electronic initiation systems are moving from niche to mainstream in regulated markets. Certification and standards compliance have become tactical gating items for market access.
-
Supply resilience: Recent on‑shoring and regional plant builds underscore supply chain fragility — the right manufacturing footprint choices will materially affect lead times and risk exposure.
What the report delivers — practical, executable content
-
Decision‑grade market sizing and trend diagnostics covering 2020–2032, with baseline, upside, and downside scenarios that embed commodity, regulation, and construction/mining cycle sensitivities.
-
Go‑to‑market playbooks for incumbents and new entrants: channel strategies, service bundling, pricing frameworks, and tender playbooks tailored to mining, industrial, and defense end users.
-
Technology and product roadmaps: actionable recommendations for electronic initiation, lead‑free chemistries, and high‑reliability detonators for aerospace/defense segments, including qualification roadmaps and cost‑to‑serve models.
-
Supply chain and manufacturing diagnostics: factory automation ROI models, localization scenarios, renewable energy integration options, and a supplier risk heatmap to prioritize mitigation actions.
-
Competitive benchmarking and M&A playbook: profiles of strategic peers, capability gaps, acquisition screening criteria, and an integration checklist that preserves regulatory compliance and HSE performance.
-
Procurement and cost engineering templates: unit economics for detonator types, labour and materials sensitivity analyses, and contract structures to balance margin and volume risk.
-
Regulatory impact assessment and ESG roadmap: scenario planning for increasingly stringent environmental standards and defense/aerospace qualification requirements.
High‑level macro takeaways (what senior leaders must internalize)
-
Measured but persistent growth. The market’s expansion from about USD 7.9 billion in 2020 to USD 9.6 billion in 2025, and our projection into the 2032 timeframe, reflects steady demand linked to mining activity, construction cycles, and defense qualification windows. The 3.42% CAGR masks uneven pockets of faster adoption where precision initiation systems and lead‑free solutions have found higher willingness‑to‑pay.
-
Technological bifurcation. Electronic and programmable initiation systems are differentiating on safety, timing precision, and data integration (blast analytics). Parallel advances in lead‑free initiation chemistries are creating regulatory and commercial pull — early movers capture premium pricing in regulated jurisdictions.
-
Manufacturing modernization is a competitive lever. Case examples from recent years show firms investing in fully automated plants and renewable energy at detonator facilities to reduce operating expense and decouple from energy‑price volatility. These investments shorten lead times and lower total cost of ownership for large buyers.
-
Supply chain topology matters. Regional plant openings and on‑shore capacity demonstrate an industry move toward mitigating logistics, compliance, and geopolitical risk. Buyers are increasingly demanding local content and faster replenishment cycles, altering procurement dynamics.
-
Concentration creates transactional and partnership opportunities. With the top three to five firms holding a meaningful but not overwhelming share of value, there is room for targeted consolidation, bolt‑on acquisitions, and strategic alliances — especially where specialized electronic or defense‑qualified capabilities are scarce.
Competitive landscape — strategic reads on leading players
-
Dyno Nobel: Continuing investments in factory automation and energy resilience mark Dyno Nobel as an operator focused on scale efficiency and sustainability. Their portfolio emphasis on electronic initiation systems and automated plants positions them to serve large, safety‑conscious mining clients.
-
Orica Limited: Orica’s push on lead‑free electronic systems and formal certifications reflects a product differentiation strategy aligned with regulatory markets. Their certification milestones reduce adoption friction in Europe and other regulated geographies.
-
Austin Powder Company: With offerings spanning electronic, electric, and non‑electric systems, Austin Powder combines product breadth with industrial blasting services — a useful model for mixed‑portfolio operators seeking relational contracts with mines and civil contractors.
-
MAXAM and Enaex: Both firms illustrate regional strength coupled with focused electronic solutions. Enaex’s programmable detonators and MAXAM’s electronic lines show the increasing value of precision timing in blast optimization services.
-
Specialty suppliers (Chemring, Excelitas, Teledyne): These players secure high‑value, technically demanding pockets — defense, aerospace, and specialized industrial clients — where qualification standards and traceability requirements create higher barriers to entry.
-
Regional manufacturers and new capacity (BME Mining Canada, Kırlıoğlu, Nelson Brothers, Ideal Mining Services): Recent plant openings and local production capabilities highlight an industry pivot to mitigate supply chain risks and meet regional content expectations.
Recent industry moves to watch (2024–2026)
-
Automation and energy initiatives: Several major manufacturers completed or expanded automated electronic detonator plants and renewable energy installations at detonator/booster sites, reducing operating cost volatility and improving sustainability credentials.
-
Regional capacity builds: New plant openings in established mining jurisdictions reflect a strategic push to de‑risk logistics and shorten lead times for critical initiation products.
-
Product certification and lead‑free adoption: Market leaders secured certifications that enable the commercial rollout of fully lead‑free electronic detonators across regulated markets, unlocking procurement pipelines in Europe and beyond.
Strategic imperatives for 2026
-
Prioritise capability bets: Decide whether to invest in in‑house electronic initiation, buy capabilities through M&A, or secure long‑term supply agreements. The right choice depends on scale, end‑market mix, and regulatory exposure.
-
Localize selectively: Use a triage of lead time, regulatory risk, and customer demand to determine where regional manufacturing is justified versus where centralized, low‑cost production remains optimal.
-
Accelerate qualification programs: For players targeting defense, aerospace, or highly regulated mining markets, front‑loading qualification (and certification) shortens commercial ramp timelines and creates durable differentiation.
-
Embed digital value: Electronic detonators that provide timing data and blast analytics can be monetized through service contracts and analytics subscriptions — turn a component sale into a recurring revenue stream.
-
Mitigate raw‑material and labour risks: Scenario plans should quantify exposure to specialized labour shortages and shifts in explosive feedstock; hedges and dual‑sourcing arrangements are no longer optional.
-
Use M&A to fill capability gaps: In a market with moderate concentration, bolt‑ons can provide rapid access to electronic know‑how, regional footprint, or defense qualifications without the time and compliance burden of greenfield builds.
How PW Consulting supports your 2026 agenda
-
Bespoke strategy workshops that convert the global forecast and supplier benchmarking into an executable 12–36 month roadmap.
-
Investment‑grade financial models and scenario simulators, calibrated to your cost base and optionality points (manufacturing, qualifications, product R&D).
-
M&A origination and diligence support: targeted screening, regulatory pathway mapping, and integration playbooks that preserve HSE and certification continuity.
-
Procurement transformation: supplier scorecards, contract playbooks, and negotiation templates designed to secure resilient supply at predictable unit economics.
For senior leaders preparing 2026 capital and commercial plans, the choice is clear: act on high‑confidence signals now or accept the strategic drag of catching up later. PW Consulting’s Detonator Market report provides the data, scenarios, and playbooks to make those decisions with conviction. The executive summary above highlights core insights and practical implications; the full report contains the detailed segment tables, regional demand matrices, and supplier scorecards that underpin these recommendations. Access the complete intelligence package to move from strategic intent to execution-ready plans.
For detailed analysis of this topic, please visit the official page: Detonator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Natural Ferulic Acid Market to Reach USD 90.22 Million by 2032 at 6.7% CAGR
By pmarketresearch, 2026-07-30
Natural Ferulic Acid (CAS 1135-24-6): Strategic Preview for 2026 Decision‑Makers
Executive snapshot
Natural ferulic acid has moved from a niche specialty ingredient to a commercially relevant natural actives category with clear implications for sourcing, formulation and regulatory positioning. Our latest market study (base year 2025) models a steady expansion from a global market sized in the mid‑tens of millions of USD in 2025 to a near‑nine‑figure opportunity by the end of the 2026–2032 forecast window at an implied compound annual growth rate of 6.7%. For 2026 corporate planning, this is not a marginal trend—it's a multi‑year demand trajectory that should inform procurement, R&D prioritization and go‑to‑market strategies across cosmetics, nutraceuticals and specialty food applications.
Natural Ferulic Acid (CAS 1135-24-6) Market
Why this research matters in 2026
- Actionable horizon: The report translates a medium‑term CAGR into discrete strategic options—sourcing hedges, product roadmaps and M&A triggers—that are executable within 12–24 months.
- Risk‑calibrated guidance: We combine market sizing with supply‑chain sensitivity analysis so executives can translate growth expectations into contract structures that protect margins against agricultural feedstock variability.
- Regulatory & positioning playbook: As clean‑label and “naturally sourced” claims gain regulatory scrutiny across core markets, the study outlines compliance pathways and labeling strategies that preserve premium positioning without introducing litigation risk.
Market trajectory and what the numbers imply
The market’s projected growth profile—a consistent mid‑single‑digit CAGR—reflects a balance of demand expansion in higher‑value applications (cosmetics and nutraceuticals) and ongoing supply constraints tied to natural extraction. In practical terms, companies planning capacity, budgets or product launches in 2026 should assume a tightening supply environment relative to demand growth, which will put a premium on long‑term supplier relationships, vertically integrated sourcing, or alternative feedstock strategies.
Natural Ferulic Acid (CAS 1135-24-6) Market
Our modeling shows a clear inflection: incremental demand is strong enough to reward early movers who secure diversified raw materials and who can convert supply reliability into preferred supplier status with OEMs and formulators. For investors, the growth trajectory supports disciplined capital deployment into extraction capacity, formulation platforms, and bolt‑on targets that deliver immediate route‑to‑market synergies.
Natural Ferulic Acid (CAS 1135-24-6) Market
Supply‑side dynamics: raw material dependency and cost volatility
Natural ferulic acid is primarily extracted from agricultural byproducts—most notably rice and wheat brans. That biologically anchored supply base creates two structural realities. First, production costs and yield are seasonal and tied to crop cycles; second, geographic concentration of processing capacity matters because logistics and feedstock proximity materially affect delivered cost and lead time.
- Price risk: Agri‑feedstock volatility can propagate quickly through extraction margins. Fixed‑price contracts and index‑linked purchasing are both viable mitigants; the optimal choice depends on a firm’s risk tolerance and balance‑sheet flexibility.
- Feedstock diversification: Procuring from multiple cereal sources and investing in extraction process flexibility reduces single‑source risk and creates negotiating leverage.
- Technical differentiation: Extraction efficiency and downstream purification quality are critical differentiators. Players with improved yield or lower impurity profiles command a valuation premium in B2B negotiations.
Demand dynamics and regulatory tailwinds
Demand is being driven by two converging forces: formulators seeking natural antioxidant and UV‑stabilizing actives, and consumer preferences shifting toward clean‑label, naturally derived ingredients. Regulatory regimes in major markets increasingly favor transparency about ingredient origin, which benefits genuinely natural suppliers but increases validation and documentation requirements.
- Cosmetics and nutraceuticals lead: High‑value formulations that credibly leverage natural sourcing and scientifically backed claims create the fastest margin expansion opportunities.
- Compliance costs: Expect higher compliance and certification costs for suppliers that wish to claim “natural” across multiple jurisdictions—companies must budget for traceability systems, third‑party validation and extended product dossiers.
- Private‑label and brand risk: Brands that use low‑cost synthetic alternatives may face consumer scrutiny; as a result, many mid‑to‑premium brands will pay a premium for documented natural sourcing.
Competitive landscape — what incumbents reveal about strategic options
The competitive field is characterized by a mix of long‑standing specialists, regional champions and vertically integrated vegetable oil/bran processors. That mix produces a market that is neither a pure commodity race to the bottom nor a closed oligopoly—there is room for differentiation based on feedstock, purity, formulation support and customer intimacy.
- Zhejiang Delekang Food Co., Ltd. (China) — A veteran producer focused on rice bran extraction with a track record of cost‑competitive supply for food and cosmetics customers. Their scale and commodity know‑how make them an attractive partner for volume buyers seeking competitive pricing.
- TSUNO Group Co., Ltd. (Japan) — Notable for patented high‑dosage UV‑absorbing formulations and ongoing product development. Recent 2026 activity includes exhibition at major trade shows and new consumer launches leveraging domestically sourced rice‑bran ferulic acid, signaling an integrated approach from feedstock to finished consumer format.
- Okayasu Shoten, Oryza Oil & Fat Chemical, HSF Biotechnology, Shaanxi Guanjie, Hubei Yuancheng and Xi'an App Chem — These firms collectively illustrate the spectrum of capabilities: advanced extraction efficiency, high‑purity manufacturing, feedstock specialization (wheat vs rice bran) and targeted application expertise (pharma vs cosmetics). Each represents a different strategic partner archetype—cost leader, technical innovator, or regulatory‑compliant supplier.
For buyers and investors, the takeaways are clear: leverage supplier archetypes to match strategic needs (scale vs. purity vs. development support), and expect that top domestic specialists and regional champions will continue to shape pricing and availability in their home markets.
Strategic playbook for 2026 — five immediate actions
- Lock strategic offtake where price/volume terms align with scenario planning. Prioritize multi‑year agreements with flex windows tied to feedstock indices to balance risk and cost predictability.
- Invest in feedstock diversification and dual‑sourcing. Even small additional sourcing options materially reduce exposure to seasonal shortages or regional crop failures.
- Accelerate formulation partnerships that turn natural ferulic acid from an ingredient into a differentiating consumer claim. Co‑developed formulations reduce time‑to‑market and create switching costs for customers.
- Build regulatory dossiers and traceability. For premium positioning, expect to invest in third‑party certifications and digital traceability—these are now table stakes in key markets.
- Evaluate targeted M&A or JV activity in 2026–2027. With the market growth profile, small bolt‑ons that expand feedstock access, purification capability or application expertise can generate rapid strategic payback.
Scenario considerations (practical and quick to model)
Use three short scenarios when stress‑testing capacity or pricing decisions: a baseline aligned with the mid‑single‑digit CAGR, an upside driven by accelerated cosmetic & nutraceutical adoption, and a downside driven by raw‑material shocks or regulatory friction. The levers that most affect outcomes are feedstock price volatility, conversion efficiency and the pace of premium formulation adoption. In our models, these three variables explain the majority of variance in margin outcomes over the next three years.
What the full report delivers (practical contents)
Our study is designed for executives and investment teams who need executable intelligence, not just charts. Highlights include:
- Detailed market sizing and growth drivers (2020–2025 historical, 2026–2032 forecast) with build‑ups that link demand by application to unit economics.
- Supply‑chain maps and supplier profiles with capability matrices and contact‑ready checklists for commercial negotiations.
- Sensitivity and scenario models you can adapt to internal cost structures, including raw‑material elasticity tables and break‑even curves for different contract structures.
- Regulatory and claims matrix for major markets outlining compliance steps to preserve “natural” labeling and minimize downstream litigation risk.
- Commercial playbooks for buyers, formulators and investors—pricing strategies, co‑development templates and M&A decision matrices.
Final perspective and recommended next step
2026 is a decision inflection point for many organizations exposed to natural actives. The growth path for natural ferulic acid is substantial enough to warrant explicit strategy work—procurement hedging, formulation partnerships, and selective capacity investments are now timely. However, converting growth into margin requires deliberate choices about supplier archetypes, feedstock strategy and regulatory positioning.
To move from directional insight to operational decisions, access to the full report is essential: it provides the granular models, supplier contact frameworks and contract language that enable rapid execution. PW Consulting’s full study is structured as a playbook—designed to convert the 6.7% CAGR opportunity into measurable commercial outcomes over the next 18 months.
For teams planning 2026 budgets, product launches or M&A screens, start with a focused review of the supply‑risk chapter and the scenario model that aligns best with your cost structure—then use the supplier profiles and negotiation templates to convert insight into secured access.
For detailed analysis of this topic, please visit the official page: Natural Ferulic Acid (CAS 1135-24-6) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hot-Work Die Steels Market to Reach USD 344.8M by 2032 (6.98% CAGR)
By pmarketresearch, 2026-07-30
Hot-Work Die Steels Market — Strategic Preview for 2026 Decision-Making
Executive snapshot
The Hot-Work Die Steels market has moved from a niche durability play into a strategically material segment of advanced tooling supply chains. Measured on a global basis, the market reached USD 215.0 Million in our base year (2025) after recovering from pandemic-era volatility and is projected to expand at a compound annual growth rate (CAGR) of 6.98% across the 2026–2032 forecast window. By 2032 the market is expected to exceed USD 340 Million, driven by demand for higher-duty dies, tighter tolerances in forged and cast components, and rising adoption of alloy and process improvements that extend die life under severe thermal cycling.
Hot-Work Die Steels Market
Why this research matters for 2026 corporate strategy
For manufacturing leaders, die makers and materials buyers, 2026 is shaping up as an inflection year. Policy shifts (including new carbon border adjustments and emissions limits), consolidation among European suppliers, and continued product engineering advances are simultaneously compressing supplier choice and raising the stakes of sourcing and innovation decisions. This research presents the market-level view required to align sourcing, R&D investment, and M&A priorities with near-term constraints and mid-term opportunity.
Hot-Work Die Steels Market
-
Timing: With new tariffs and carbon-related measures taking effect around 2026 in key markets, procurement and localization strategies must be set now to avoid margin erosion.
Hot-Work Die Steels Market -
Technology pivot: Thermal-management improvements and cleaner metallurgy are changing the value equation for die steels — you either play the long-life, premium-die game or compete on lower-cost, higher-replacement models.
-
Consolidation window: Recent and announced integrations (notably the GMH Gruppe integration in early 2026) open both supply-side scale and consolidation arbitrage for strategic buyers and partners.
What the report delivers — practical, executable content
This market study is structured to support immediate 2026 decision cycles. It blends quantitative market sizing and scenario forecasting with operational playbooks that translate insight into actions. Key deliverables include:
-
Robust market sizing and top-line forecasts for 2026–2032 based on sector drivers and sensitivity to raw-material and regulatory scenarios.
-
Supply-chain diagnostics: identification of pinch-points for high-purity alloy inputs (chrome, molybdenum, vanadium), logistics risk maps and alternative sourcing ladders designed for rapid deployment.
-
Regulatory impact modelling that translates EU emissions rules and carbon border adjustments into cost-per-ton and sourcing penalty vectors for different supply origin scenarios.
-
Commercial playbooks: supplier selection scorecards, long-term off-take vs spot procurement decision matrices, and procurement contracting templates oriented to die-life total cost of ownership (TCO).
-
R&D and product strategy guidance: priority areas for alloy chemistry and heat-treatment investments, and a roadmap to deploy thermal-conductive and high-toughness grades for specific die-making use cases.
-
M&A and partnership scenarios: where scale matters (production capacity, ESR/VIM facilities, vacuum hardening expertise) and how to structure deals to unlock synergies quickly.
Market dynamics and near-term catalysts
Several interacting forces will define competitive advantage in 2026 and beyond:
-
Material science advances. Suppliers are launching grades with improved thermal conductivity and high-temperature strength — an example being a new hot-work grade aimed at extending mold service life and reducing operating cost per part.
-
Regulatory pressure. European limits on emissions from electric arc furnaces and the roll-out of carbon border adjustment mechanisms require buyers to quantify embedded carbon and evaluate near-shore or compliant suppliers.
-
Standards-driven quality expectations. ISO specifications governing impact toughness for hot-work die steels impose minimum properties that affect both vendor qualification and warranty exposure.
-
Raw material tightness. Premium hot-work grades require high-purity chrome-molybdenum-vanadium inputs; supply constraints or price shocks in these alloys disproportionately affect specialty steel pricing and availability.
Operationally, the sector is also experiencing a labor- and skills-driven shift: specialized heat-treatment proficiencies, particularly vacuum hardening and ESR processing know-how, have risen in importance (with notable increases in required skilled labor since 2024), altering where and how value is captured in the supply chain.
Competitive landscape — who moves the market
The market remains fragmented: the leading companies together account for roughly a quarter of total market revenue, leaving a long tail of regional and specialty producers. This fragmentation breeds both competition and acquisition opportunity.
-
Japanese leadership in alloy R&D and cleanliness: companies such as Daido Steel, Sanyo Special Steel, Nippon Koshuha, Proterial and several specialty mills continue to push metallurgical boundaries with grades optimized for die casting, forging and extrusion. Their strengths include vacuum metallurgy, high-purity product lines and strong OEM relationships in automotive and industrial equipment.
-
European premium capability and consolidation: suppliers such as voestalpine High Performance Metals, Swiss Steel Group and Aubert & Duval combine advanced processing (ESR, VIM) with engineering services. Swiss Steel’s recent grade launch (late 2025) and the GMH Gruppe integration (completed in January 2026) are examples of how European players are seeking product-led and scale-led differentiation.
-
Regional producers and capacity plays: Asian producers across China and India (including several large-scale steelmakers and specialty mills) provide competitive supply for commodity-lean applications, giving buyers options where carbon and regulatory exposure are manageable or where cost pressure is paramount.
-
North American specialists: boutique tool-steel producers and service-focused companies (e.g., Hudson Tool Steel and Southern Tool Steel) maintain close relationships with die shops and OEMs, offering localized response and aftermarket services that reduce downtime.
For buyers and strategic planners, the implications are clear: metallurgical superiority and low-carbon production credentials command premiums; meanwhile, geographic footprint and service models determine price-to-value in procurement negotiations.
Strategic implications and recommended levers for 2026
Based on our synthesis, executives should execute a coordinated set of actions across four dimensions in 2026:
-
Secure supply and diversify alloy sourcing: establish dual-sourcing for high-purity alloy inputs, and structure long-term contracts that include embedded carbon clauses to address CBAM exposure.
-
Prioritize product and process differentiation: invest in thermal-management and surface engineering to extend die life, and partner with suppliers who offer ESR/VIM capacity and demonstrable low-CO2 footprints.
-
Operationalize locale and compliance: where tariffs or carbon mechanisms bite, consider near-shore production or co-investment in compliant mills to preserve margin and lead times.
-
Use M&A and partnerships tactically: pursue bolt-on acquisitions or JV partnerships to acquire vacuum hardening, ESR capacity or specialty alloy lines rather than broad horizontal deals — the market rewards depth over scale for technical capabilities.
How to use this report in your 2026 planning cycle
We designed the research to be immediately actionable for board-level strategy sessions and operational procurement teams alike. Practical use-cases include:
-
Baseline scenario planning: overlay the report’s market forecast and regulatory impact analysis onto your volume and margin forecasts to derive adjusted capital and working-capital plans.
-
Supplier scorecarding: adopt the report’s supplier evaluation templates to re-run vendor assessments with carbon, metallurgy and service response incorporated.
-
Deal readiness: use the M&A playbooks and synergy schematics to evaluate target mills and to fast-track integration planning where acquisitions are pursued.
-
R&D and CapEx prioritization: align alloy development projects and heat-treatment investments with the report’s timing for premium grade adoption to maximize payback.
Conclusion — the strategic choice for 2026
The hot-work die steels market is neither a low-risk commodity arena nor a purely bespoke boutique sector: it sits at the intersection of high-precision metallurgy, regulatory exposure and operational intensity. For 2026, companies that move early to secure compliant alloy supply, partner on high-performance grades, and rationalize service-oriented offerings will capture outsized value as the market grows at a near 7% CAGR toward 2032.
This preview intentionally highlights trends, competitive dynamics and decision levers while preserving the granular subsegment and regional breakdowns that are core to procurement and investment actions. For the full data tables, segment-level forecasts and supplier scorecards that operational teams require for contract and capital decisions, access the complete report on our site and download the supporting appendices.
For detailed analysis of this topic, please visit the official page: Hot-Work Die Steels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com