

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Plate-fin Heat Exchanger Market: USD 142.0M in 2025, 4.9% CAGR to 2032

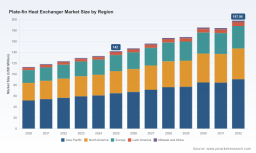
Plate-fin Heat Exchanger Market: Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a forward-looking synthesis of our Plate-fin Heat Exchanger (PFHE / brazed aluminum plate-fin heat exchangers — BAHX) market study designed to equip executives, procurement leaders, and investors with the strategic context they need for 2026. This briefing highlights the research’s strategic value, the operating dynamics that will shape near-term choices, and the competitive vectors that matter — while deliberately omitting granular segment tables and confidential split data to preserve the report’s proprietary value. For the full quantitative detail and downloadable modeling assets, please consult the PW Consulting report landing page.
Plate-fin Heat Exchanger Market
Why this study matters now
-
A maturing growth profile: Our analysis uses 2025 as the base year and projects the global plate-fin heat exchanger market to grow at a compound annual growth rate (CAGR) of 4.9% through the forecast window (2026–2032). That trajectory reflects steady expansion driven by industrial recovery, rising demand in cold-chain and cryogenics, energy transition projects, and near-term investments in domestic supply chain resilience.
Plate-fin Heat Exchanger Market -
Decision-making inflection in 2026: Companies planning CAPEX cycles, vendor consolidation, or regional manufacturing footprints in 2026 must synthesize regulatory updates, raw-material exposure, and supplier concentration into their procurement and engineering timelines. Our study converts those inputs into actionable scenarios and investment lenses.
Plate-fin Heat Exchanger Market -
Practical utility: This is not a high-level narrative. The report is rooted in a consolidated dataset and pragmatic tools — procurement scorecards, vendor due-diligence templates, integrity and safety checklists aligned to industry standards, and scenario-based cash-flow implications for design and material choices.
What the report delivers — operational content you can act on
-
Market sizing & trajectory: A reconciled market-size series calibrated to industry shipment and supplier-revenue data, with forecasts under three demand scenarios (baseline, accelerated energy-transition, downside macro shock).
-
Methodology transparency: Detailed forecasting assumptions, sensitivity matrices, and an explanation of the drivers behind our 4.9% CAGR. This lets teams re-run the model with proprietary inputs (e.g., plant-level load growth, project timelines).
-
Procurement playbook: Supplier selection criteria, total cost of ownership (TCO) templates, contract clauses for warranty and integrity, and a supplier-risk heat map keyed to material supplies and trade policy exposure.
-
Supply-chain mapping: Practical diagrams showing common raw-material routes, choke points for brazed-aluminum fabrication, and strategies that large OEMs and EPCs use to de-risk lead times and maintain quality.
-
Standards & compliance pack: An easy-reference digest of ALPEMA guidance, API alignment issues, and recommended internal checkpoints for integrity operating windows — framed as checklists for engineering and safety teams.
-
Case-driven guidance: Project-level case studies illustrating trade-offs (material selection, brazing processes, repairability, lifecycle costs) and a short-list of mitigation measures that preserve thermal performance while lowering lifecycle risk.
-
Investment and M&A intelligence: A tactical view of buyer-seller dynamics, valuation drivers, and likely consolidation vectors — for corporate development teams and private equity looking at mid-market BAHX specialists.
Key dynamics shaping supplier and buyer strategy
-
Standards evolution and operational implications: ALPEMA’s active role in clarifying its 4th edition standards — and its formal responses to the 2nd edition of API 668 — have immediate implications for engineering acceptance criteria, vendor qualification, and post-installation integrity programs. Buyers who internalize these updates early can shorten acceptance cycles and reduce retrofit exposure.
-
Raw-material and tariff pressure: Aluminum remains a medium-influence input for the BAHX value chain. Tariff tensions and policy-driven sourcing shifts are prompting manufacturers and large end-users to localize critical fabrication steps or hold strategic buffer inventories. Our supply-chain scenarios quantify the trade-offs between localized capacity build-out and incremental unit-costs.
-
Concentration and competitive tension: The market displays moderate concentration; the top tier of global suppliers accounts for a material share of industry revenue, but a broad long tail of specialist fabricators remains active. This balance favors sophisticated buyers who can leverage competitive bidding while maintaining technical prerequisites for performance and integrity.
-
Technology and application cross-currents: Advances in brazing processes, materials science, and quality-testing technologies are reducing failure modes and expanding feasible operating envelopes. Simultaneously, opportunities in LNG, industrial gas, and energy-efficiency applications are catalyzing demand for higher-specification units — with procurement consequences for cycle time and capital intensity.
Competitive landscape — who sets the technical baseline
The competitive map is anchored by established global players and a distributed base of regional specialists. Our report provides a vendor framework that reconciles technology capability, geographic reach, and service models. Below is a high-level synopsis of the primary global actors discussed in the study (profiles in the full report include capability matrices and vendor scorecards):
-
Linde Engineering (Munich, Germany): A leading manufacturer of brazed aluminum plate-fin heat exchangers with a long operational history. Linde’s installed base and ALPEMA participation underpin its engineering leadership and cross-border project execution capability.
-
Chart Energy & Chemicals, Inc. / Chart Industries (La Crosse, Wisconsin, USA): A major producer of vacuum-brazed aluminum PFHEs, with strong positioning in cryogenic and process applications. Chart’s product family is frequently specified for industrial gas and cryogenic systems.
-
Kobe Steel, Ltd. (Takasago, Hyogo, Japan): Known for high-performance PFHEs tailored to petrochemical, LNG, and industrial gas processing, Kobe Steel brings manufacturing scale and application-specific engineering.
-
Sumitomo Precision Products Co., Ltd. (Takarazuka, Osaka, Japan): A specialist with decades of experience in aluminum plate-fin heat exchangers, focused on cryogenic and precision industrial applications.
-
Alfa Laval (Lund, Sweden): Broadly recognized for compact PFHEs across HVAC, refrigeration, food processing, and industrial thermal management, Alfa Laval’s portfolio is oriented toward modularity and serviceability.
-
Eaton Corporation (Dublin, Ireland): Supplies custom vacuum-brazed aluminum PFHEs for liquid-to-liquid and liquid-to-air applications across automotive, aerospace, and industrial segments, with emphasis on lightweight and high-performance designs.
Strategic implication: The competitive set blends heavy-industrial incumbents (with deep project experience and large installed bases) and engineering-centric firms offering specialized product platforms. For buyers, this means evaluating suppliers on three axes: thermal performance, supply-chain risk (including material sourcing), and aftermarket integrity services.
Recent events and regulatory signals to watch
-
Industry convenings continue to accelerate dissemination of innovations and buyer-supplier matchmaking. Regional trade shows and technical expos in 2025–2026 offered early previews of next-generation PFHE architectures and testing protocols.
-
ALPEMA updates in late 2025 — including addenda and FAQs to the 4th Edition and a formal response to API 668’s second edition — elevate the importance of documented integrity operating windows and manufacturer-authorized maintenance regimes. Organizations that do not align inspection and acceptance processes to these standards will face higher operational friction and insurance scrutiny.
-
Supply-chain localization trends, driven by tariff conflicts and strategic sourcing policies, are creating selective opportunities for nearshore fabrication and aftermarket service providers. Our report quantifies the cost-per-unit of de-risking strategies versus the latency impact on project execution.
How to use the report in 2026 strategic planning
-
Procurement & supply-chain teams: Use the PW Consulting procurement templates to reconfigure RFQs around TCO and integrity risk, not just capex price. The report’s vendor scorecards help prioritize supplier trials and pre-qualification windows to align with upcoming projects.
-
Engineering & operations: Integrate the ALPEMA compliance checklists and integrity operating window guidance into commissioning and maintenance protocols. Our scenarios help quantify the trade-off between higher-specification units and lifecycle maintenance exposure.
-
Corporate development & investors: The M&A chapter isolates valuation levers (installed-base service revenue, proprietary fabrication capability, geographic access to key end-markets) and highlights likely consolidation targets and timing windows.
What we intentionally withhold here — and why
In line with our “trailer” principle, this briefing intentionally omits detailed segment-level splits by region, type, and application — and it does not disclose proprietary unit-level revenue tables embedded in the full model. Those datasets are part of the PW Consulting report package and are available through our web portal for licensed subscribers. This approach preserves the strategic advantage for decision-makers who need replicable numbers and downloadable financial models.
Closing guidance — three tactical moves for 2026
-
Short-term procurement: Recast RFQs to include integrity and lifecycle clauses aligned with ALPEMA and API expectations; quantify the premium for local fabrication versus extended lead times.
-
Operational resilience: Establish material hedging or strategic vendor partnerships focused on aluminum component continuity; expect modest cost increases tied to localization but measurable reductions in delivery risk.
-
Strategic scanning: Monitor M&A activity among mid-market fabricators and OEMs; these will be the most likely consolidation targets for companies seeking to build regional service networks and aftermarket revenues.
For the full dataset, downloadable forecasting model, vendor scorecards, and a step-by-step procurement playbook tuned for 2026 execution, visit the PW Consulting Plate-fin Heat Exchanger Market report page. The full report is structured to be both a strategic primer and an operational workbench for teams executing CAPEX, sourcing, or M&A activities this year.
For detailed analysis of this topic, please visit the official page: Plate-fin Heat Exchanger Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com