

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Nylon-MXD6 Market to Grow at 5.85% CAGR, Reaching USD 749M by 2032

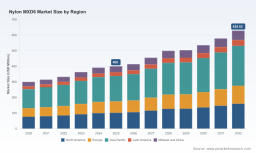
Nylon‑MXD6 Market — 2026 Strategic Outlook and Decision‑Grade Intelligence
As companies set their 2026 strategic plans, Nylon‑MXD6 has moved from a niche performance polymer to a commercially strategic material across packaging, automotive, and select engineering markets. PW Consulting’s latest Nylon‑MXD6 Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes quantitative forecasting, supply‑chain mapping, and actionable strategy frameworks to convert material science advantage into commercial value. The market reached approximately USD 506 million in 2025 and, under our central scenario, is projected to expand at a 5.85% CAGR through the 2026–2032 forecast window — reaching the high‑hundreds million range by 2032. This report is designed as an operational roadmap for procurement leads, product managers, and corporate strategy teams who must make investment decisions in 2026 with a 3–7 year horizon.
Nylon-MXD6 Market
Why Nylon‑MXD6 matters for 2026 decisions
-
Performance economics: MXD6’s unique semi‑aromatic backbone delivers barrier performance and thermal stability that bridge commodity nylons and engineering polymers — enabling downsizing, weight savings, and sustainability claims without compromising shelf life or mechanical integrity.
Nylon-MXD6 Market -
Commercial inflection: The market has matured from early adopters to supply‑constrained mainstream buyers. Historical growth from the early 2020s through 2025 demonstrates both demand elasticity and capacity responses, creating a window where timely strategic moves (sourcing, licensing, or co‑development) can materially change cost and market positioning.
Nylon-MXD6 Market -
Regulatory and sustainability vectors: Certification pathways (notably ISO 22095 mass‑balance routes) now permit bio‑content nylon variants without performance tradeoffs, opening packaging end‑markets that prize renewable content while maintaining barrier integrity.
What this study delivers (practical, decision‑ready contents)
-
Robust market model: A bottom‑up revenue model covering 2020–2025 historicals and 2026–2032 forecasts. The model quantifies demand drivers and sensitivity to feedstock and end‑market cycles. High‑granularity time series are provided for subscribers (note: detailed segment revenue tables are available within the full report).
-
Scenario packs: Three executable scenarios (Base, High‑Adoption, Supply‑Shock) with trigger matrices that translate macro inputs—feedstock price volatility, regulatory shifts, and capacity additions—into P&L and EBITDA impacts for manufacturers and converters.
-
Supply‑chain maps and risk heatmaps: Upstream monomer flows, critical dependencies on MXDA synthesis pathways, and exposure diagnostics for feedstock swings—essential for procurement and hedging strategies.
-
Commercial playbooks: Go‑to‑market options for polymer producers, compounders, and converters including licensing models, tolling partnerships, and joint R&D structures to enable faster market entry or margin protection.
-
Deal and M&A compass: A prioritized list of acquisition archetypes and red flags for corporate development teams, alongside valuation sensitivity to capacity additions and certification premiums.
-
Competitor intelligence dossiers: Strategic positioning, technology licensing footprints, and product portfolios for the industry’s active players — enabling benchmarking and counter‑strategy development.
Key market dynamics every executive must factor into 2026 plans
-
Feedstock volatility is not academic: MXD6 production relies on MXDA monomer (synthesized from m‑xylene and ammonia). Historical analysis shows crude‑linked feedstock swings that can exceed 30% in short cycles; procurement strategies that ignore hedging, vertical integration, or alternative feedstocks risk margin erosion during pricing spikes.
-
Certification changes are creating premium pockets: Mass‑balance certification (ISO 22095) has enabled the commercial launch of bio‑sourced MXD6 blends. Newly announced grades with certified renewable content convert technical sustainability claims into procurement‑eligible specs for large consumer packaged goods companies.
-
Domestic capacity shifts alter bargaining power: New pilot and ramp projects targeting local supply (particularly in China) are changing traditional trade flows and shortening lead times—an important consideration for firms looking to lock inbound supply or negotiate long‑term offtake.
-
Market concentration is material: The industry shows a moderate concentration at the top; incumbent technology owners and their licensed producers retain preferred access to specialized film‑grade and barrier‑enhanced variants, shaping pricing and co‑development dynamics.
Competitive landscape — strategic implications
The competitive map blends entrenched licensors and nimble compounders. A few firms hold core technology and brand cachet for MXD6 production, with additional licensed and regional producers closing the supply gap or competing on cost‑engineered compounds.
-
Technology owners and licensors: Established licensors with proprietary MXDA polymerization technology possess IP that creates high barriers for full‑performance grade replication. Their strategic options include licensing expansion, co‑branding for specialty grades (e.g., barrier‑enhanced films), and premium pricing for certified bio blends.
-
Regional compounders and long‑fiber suppliers: Compounders offering LFT‑reinforced MXD6 and filled compounds enable new engineering use cases (structural automotive, durable consumer goods) where material substitution can create value through part count reduction or weight savings.
-
New domestic entrants: Recent pilot capacity approvals and ramp announcements evidence a pivot toward import substitution in some markets. These entrants will focus on volume, cost competitiveness, and local certification to win contracts with domestic converters or converters seeking de‑risked supply chains.
For corporate strategists, these dynamics imply three tactical vectors for 2026: (1) secure differentiated feedstock pathways and certification to capture sustainability premiums, (2) pursue selective partnerships with licensed technology owners or licensed producers to access high‑value grades, and (3) hedge near‑term demand via flexible sourcing agreements or tolling arrangements while evaluating capex for longer‑term vertical integration.
Recent developments that change the 2026 calculus
-
Commercial bio‑graded launch: A leading technology owner recently launched an MXD6 grade with approximately 25% bio‑sourced MXDA via an ISO 22095 mass‑balance-certified pathway. This product shifts the certification barrier and enables adoption by CPGs with strict renewable content thresholds.
-
Pilot‑to‑scale pushes: Several suppliers have announced pilot capacity projects with fast‑track plans to scale. Early pilot approvals demonstrate regulatory support in targeted jurisdictions and indicate a near‑term increase in available supply that could pressure regional premiums.
How to use the report in 2026 planning cycles
-
Procurement: Use the report’s price sensitivity and feedstock exposure models to design multi‑tier contracts (indexation + floor, strategic corridors, or options) that limit upside cost exposure while maintaining supply security for 2026 launches.
-
Product development: Leverage the material substitution matrix and barrier performance banding to prioritize MXD6 trials for packaging lines where shelf life or downgauging unlocks margin expansion.
-
Capex and M&A: Apply the scenario outputs to capex timing decisions; evaluate bolt‑on buys in compounders or licensed producers when projected regional supply tightness exceeds acceptable risk thresholds.
-
Sustainability and regulatory: Integrate certification pathways into your supplier evaluation checklist; ISO 22095‑compliant mass‑balance products can reduce time‑to‑market for renewable claims.
What PW Consulting’s Nylon‑MXD6 Market report does not publish here
To preserve the strategic sensitivity of core segment economics and to follow our “trailer” principle, this introduction outlines the modeling approach and the strategic implications without publishing granular segment‑level revenue breakdowns or unit pricing matrices by region and application. The full study includes downloadable excel models, granular regional and application segment tables, vendor scorecards, and bespoke scenario outputs — all accessible via the report landing page.
Call to action for 2026 leaders
If you are evaluating raw material sourcing, product reformulation, capital allocation or M&A in 2026, this report converts market noise into decision rules. Our clients use these outputs to: (a) quantify the value of early licensing agreements, (b) decide between capacity investment and long‑term offtake, and (c) price sustainability premiums into bids. For teams that need workshop support, PW Consulting offers scenario rehearsals and bespoke modeling to integrate the Nylon‑MXD6 forecast directly into your 2026 budgeting and strategic planning cadence.
PW Consulting’s Nylon‑MXD6 Market study is the operational intelligence pack for 2026: it provides the market context, risk controls, and competitive insight you need — without exposing the proprietary segment detail here. Access the full report for the datasets, models, and playbooks that will make your 2026 decisions defensible and actionable.
For detailed analysis of this topic, please visit the official page: Nylon-MXD6 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com