

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Wedding Ring Market to Reach USD 158.38B by 2032 at 6.5% CAGR

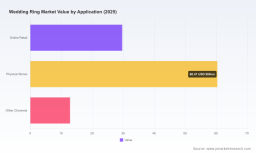
Wedding Ring Market — 2026 Strategic Preview
Executive snapshot
PW Consulting's latest Wedding Ring Market study (base year 2025) equips executives with the commercial intelligence required to make high-conviction decisions in 2026. The market has expanded steadily through the 2020–2025 period, rising from a mid‑teens USD billion base in 2020 to a USD 103.0 Billion market in 2025. Our forecast (2026–2032) projects continuation of this trajectory under a central case CAGR of 6.5%, reaching roughly USD 158.4 Billion by 2032. The market displays meaningful concentration at the top; the three largest groups account for a clear majority of industry revenue and the top five approach three‑quarters of the market — a structural fact that shapes competitive tactics and M&A returns.
Wedding Ring Market
Why this matters for 2026 corporate planning
-
Growth remains attractive but binary: steady headline expansion masks bifurcation between premiumization and volume-led segments. Brands that can combine premium storytelling (heritage, cut performance, provenance) with scalable distribution will capture outsized value.
Wedding Ring Market -
Input-cost volatility has moved from background risk to strategic determinant. Raw material dynamics — including record price movements in precious metals and the ongoing cost pressure on diamonds — will materially affect gross margins, inventory policies, and pricing cadence in 2026.
Wedding Ring Market -
Ethical sourcing and transparent provenance have migrated from CSR checkbox to purchase driver, particularly among high-value cohorts. Brands without credible traceability will find margin compression as consumers increasingly pay premiums for responsibly sourced goods.
-
Channel economics are evolving: digital first‑touch conversion improvements reduce acquisition costs, but physical retail remains essential for high-ticket closure and post‑sale services. The optimal 2026 model is omnichannel, calibrated by cohort-specific conversion economics.
-
Market concentration creates fertile ground for M&A and strategic alliances. Acquirers who can integrate manufacturing scale, distribution reach and brand exclusivity stand to accelerate roll‑up synergies in 2026 and beyond.
Key dynamics shaping strategy in 2026
-
Material price pressure and hedging: 2025 volatility has pushed procurement to the top of the agenda. Leading firms are combining longer-term supplier contracts, financial hedges and a calibrated mix of recycled/reclaimed metals to stabilize input costs and preserve margin elasticity.
-
Provenance and ESG integration: Ethical sourcing initiatives are no longer optional. Certification, blockchain-enabled provenance, and direct-sourcing partnerships with responsible mines and refiners are now strategic investments to protect brand equity and command price premiums.
-
Product modularity and personalization: Consumer preferences are skewing towards customizable and stackable designs. Operationally, this trend favors modular manufacturing and configurable SKUs that allow personalization at scale without proportional increases in lead time or cost.
-
Digitally-enabled product experience: Investment in high-fidelity visualization tools (light‑return simulators, AR try-ons, cut‑performance dashboards) materially increases conversion, especially for digitally native cohorts who prioritize objective quality signals.
-
Channel orchestration: Optimizing the interplay between online discovery, virtual consultations and in-store fulfillment will determine customer acquisition economics and lifetime value in 2026. Firms should measure and iterate the omni funnel with closed-loop attribution.
What the PW Consulting report delivers (practical, on-the-ground content)
This report is designed as an operational toolkit for 2026 planning cycles. Highlights include:
-
Scenario-led financial models: three demand scenarios (base, upside, downside) across 2026–2032 with sensitivity to material prices, channel mix and average selling price (ASP) movement.
-
Price elasticity and packaging frameworks: empirically validated elasticities by product tier and recommended promotional strategies that protect brand equity while improving conversion.
-
Supply‑chain risk matrix and sourcing playbook: supplier segmentation, traceability checklists, inventory policy recommendations and hedging protocols tailored to wedding rings.
-
Omnichannel commercial playbooks: cost-to-serve models, store-vs-digital margin trade-offs, localized assortment tactics and pilot blueprints for click‑to‑collect and virtual‑reservation services.
-
Product and assortment roadmaps: modular SKU architecture templates, launch calendars for stackable and customizable collections, and unit-economics tests for DTC versus wholesale placements.
-
M&A and partnership scorecards: acquisition screening filters, integration checklists and expected synergies for manufacturing, distribution and IP-focused targets.
-
Customer segmentation and LTV models: cohort definitions, acquisition benchmarks, retention levers and lifetime value uplift scenarios for personalization and aftercare services.
-
KPIs and implementation dashboards: executive dashboards and organizational change templates to operationalize strategy into QBRs and 12‑18 month roadmaps.
Competitive landscape — strategic takeaways from incumbent behavior
The report examines marquee incumbents and their strategic postures. Below is a concise reading of how leading firms in the wedding ring space are positioning — and what that implies for competitors and potential investors.
-
Artcarved (New York) — Heritage craftsmanship and comfort-centric design are Artcarved’s differentiators. Strategic implication: heritage brands can monetize provenance and differentiated fit, but must modernize supply-chain transparency and digital merchandising to connect with younger buyers. Recommendation: pair limited-edition heritage runs with robust DTC storytelling and aftercare subscriptions.
-
Brilliant Earth (San Francisco) — Market leader on ethical sourcing and traceability. Strategic implication: sustainability creates a defensible premium; rivals must decide whether to match via certification or compete on price/scale. Recommendation: companies seeking share in premium segments should fast-track traceability pilots and certification partnerships, or risk margin erosion.
-
Tacori (California) — Known for customizable, American-made designs. Strategic implication: customization drives differentiation but elevates operational complexity. Recommendation: adopt a modular manufacturing approach to reduce lead-times while preserving bespoke value, and explore in-store configurators that convert higher-AOV customers.
-
Whiteflash (New York) — Focus on cut performance and measurable light return. Strategic implication: technical differentiation appeals to quality‑sensitive buyers; translating technical advantage into accessible messaging is the gap. Recommendation: invest in visualization tools and third‑party validations to convert technical superiority into purchase intent.
-
Shane Co. (Minneapolis) — Family-owned omnichannel operator with broad inventory. Strategic implication: physical scale drives convenience and trust for high-ticket purchases, but inventory financing and working-capital are critical levers. Recommendation: optimize SKU rationalization and inventory turns; explore subscription-style maintenance and upgrade programs to increase LTV.
-
JewelPin (USA) — Global manufacturer/wholesaler of ready-to-ship rings. Strategic implication: supply-side scale positions this player as an attractive partner for private-label programs and fast-fulfillment needs. Recommendation: brands should evaluate strategic supplier relationships to capture cost advantages, while protecting brand exclusivity through design IP and selective distribution.
Recommended 2026 playbook — five tactical moves
-
Institute a two‑track pricing strategy: protect premium SKUs with provenance narratives while deploying value-led assortments optimized for rapid inventory turns.
-
Implement a raw-materials risk dashboard: combine contractual coverage, recycled metals and selective hedging to smooth cost pass-through to consumers.
-
Scale modular customization: reduce bespoke costs with pre‑configured modules, improving margins and reducing lead times.
-
Operationalize provenance: move from marketing claims to auditable supply chains (certificates, trace logs, digital provenance) to protect pricing power.
-
Pursue targeted consolidation: use the current concentration dynamics to acquire complementary manufacturing or distribution assets that accelerate profitable growth.
What we intentionally withhold in this preview
To preserve actionable value for decision-makers, this preview omits the granular regional, material and channel breakdowns (detailed tables with regional splits, per‑material revenue bands and channel economics are available in the full report). The report also includes downloadable financial models, country-level forecasts and executable pilot templates that are not reproduced here.
Next steps
For market-entry analysis, capex planning, or M&A screening in 2026, PW Consulting’s full Wedding Ring Market report provides the granular intelligence and tools required to move from insight to execution. Access the complete dataset, scenario models and playbooks on PW Consulting’s report page or contact our industry leads for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Wedding Ring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com