

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hot-Work Die Steels Market to Reach USD 344.8M by 2032 (6.98% CAGR)

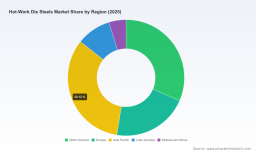
Hot-Work Die Steels Market — Strategic Preview for 2026 Decision-Making
Executive snapshot
The Hot-Work Die Steels market has moved from a niche durability play into a strategically material segment of advanced tooling supply chains. Measured on a global basis, the market reached USD 215.0 Million in our base year (2025) after recovering from pandemic-era volatility and is projected to expand at a compound annual growth rate (CAGR) of 6.98% across the 2026–2032 forecast window. By 2032 the market is expected to exceed USD 340 Million, driven by demand for higher-duty dies, tighter tolerances in forged and cast components, and rising adoption of alloy and process improvements that extend die life under severe thermal cycling.
Hot-Work Die Steels Market
Why this research matters for 2026 corporate strategy
For manufacturing leaders, die makers and materials buyers, 2026 is shaping up as an inflection year. Policy shifts (including new carbon border adjustments and emissions limits), consolidation among European suppliers, and continued product engineering advances are simultaneously compressing supplier choice and raising the stakes of sourcing and innovation decisions. This research presents the market-level view required to align sourcing, R&D investment, and M&A priorities with near-term constraints and mid-term opportunity.
Hot-Work Die Steels Market
-
Timing: With new tariffs and carbon-related measures taking effect around 2026 in key markets, procurement and localization strategies must be set now to avoid margin erosion.
Hot-Work Die Steels Market -
Technology pivot: Thermal-management improvements and cleaner metallurgy are changing the value equation for die steels — you either play the long-life, premium-die game or compete on lower-cost, higher-replacement models.
-
Consolidation window: Recent and announced integrations (notably the GMH Gruppe integration in early 2026) open both supply-side scale and consolidation arbitrage for strategic buyers and partners.
What the report delivers — practical, executable content
This market study is structured to support immediate 2026 decision cycles. It blends quantitative market sizing and scenario forecasting with operational playbooks that translate insight into actions. Key deliverables include:
-
Robust market sizing and top-line forecasts for 2026–2032 based on sector drivers and sensitivity to raw-material and regulatory scenarios.
-
Supply-chain diagnostics: identification of pinch-points for high-purity alloy inputs (chrome, molybdenum, vanadium), logistics risk maps and alternative sourcing ladders designed for rapid deployment.
-
Regulatory impact modelling that translates EU emissions rules and carbon border adjustments into cost-per-ton and sourcing penalty vectors for different supply origin scenarios.
-
Commercial playbooks: supplier selection scorecards, long-term off-take vs spot procurement decision matrices, and procurement contracting templates oriented to die-life total cost of ownership (TCO).
-
R&D and product strategy guidance: priority areas for alloy chemistry and heat-treatment investments, and a roadmap to deploy thermal-conductive and high-toughness grades for specific die-making use cases.
-
M&A and partnership scenarios: where scale matters (production capacity, ESR/VIM facilities, vacuum hardening expertise) and how to structure deals to unlock synergies quickly.
Market dynamics and near-term catalysts
Several interacting forces will define competitive advantage in 2026 and beyond:
-
Material science advances. Suppliers are launching grades with improved thermal conductivity and high-temperature strength — an example being a new hot-work grade aimed at extending mold service life and reducing operating cost per part.
-
Regulatory pressure. European limits on emissions from electric arc furnaces and the roll-out of carbon border adjustment mechanisms require buyers to quantify embedded carbon and evaluate near-shore or compliant suppliers.
-
Standards-driven quality expectations. ISO specifications governing impact toughness for hot-work die steels impose minimum properties that affect both vendor qualification and warranty exposure.
-
Raw material tightness. Premium hot-work grades require high-purity chrome-molybdenum-vanadium inputs; supply constraints or price shocks in these alloys disproportionately affect specialty steel pricing and availability.
Operationally, the sector is also experiencing a labor- and skills-driven shift: specialized heat-treatment proficiencies, particularly vacuum hardening and ESR processing know-how, have risen in importance (with notable increases in required skilled labor since 2024), altering where and how value is captured in the supply chain.
Competitive landscape — who moves the market
The market remains fragmented: the leading companies together account for roughly a quarter of total market revenue, leaving a long tail of regional and specialty producers. This fragmentation breeds both competition and acquisition opportunity.
-
Japanese leadership in alloy R&D and cleanliness: companies such as Daido Steel, Sanyo Special Steel, Nippon Koshuha, Proterial and several specialty mills continue to push metallurgical boundaries with grades optimized for die casting, forging and extrusion. Their strengths include vacuum metallurgy, high-purity product lines and strong OEM relationships in automotive and industrial equipment.
-
European premium capability and consolidation: suppliers such as voestalpine High Performance Metals, Swiss Steel Group and Aubert & Duval combine advanced processing (ESR, VIM) with engineering services. Swiss Steel’s recent grade launch (late 2025) and the GMH Gruppe integration (completed in January 2026) are examples of how European players are seeking product-led and scale-led differentiation.
-
Regional producers and capacity plays: Asian producers across China and India (including several large-scale steelmakers and specialty mills) provide competitive supply for commodity-lean applications, giving buyers options where carbon and regulatory exposure are manageable or where cost pressure is paramount.
-
North American specialists: boutique tool-steel producers and service-focused companies (e.g., Hudson Tool Steel and Southern Tool Steel) maintain close relationships with die shops and OEMs, offering localized response and aftermarket services that reduce downtime.
For buyers and strategic planners, the implications are clear: metallurgical superiority and low-carbon production credentials command premiums; meanwhile, geographic footprint and service models determine price-to-value in procurement negotiations.
Strategic implications and recommended levers for 2026
Based on our synthesis, executives should execute a coordinated set of actions across four dimensions in 2026:
-
Secure supply and diversify alloy sourcing: establish dual-sourcing for high-purity alloy inputs, and structure long-term contracts that include embedded carbon clauses to address CBAM exposure.
-
Prioritize product and process differentiation: invest in thermal-management and surface engineering to extend die life, and partner with suppliers who offer ESR/VIM capacity and demonstrable low-CO2 footprints.
-
Operationalize locale and compliance: where tariffs or carbon mechanisms bite, consider near-shore production or co-investment in compliant mills to preserve margin and lead times.
-
Use M&A and partnerships tactically: pursue bolt-on acquisitions or JV partnerships to acquire vacuum hardening, ESR capacity or specialty alloy lines rather than broad horizontal deals — the market rewards depth over scale for technical capabilities.
How to use this report in your 2026 planning cycle
We designed the research to be immediately actionable for board-level strategy sessions and operational procurement teams alike. Practical use-cases include:
-
Baseline scenario planning: overlay the report’s market forecast and regulatory impact analysis onto your volume and margin forecasts to derive adjusted capital and working-capital plans.
-
Supplier scorecarding: adopt the report’s supplier evaluation templates to re-run vendor assessments with carbon, metallurgy and service response incorporated.
-
Deal readiness: use the M&A playbooks and synergy schematics to evaluate target mills and to fast-track integration planning where acquisitions are pursued.
-
R&D and CapEx prioritization: align alloy development projects and heat-treatment investments with the report’s timing for premium grade adoption to maximize payback.
Conclusion — the strategic choice for 2026
The hot-work die steels market is neither a low-risk commodity arena nor a purely bespoke boutique sector: it sits at the intersection of high-precision metallurgy, regulatory exposure and operational intensity. For 2026, companies that move early to secure compliant alloy supply, partner on high-performance grades, and rationalize service-oriented offerings will capture outsized value as the market grows at a near 7% CAGR toward 2032.
This preview intentionally highlights trends, competitive dynamics and decision levers while preserving the granular subsegment and regional breakdowns that are core to procurement and investment actions. For the full data tables, segment-level forecasts and supplier scorecards that operational teams require for contract and capital decisions, access the complete report on our site and download the supporting appendices.
For detailed analysis of this topic, please visit the official page: Hot-Work Die Steels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com