

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Detonator Market to Hit USD 12,029M by 2032 at 3.42% CAGR

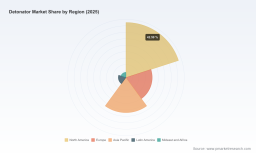
Detonator Market — 2026 Strategic Outlook (PW Consulting)
As companies make capital allocation and portfolio decisions for 2026, clarity about where the detonator market is headed is non‑negotiable. PW Consulting’s Detonator Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes validated market sizing, technology trajectories, and supplier economics into a decision-grade roadmap. The global market has expanded from roughly USD 7.9 billion in 2020 to about USD 9.6 billion in 2025 and — at a compounded annual growth rate of 3.42% across our forecast horizon — is projected to approach the low‑teens billion USD range by 2032. Market structure is moderately concentrated: the top three players collectively hold roughly 30% of value, and the top five about 40% — a dynamic that shapes competitive strategy and partnership calculus.
Detonator Market
Why this study matters for 2026 decisions
-
Timing: 2026 is the inflexion point for product and manufacturing investments. Several leading suppliers completed capacity and automation investments in 2024–2025; entrants and incumbents must decide whether to follow, differentiate, or consolidate.
Detonator Market -
Capital deployment: Firms that wait for perfect certainty will pay a premium in lost share or higher unit costs when demand re‑accelerates. Our analysis turns uncertain signals into explicit investment thresholds and staging plans.
Detonator Market -
Regulatory and customer pull: Lead‑free and precision electronic initiation systems are moving from niche to mainstream in regulated markets. Certification and standards compliance have become tactical gating items for market access.
-
Supply resilience: Recent on‑shoring and regional plant builds underscore supply chain fragility — the right manufacturing footprint choices will materially affect lead times and risk exposure.
What the report delivers — practical, executable content
-
Decision‑grade market sizing and trend diagnostics covering 2020–2032, with baseline, upside, and downside scenarios that embed commodity, regulation, and construction/mining cycle sensitivities.
-
Go‑to‑market playbooks for incumbents and new entrants: channel strategies, service bundling, pricing frameworks, and tender playbooks tailored to mining, industrial, and defense end users.
-
Technology and product roadmaps: actionable recommendations for electronic initiation, lead‑free chemistries, and high‑reliability detonators for aerospace/defense segments, including qualification roadmaps and cost‑to‑serve models.
-
Supply chain and manufacturing diagnostics: factory automation ROI models, localization scenarios, renewable energy integration options, and a supplier risk heatmap to prioritize mitigation actions.
-
Competitive benchmarking and M&A playbook: profiles of strategic peers, capability gaps, acquisition screening criteria, and an integration checklist that preserves regulatory compliance and HSE performance.
-
Procurement and cost engineering templates: unit economics for detonator types, labour and materials sensitivity analyses, and contract structures to balance margin and volume risk.
-
Regulatory impact assessment and ESG roadmap: scenario planning for increasingly stringent environmental standards and defense/aerospace qualification requirements.
High‑level macro takeaways (what senior leaders must internalize)
-
Measured but persistent growth. The market’s expansion from about USD 7.9 billion in 2020 to USD 9.6 billion in 2025, and our projection into the 2032 timeframe, reflects steady demand linked to mining activity, construction cycles, and defense qualification windows. The 3.42% CAGR masks uneven pockets of faster adoption where precision initiation systems and lead‑free solutions have found higher willingness‑to‑pay.
-
Technological bifurcation. Electronic and programmable initiation systems are differentiating on safety, timing precision, and data integration (blast analytics). Parallel advances in lead‑free initiation chemistries are creating regulatory and commercial pull — early movers capture premium pricing in regulated jurisdictions.
-
Manufacturing modernization is a competitive lever. Case examples from recent years show firms investing in fully automated plants and renewable energy at detonator facilities to reduce operating expense and decouple from energy‑price volatility. These investments shorten lead times and lower total cost of ownership for large buyers.
-
Supply chain topology matters. Regional plant openings and on‑shore capacity demonstrate an industry move toward mitigating logistics, compliance, and geopolitical risk. Buyers are increasingly demanding local content and faster replenishment cycles, altering procurement dynamics.
-
Concentration creates transactional and partnership opportunities. With the top three to five firms holding a meaningful but not overwhelming share of value, there is room for targeted consolidation, bolt‑on acquisitions, and strategic alliances — especially where specialized electronic or defense‑qualified capabilities are scarce.
Competitive landscape — strategic reads on leading players
-
Dyno Nobel: Continuing investments in factory automation and energy resilience mark Dyno Nobel as an operator focused on scale efficiency and sustainability. Their portfolio emphasis on electronic initiation systems and automated plants positions them to serve large, safety‑conscious mining clients.
-
Orica Limited: Orica’s push on lead‑free electronic systems and formal certifications reflects a product differentiation strategy aligned with regulatory markets. Their certification milestones reduce adoption friction in Europe and other regulated geographies.
-
Austin Powder Company: With offerings spanning electronic, electric, and non‑electric systems, Austin Powder combines product breadth with industrial blasting services — a useful model for mixed‑portfolio operators seeking relational contracts with mines and civil contractors.
-
MAXAM and Enaex: Both firms illustrate regional strength coupled with focused electronic solutions. Enaex’s programmable detonators and MAXAM’s electronic lines show the increasing value of precision timing in blast optimization services.
-
Specialty suppliers (Chemring, Excelitas, Teledyne): These players secure high‑value, technically demanding pockets — defense, aerospace, and specialized industrial clients — where qualification standards and traceability requirements create higher barriers to entry.
-
Regional manufacturers and new capacity (BME Mining Canada, Kırlıoğlu, Nelson Brothers, Ideal Mining Services): Recent plant openings and local production capabilities highlight an industry pivot to mitigate supply chain risks and meet regional content expectations.
Recent industry moves to watch (2024–2026)
-
Automation and energy initiatives: Several major manufacturers completed or expanded automated electronic detonator plants and renewable energy installations at detonator/booster sites, reducing operating cost volatility and improving sustainability credentials.
-
Regional capacity builds: New plant openings in established mining jurisdictions reflect a strategic push to de‑risk logistics and shorten lead times for critical initiation products.
-
Product certification and lead‑free adoption: Market leaders secured certifications that enable the commercial rollout of fully lead‑free electronic detonators across regulated markets, unlocking procurement pipelines in Europe and beyond.
Strategic imperatives for 2026
-
Prioritise capability bets: Decide whether to invest in in‑house electronic initiation, buy capabilities through M&A, or secure long‑term supply agreements. The right choice depends on scale, end‑market mix, and regulatory exposure.
-
Localize selectively: Use a triage of lead time, regulatory risk, and customer demand to determine where regional manufacturing is justified versus where centralized, low‑cost production remains optimal.
-
Accelerate qualification programs: For players targeting defense, aerospace, or highly regulated mining markets, front‑loading qualification (and certification) shortens commercial ramp timelines and creates durable differentiation.
-
Embed digital value: Electronic detonators that provide timing data and blast analytics can be monetized through service contracts and analytics subscriptions — turn a component sale into a recurring revenue stream.
-
Mitigate raw‑material and labour risks: Scenario plans should quantify exposure to specialized labour shortages and shifts in explosive feedstock; hedges and dual‑sourcing arrangements are no longer optional.
-
Use M&A to fill capability gaps: In a market with moderate concentration, bolt‑ons can provide rapid access to electronic know‑how, regional footprint, or defense qualifications without the time and compliance burden of greenfield builds.
How PW Consulting supports your 2026 agenda
-
Bespoke strategy workshops that convert the global forecast and supplier benchmarking into an executable 12–36 month roadmap.
-
Investment‑grade financial models and scenario simulators, calibrated to your cost base and optionality points (manufacturing, qualifications, product R&D).
-
M&A origination and diligence support: targeted screening, regulatory pathway mapping, and integration playbooks that preserve HSE and certification continuity.
-
Procurement transformation: supplier scorecards, contract playbooks, and negotiation templates designed to secure resilient supply at predictable unit economics.
For senior leaders preparing 2026 capital and commercial plans, the choice is clear: act on high‑confidence signals now or accept the strategic drag of catching up later. PW Consulting’s Detonator Market report provides the data, scenarios, and playbooks to make those decisions with conviction. The executive summary above highlights core insights and practical implications; the full report contains the detailed segment tables, regional demand matrices, and supplier scorecards that underpin these recommendations. Access the complete intelligence package to move from strategic intent to execution-ready plans.
For detailed analysis of this topic, please visit the official page: Detonator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com