

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: EMI Absorber Sheets & Tiles Market to Reach USD 1,102M by 2032 (5.1% CAGR)

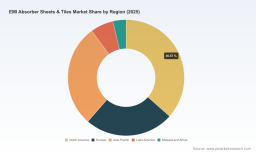
EMI Absorber Sheets & Tiles Market — Strategic Perspectives for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a succinct, decision-focused introduction to our new market study on EMI absorber sheets and tiles. This market is transitioning from niche materials play to a strategic systems component, and the choices organizations make in 2026 will determine competitive position through the next investment cycle. Our view is grounded in a consolidated market model (base year 2025, historical window 2020–2025, forecast horizon 2026–2032) that projects a compound annual growth rate (CAGR) of 5.1% across 2026–2032. The industry recovered from mid-decade volatility, with global reported market value around USD 778 million in 2025 and a projected trajectory toward roughly USD 1.10 billion by 2032.
EMI Absorber Sheets & Tiles Market
Why this study matters to C-suite and BU leaders in 2026
- Validate product and market bets: the study translates macro demand drivers (telecom densification, automotive electrification, miniaturization in consumer electronics, medical device reliability) into implications for absorber material choices and form factors.
- Prioritize capital allocation: our scenario-based forecasts identify when to scale capacity, automate converting/die-cutting, or defer CAPEX to avoid overcapacity.
- Derisk sourcing and pricing: we quantify the sensitivity of margins to raw-material swings (ferrites, conductive polymers) and labor inputs in adhesive converting.
- Shape M&A and partnership agendas: concentration metrics and capability maps reveal what capabilities are most accretive (broadband formulations, thin elastomer converters, ferrite tile manufacturing).
- Fast-track regulatory readiness: EMC compliance up to 10 GHz, RoHS, and UL94V-0 flame-retardancy requirements are central to product acceptance in core verticals.
What you will practically get from the full report
- Executive dashboard: concise market sizing, validated growth curves, and scenario outputs to support board-level decisions.
- Demand-by-dimension model: a dynamic engine combining end-market adoption curves, device BOM penetration rates, and replace/retrofit cycles (regional and application decompositions available in the full report).
- Competitive playbooks: capability matrices, go-to-market positioning, product portfolios and channel strategies for leading and emerging suppliers.
- Supply-chain risk map: tiered supplier intelligence for ferrites, conductive polymers, adhesives and converting partners, with contingent sourcing blueprints.
- Pricing and margin sensitivity tool: run “what-if” scenarios on raw-material spikes, freight dislocations, and labor rate shifts to quantify P&L exposure.
- Regulatory and testing checklist: mandatory EMC/EMI test bands, certification pathways, and time-to-market implications for different verticals.
- Actionable recommendations and a 12–36 month implementation playbook tailored to three archetypes: OEMs, component manufacturers, and specialty converters.
Macro trends and constraints shaping 2026 decisions
Three structural themes will dominate strategy in 2026:
EMI Absorber Sheets & Tiles Market
- Standards-driven complexity: EMC requirements increasingly require absorption solutions to perform across broader frequency ranges—designs must be validated to tens of GHz in product test plans. This drives demand for broadband absorber formulations and hybrid solutions that combine ferrites and conductive polymers.
- End-market consolidation and technological substitution: automotive electrification and advanced driver-assistance systems (ADAS) introduce more stringent EMI requirements, increasing per-vehicle absorber content. Simultaneously, telecom densification (including 5G and emerging mmWave deployments) reallocates absorber demand between form factors—sheet, tile, and dispensable materials.
- Cost-to-serve pressure from material and processing inputs: ferrites and conductive polymers represent the majority of raw-material cost in sheet/tile manufacturing, while converting operations (adhesive lamination, die-cutting) introduce labor and precision-costs that materially affect unit economics. Strategic choices—automation of converting, supplier consolidation, or vertical integration—will determine margin trajectories.
Overlaying these themes are regulatory constraints: EMC compliance up to 10 GHz is increasingly expected, and materials must meet RoHS and UL94V-0 flame-retardancy standards for many applications. These requirements affect sourcing, lead times, and qualification cycles.
EMI Absorber Sheets & Tiles Market
Competitive landscape — who matters and how
The market exhibits a moderate concentration profile: the top three global players account for roughly two-thirds of reported industry revenue, and the top five approach three-quarters of the market. This structure creates both barrier and opportunity: established incumbents control scale advantages and deep customer relationships, while focused specialists and regional producers can win on technical differentiation or cost agility.
- 3M Company (St. Paul, Minnesota) — A technology stalwart with a broad portfolio (including multi-frequency absorbers) and deep relationships across electronics and automotive OEMs. Their advantage is integrated material science, strong formulation IP, and global go-to-market coverage. Strategic implication: competing with 3M requires either a technical niche (ultra-thin form factors, tailored adhesive stacks) or superior cost-to-serve in targeted verticals.
- Laird Performance Materials (United States) — Focused on thin elastomer absorbers, ferrite sheets and dispensable absorbers for near-field and cavity-resonance suppression. Laird’s playbook emphasizes application-specific engineering and close OEM collaboration. Strategic implication: partnerships or licensing of niche formulations can accelerate time-to-market for OEMs seeking quick qualification cycles.
- Fair-Rite Products Corp. (Wallkill, NY) — A ferrite-component specialist delivering absorber and shielding components integrated into sheets and tiles. Their capabilities matter where ferrite performance dominates, particularly in constrained geometries and cavity solutions. Strategic implication: securing ferrite supply or co-development agreements is a defensive move for manufacturers reliant on ferrite performance.
- KITAGAWA INDUSTRIES (Japan) — A regional supplier with a deep product catalogue tailored for EMC use cases. Kitagawa’s strengths are engineering support and localized supply chains in Asia. Strategic implication: for players targeting Asia Pacific, regional alliances or distribution agreements are pragmatic short-cuts.
- Henkel AG & Co. KGaA (Düsseldorf) — Known for adhesives and shielding films, Henkel has leaned into automotive electronics with recent product introductions designed to combine shielding and adhesion in cost-effective formats. Strategic implication: adhesives and films are adjacent levers—OEMs should evaluate integrated film+adhesive offers to simplify assembly and certification burdens.
Recent vendor activity underscores the pace of product development and catalogue refresh: Henkel launched a targeted shielding film at Productronica 2025; KITAGAWA updated its absorber product range in April 2025; Fair-Rite refreshed its ferrite components catalogue in late 2025. These moves signal that incumbents are optimizing portfolios for automotive and smart-home applications while trying to capture retrofit and retrofit-replacement windows.
Strategic playbook for 2026 (practical recommendations)
- Segment with intent: prioritize a limited set of end-markets (e.g., high-value automotive modules, telecom infrastructure, or medical devices) where technical differentiation or regulatory moats allow premium pricing. Use the report’s demand engine to stress-test your selection under three scenarios.
- Lock critical raw-material access: establish multi-sourced agreements for ferrites and conductive polymers, include price collars or indexation clauses, and explore toll-processing partnerships to reduce inventory buffers.
- Optimize converting economics: audit converting steps (adhesive lamination, die-cutting) and quantify ROI on automation. For many players, a hybrid approach—capex-light regional converting hubs paired with centralized bulk compounding—offers best trade-off between lead time and cost.
- Invest selectively in integration: vertical moves into ferrite compounding or adhesive laminating can be accretive if you capture >X% of internal demand (see detailed thresholds in the report). Otherwise, pursue strategic alliances and tight co-development agreements.
- Design for certification early: embed EMC test requirements (up to 10 GHz), RoHS, and UL94 planning into product roadmaps to avoid late-stage redesign costs and delayed time-to-market.
- Prepare M&A playbooks: target niche specialists in broadband formulations or high-precision die-cutting; run rapid technical diligence against supplier scorecards we provide.
- Differentiate on service: offer design-assist, prototype-to-qualification services, and inventory-managed programs to OEMs—these can convert technical value into sustainable margin expansion.
Supply-chain levers and cost management
Two cost buckets deserve programmatic attention in 2026: raw materials and converting labor. Ferrites and conductive polymers account for the majority of material cost; adhesive converting and die-cutting are the principal labor and precision-cost drivers. Practical levers include formula reformulation to reduce expensive fillers, moving low-variance converting to automated cells, implementing vendor-managed inventory for adhesives, and negotiating freight and lead-time guarantees with upstream suppliers.
How PW Consulting’s analysis de-risks your pathway
- Transparent scenario modelling: three adoption trajectories and sensitivity matrices tied to raw material moves and regulatory timelines.
- Supplier scorecards and capability heatmaps: technical capacity, qualification timelines, geographic footprint, and price bands—designed for rapid procurement decisions.
- Case studies and playbooks: real-world rollouts in automotive and telecom contexts that translate to certification time, costs, and expected absorption rates per device class.
- Negotiation-ready templates: commercial terms, sample SOWs for co-development, and recommended risk-sharing clauses for supply agreements.
Closing — what this preview leaves deliberately unsaid
This article intentionally focuses on strategic implications, the competitive topology, and operational levers for 2026. To preserve the “trailer” purpose—illustrating depth while reserving the core forensic inputs—we have omitted the granular regional and application-level revenue breakdowns, detailed segment-by-segment CAGR overlays, and specific pricing curves. These elements are central to tactical execution (e.g., targeted capacity investments, SKU rationalization, and regional sales plays) and are contained in the full PW Consulting report and the downloadable analytical models.
If you are preparing capital plans, supplier strategies, or product roadmaps for 2026 and beyond, the full report will provide the numeric precision (regional and application allocations, unit economics, and supplier-level financial proxies) needed to convert the strategic directions above into executable programs.
Contact PW Consulting to access the full EMI Absorber Sheets & Tiles Market study, the interactive model, and a tailored briefing that maps our insights to your organization’s decision calendar for 2026.
For detailed analysis of this topic, please visit the official page: EMI Absorber Sheets & Tiles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com