

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Video Intercom Market to Reach USD 36.67M by 2026 at 12.45% CAGR

Video Intercom Devices and Equipment Market: Strategic Imperatives for 2026 Decision-Makers
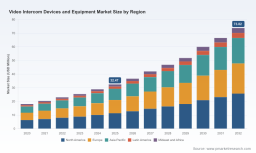
As organizations finalize budgets and roadmaps for 2026, the video intercom market is at an inflection point. Our PW Consulting market study—anchored on a 2025 base year, tracking 2020–2025 historicals and forecasting through 2032—shows the sector expanding from a market size of USD 32.47 Million in 2025 to an estimated USD 73.82 Million by 2032, implying a compound annual growth rate of 12.45%. That trajectory reflects not only steady demand for basic ingress/egress solutions but a rapid compositing of cloud services, AI-enabled features, and systems integration that reframe intercom devices as nodes in broader security, building-management and tenant-experience platforms.
Video Intercom Devices and Equipment Market
Why this study matters for 2026 strategy
-
Timing: 2026 is the year many enterprises and public-sector procurement teams will operationalize multi-year digital infrastructure programs initiated during the pandemic recovery and smart-building pushes. Decisions made this year determine 3–5 year platform lock-in and long-tail operational costs.
Video Intercom Devices and Equipment Market -
Scale and pace: With a mid-teens CAGR, the market is large enough to attract both incumbents and new entrants but still fragmented enough to leave meaningful share and margin opportunities for bold players.
Video Intercom Devices and Equipment Market -
Regulatory pivot points: New and incoming regulations around procurement security, energy reporting and data-center obligations are already influencing vendor eligibility and platform design choices—making compliance a primary procurement filter in 2026.
-
Commercial impact: Video intercoms are transitioning from single-purpose devices into integrated security and tenant-engagement touchpoints; this reclassification changes procurement criteria from unit price to lifecycle total cost and data governance.
What the macro picture tells us (without revealing the confidential splits)
The headline growth and multi-year market sizing underscore a market that is expanding both in unit demand and in average revenue per device, as higher-value features—cloud subscriptions, AI analytics, and enterprise-grade integrations—become standard options. Market concentration is moderate: the top three vendors account for a meaningful share of industry revenues, and the top five expand that presence further. That configuration creates two strategic realities for 2026: first, scale and channel reach will continue to matter for large enterprise and government deals; second, differentiated feature sets and go-to-market models (e.g., fully mobile cloud vs. SIP-native and on-prem variants) can still deliver outsized growth for focused challengers.
Competitive landscape — what to watch in 2026
-
Incumbents with platform plays: Firms building integrated platform stacks—combining video, access control and cloud management—are shifting procurement conversations. These vendors emphasize operational simplicity and data consolidation, which appeals to enterprise customers seeking to reduce vendor sprawl.
-
Cloud-native disruptors: Mobile-first, no-wiring installation models are accelerating deployments in multifamily and retrofit commercial spaces. These providers lower installation friction and create recurring revenue via subscription models, but need to prove enterprise-grade reliability and integration breadth to win larger institutional customers.
-
Specialists focused on critical communications: Vendors delivering hardened, standards-based intercoms for industrial, broadcast and critical infrastructure retain a defensible niche—particularly where regulatory mandates and reliability requirements exclude consumer-grade alternatives.
-
Chinese OEM dynamics: Manufacturers with vertically integrated supply chains continue to compete on price and scale, but geopolitical and regulatory pressures in select procurement channels are materially reshaping their near-term addressable markets.
Across these archetypes you will find the companies profiled in our study. Each exhibits distinct strategic plays: cloud remote management and IP-series product lines from established hardware vendors; mobile-cloud propositions from emergent entrants; integrated AI and access-control convergence from enterprise-focused firms; and SIP-native offerings favored by systems integrators. These differences are not just marketing—they determine channel, pricing and integration strategies for 2026 contracts.
Regulatory and infrastructure headwinds (and opportunities)
-
Procurement security rules: Legislative measures that restrict certain vendors from government procurement in some jurisdictions force buyers and integrators to embed compliance criteria into RFPs. For vendors, achieving diversification and compliance attestations will be table stakes to access public-sector pipelines.
-
Energy and data-center constraints: New energy-reporting and power-usage obligations for infrastructure that supports cloud-based intercom services are increasing the effective cost of cloud operations in regulated regions. This creates demand for energy-efficient edge processing and hybrid cloud architectures that minimize data-center burdens.
-
Supply-side volatility: Component price swings—especially in displays, optics and polymer parts—are creating 15–20% cost fluctuation risks on bills of materials. Procurement teams must plan for buffer strategies such as dual-sourcing, longer-term contracts, and modular product designs to avoid margin erosion.
-
Local infrastructure policy: Regional electricity and transmission rules can materially change the TCO of cloud-first offerings where data-center obligations accrue to platform operators or their customers.
Recent vendor moves that foreshadow 2026 priorities
-
AI and usability innovations such as live translation, AI-powered voice directories and deterrence features are moving from pilot to productized releases—changing buyer expectations for what a modern intercom must do.
-
Modular integration modules and protocol adapters are being released to bridge touchscreen and third-party access-control ecosystems—reflecting demand for interoperability without wholesale rip-and-replace.
-
New mobile-directory and cloud-directory solutions for multi-tenant buildings show how software-as-a-service revenue and tenancy models are growing in importance alongside hardware sales.
Actionable recommendations for 2026 planning
-
Adopt a compliance-first vendor matrix: Build procurement scorecards that prioritize regulatory eligibility, energy reporting capability and supply-chain transparency over unit price alone. For public buyers, enforce vendor whitelisting and contract clauses tied to compliance milestones.
-
Model hybrid architectures: Require vendors to present hybrid cloud/edge deployment options and quantify delta-TCO over 3–7 year horizons under different energy and data-center cost scenarios. This will reveal true operating exposure and potential migration costs.
-
Stress-test supply chains: Mandate dual-sourcing for critical components or inventory hedging for greenfield deployments in 2026. Negotiate fixed-price or indexed contracts for volatile components when possible.
-
Insist on open integrations: For enterprise and multi-tenant deployments, require SIP and API compatibility, published SDKs and third-party integration references to reduce future lock-in and enable richer tenant services.
-
Prioritize lifecycle and service revenue: Shift procurement evaluation to include subscription economics, software roadmap alignment and service-level guarantees. Vendors with recurring-revenue models are more likely to invest in continuous feature upgrades relevant to tenant experience.
-
Look for partnership and M&A opportunities: Moderate concentration and differing vendor specializations mean strategic acquisitions or partnerships can deliver rapid capability expansion—particularly for players seeking AI or cloud competencies.
What the full PW Consulting report delivers
-
Comprehensive market-sizing (base year and forecast) and scenario modeling that captures energy, regulatory and supply-chain contingencies.
-
Vendor scorecards and positioning maps that evaluate product portfolios, go-to-market models, integration breadth and customer support maturity.
-
Action-oriented playbooks for procurement, systems integrators and product teams: migration roadmaps, contract clauses, integration checklists and three-year migration budgets.
-
TCO calculators and sensitivity analyses for cloud vs. edge strategies, including energy reporting impacts and component-cost shock tests.
-
Go-to-market strategies for challengers and incumbents: channel expansion tactics, partnership templates and M&A targets tailored to different regional and vertical priorities.
-
Primary research syntheses: interviews with integrators, end-users and vendor executives that ground our forecasts and vendor assessments.
Concluding strategic takeaways
2026 will be a decision-heavy year for both buyers and sellers in the video intercom market. The sector’s strong mid-teens CAGR and projected near-term doubling in market size make it an attractive arena for investment—but the path to sustained value depends on more than product specs. Compliance posture, energy-aware architectures, resilient supply chains and interoperable platforms will determine winners. Organizations that embed these criteria into procurement and product roadmaps in 2026 will avoid costly rework, capture recurring revenue opportunities and secure longer-term strategic advantage.
PW Consulting’s full research package contains the granular forecasts, vendor matrices and executable playbooks that procurement leaders, product strategists and M&A teams need to act with confidence. This executive preview intentionally omits confidential granular splits to preserve the analytical value of the full report. For the complete dataset, vendor scorecards and the customizable TCO models you will use to make 2026 decisions, refer to the full report.
For detailed analysis of this topic, please visit the official page: Video Intercom Devices and Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com