

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Metallocene Polyethylene Market to Reach USD 13,520M by 2032
By pmarketresearch, 2026-07-30
Metallocene Polyethylene Market — Strategic Imperatives for 2026
Executive summary
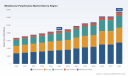
As metallocene polyethylene (mPE) transitions from a specialty polymer to a mainstream performance resin, 2026 represents a pivotal decision point for producers, converters, and investors. Our PW Consulting Metallocene Polyethylene Market study uses a 2025 base year and a 2026–2032 forecast horizon to quantify the opportunity and design actionable pathways. At a 6.8% compound annual growth rate (CAGR) through the forecast window, the market expands from approximately USD 6.74 billion in 2020 to an expected USD 13.52 billion by 2032, with the 2025 base market measured at USD 8.62 billion and the 2026 opening-year projection at roughly USD 8.95 billion (USD Million, historical series 2020–2025 included).
Metallocene Polyethylene Market
This report is intentionally structured as a strategic "preview": it surfaces the high-conviction trends, supplier strategic playbooks, and risk scenarios that will shape capital allocation and commercial tactics in 2026 — while withholding granular line-item segment tables in this public preview to ensure prospective clients consult the full intelligence package for the detailed breakouts that underpin investment models.
Metallocene Polyethylene Market
Why this matters for 2026 decision-makers
-
Demand profile and growth momentum: mPE’s differentiated performance—improved film optics, toughness at thinner gauges, and controlled molecular architecture—continues to expand use cases across packaging, construction, and mobility. The steady 6.8% CAGR signals both adoption depth and room for premiumization strategies in adjacent markets.
Metallocene Polyethylene Market -
Supply-side reconfiguration: Major incumbents are actively expanding capacity and layering product portfolios with metallocene-enabled grades. These investments will reshape regional competitive dynamics and cost curves through the mid-decade.
-
Feedstock and regulatory convergence: Large-scale ethylene additions globally are creating downward pressure on feedstock volatility and improving security of supply — a structural tailwind for mPE margins. Simultaneously, evolving sustainability and packaging regulations are accelerating demand for high-performance, lightweight solutions compatible with recycling streams.
Strategic actions we recommend
-
Prioritize product differentiation over low-cost commoditization. Invest in grade families that exploit metallocene’s unique molecular control (e.g., thinner, stronger films; tailor-made impact modifiers for pipes; breathable/laminating grades for hygiene and medical applications).
-
Optimize capacity timing and location. With new metallocene-capable units coming online, adopting a staged capacity-add approach reduces exposure to near-term price softness while preserving optionality to meet accelerating demand.
-
Securing feedstock visas. Locking competitive ethylene arrangements and integrating closer with steam cracker projects or merchant ethylene hubs will be decisive in 2026 investment returns.
-
Commercialize upstream R&D into converter enablement. Provide formulation support, co-development, and trial programs to accelerate converter migration to mPE and capture value beyond resin sales.
-
Embed sustainability as a margin lever. Align product messaging and technical documentation with recycling and packaging regulations to capture procurement wins in regulated markets.
What the full report delivers — operational and decision-grade content
-
Market sizing and forecasting with scenario runs (baseline, upside, downside) across 2026–2032, including sensitivity to ethylene feedstock price swings and capacity phasing assumptions.
-
Detailed segment economics and pricing models for grades, applications, and regions (note: granular split tables are available in the full subscription report).
-
Supply chain heatmaps with supplier-by-supplier capacity, asset vintage, and upgrade windows to support plant-level capex timing decisions.
-
Go-to-market playbooks for resin producers and converters — commercial KPIs, sample commercialization timelines, and margin capture strategies.
-
Risk matrices with mitigation options (feedstock, trade policy, technological substitution, circularity disruptions), and a quantified impact score to prioritize action.
-
M&A and partnering framework, including valuation anchors for bolt-on plants, tolling arrangements, and JV structures specific to metallocene-enabled assets.
Competitive landscape — what incumbents are doing
The mPE competitive set is concentrated, and three- to five-firm concentration metrics reflect a market with high structural barriers and scale advantages. Leading players are pursuing a mix of capacity investments, differentiated product portfolios, and regional footprint expansion to capture premium segments.
-
SABIC — Known for SUPEER™ mLLDPE and COHERE™/FORTIFY™ mPE grades, SABIC is positioning to serve flexible film packaging, agricultural films, and polymer modification markets. Its recent Southeast Asia facility expansion (announced September 2025) explicitly aims to increase regional metallocene output in alignment with evolving packaging regulations.
-
ExxonMobil — With Exceed™ metallocene resins in its portfolio, ExxonMobil has pursued both capacity and portfolio-led growth. Its Huizhou project (initiated operations mid-2025), which added a very-large LLDPE unit incorporating metallocene production, plus a late-2025 product launch targeting high-performance automotive applications, exemplify a dual-capability approach: scale plus specialized grades.
-
LyondellBasell — Leveraging Icorene™ metallocene hexene powders and mPE grades, LyondellBasell focuses on rotomolding, automotive, and industrial markets—segments where product performance can justify technical collaboration and premium pricing.
-
TotalEnergies — Lumicene™ grades position TotalEnergies in flexible film and breathable applications, aiming to capture demand driven by lightweighting and functional laminates.
-
Regional and specialist players — New product introductions out of Russia and Central Europe, and launches from state-owned or regional NOCs, continue to diversify supplier options for converters and end-users, intensifying the need for credentialed technical support and co-development.
Recent industry developments that re-shape 2026 strategy
-
Capacity and product moves: Major announcements in 2025–2026 (including large-scale LLDPE/mPE-capable units and new specialty grade rollouts) are compressing the window to secure converter trials and long-term offtake agreements.
-
Feedstock dynamics: Analysts report substantial global ethylene capacity additions through 2025. These additions, including significant build-out in China, are contributing to improved ethylene supply security and downward pressure on regional feedstock costs — a structural input that materially affects integrated and merchant margin profiles in 2026.
-
Regulatory alignment: Regional packaging and environmental standards (notably in Asia) are encouraging investments in single-site catalyst technologies and enabling cleaner production narratives. Facility expansions that explicitly cite regulatory alignment (e.g., reduced environmental impact for flexible films) are gaining preferential attention from downstream customers and regulators.
Risk vectors and scenario planning
-
Feedstock price volatility — Even with sizeable ethylene additions, downstream margins remain exposed to short-term cracker outages and energy price shifts. Hedging strategies and feedstock diversification remain primary mitigation levers.
-
Overcapacity in the near term — Capacity additions concentrated in specific regions risk local price compression. Staged capacity ramp-up and commercial differentiation can reduce exposure.
-
Circularity and regulatory disruption — Accelerated mandates for recyclability, PCR content, or single-stream separation could both favor and penalize mPE depending on grade recyclability and certification.
-
Technological substitution — Alternative polyolefin technologies or catalyst breakthroughs that further lower mPE cost structures could emerge; continual R&D monitoring is essential.
How to use this intelligence in 90/180/360-day cycles
-
90 days: Conduct a quick-scan commercial readiness audit — grade portfolio fit vs. priority customers, sample and trial readiness, and short-term hedging posture for ethylene exposure.
-
180 days: Finalize capacity timing decisions and offtake/tolling structures; initiate converter co-development partnerships and prioritize market-entry geographies based on logistical cost-to-serve.
-
360 days: Execute capacity investments or JV formations, finalize M&A targets using our valuation frameworks, and embed circularity credentials to capture regulated procurement streams.
Closing — why PW Consulting’s study matters to your 2026 plan
Our analysis blends rigorous quantitative forecasting (2020–2025 historical data, a 2025 base year, and 2026–2032 scenarios), supplier-by-supplier strategic mapping, and executable commercial playbooks. The report translates a 6.8% CAGR and multi-billion-dollar market trajectory into portfolio-level choices: which grades to push, where to site new capacity, and how to structure offtake and pricing agreements to preserve margin in the face of evolving feedstock and regulatory realities.
To uphold the “preview” principle and preserve the commercial value of the downstream granularity that underpins investment-grade decisions, we have withheld the detailed regional and application split tables from this public overview. For clients requiring the full dataset — including the segmented demand curves, price and margin models by grade and geography, and our tailored M&A playbook — please consult the full report available via PW Consulting’s Metallocene Polyethylene Market page.
PW Consulting stands ready to translate these insights into a bespoke implementation roadmap for your organization in 2026 — from tactical commercial pilots to capex and M&A execution. Contact our team to schedule a strategy session and access the confidential appendices and modeling workbooks.
For detailed analysis of this topic, please visit the official page: Metallocene Polyethylene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vitamin D Testing Market to Hit USD 1,985.5M by 2032 at 8.15% CAGR
By pmarketresearch, 2026-07-30
Vitamin D Testing Market: Strategic Imperatives for 2026 — PW Consulting Preview
Executive summary
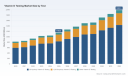
As healthcare stakeholders enter 2026, Vitamin D testing remains a high-velocity segment within clinical diagnostics. Our proprietary market model puts the global market at approximately USD 1.15 billion in 2025, and—assuming the central scenario—rising toward the USD 2.0 billion range by the end of our forecast window in 2032, driven by an 8.15% compound annual growth rate. These headline figures mask a rapidly evolving competitive, regulatory, and reimbursement landscape. This preview surfaces the strategic consequences for manufacturers, clinical laboratories, payers, and investors while intentionally withholding the granular regional and sub-segment worksheets included in the full PW Consulting report; those datasets are available through our secure report portal.
Vitamin D Testing Market
Market trajectory and growth dynamics
The Vitamin D testing market is moving from episodic demand—driven by seasonal screening and specific clinical indications—toward more integrated, protocolized testing across primary care and specialty pathways. The market’s mid-single-digit-to-high-single-digit trajectory over the 2026–2032 forecast period reflects three structural forces:
Vitamin D Testing Market
- Clinical expansion: growing clinician awareness of extra-skeletal roles of vitamin D and guideline updates that broaden testing triggers in certain patient cohorts.
- Technological substitution: a sustained shift toward higher-specificity assay platforms (including mass spectrometry and next-generation immunoassays), which changes unit economics and capital intensity for laboratories.
- Reimbursement and policy reconfiguration: a flurry of local coverage decisions and billing guidance that is tightening claim adjudication in some channels while opening opportunity windows in others.
For strategic planning, the core implication is that topline growth is available, but access to that growth will be uneven across channels and geographies depending on reimbursement alignment, laboratory capability, and go-to-market execution.
Vitamin D Testing Market
Regulatory, reimbursement and policy context
Regulatory and payer actions are shaping near-term access and long-term demand patterns:
- Regulatory classifications and test complexity designations are material. A notable development in late 2025 saw a mass spectrometry–based 25-hydroxy vitamin D assay categorized as Moderate Complexity—an event with immediate implications for decentralization and laboratory-sourcing models.
- Medicare and payer guidance continues to evolve. The retirement of certain Medicare local coverage guidance in mid‑2025 and selective revisions to billing and coding documents have created both compliance risk and opportunities for labs that can evidence medical necessity under updated LCD criteria.
- Commercial payers are refining policy language: several plan-specific updates in 2025–2026 now emphasize diagnosis-code alignment and prior authorization rules linked to discrete CPT and proprietary codes.
Decision-makers must therefore bake policy-sensitivity into their 2026 plans: a product launch or price change that looks attractive on raw market growth can be derailed by shifting CPT/LCD interpretations or plan-level claim edits.
Competitive landscape — concentrated but dynamic
The market’s concentration is meaningful but not immovable. PW Consulting’s competitive analysis shows a moderately consolidated supplier base: three-firm concentration and five-firm concentration metrics indicate incumbent strength, yet there remains room for niche innovators and vertically integrated labs to capture value. Key players that shape industry structure include:
- Roche Diagnostics — with a strong clinical sales and service footprint; recent regulatory milestones around mass spectrometry testing materially shift the accessibility of higher-specificity assays to a broader set of clinical labs.
- DiaSorin S.p.A. — a specialist player with assay-focused portfolios and channel relationships in core European markets; their product roadmap positions them to compete on both accuracy and lab workflow integration.
- Abbott Laboratories — notable for scale in instrument placements and reagent revenues, with distribution strengths in hospital and reference lab segments.
- Siemens Healthineers — leveraging integrated diagnostics platforms and lab automation capabilities to sell testing solutions as part of broader laboratory modernization programs.
- Beckman Coulter, Thermo Fisher Scientific, Quidel Corporation, Bio‑Rad Laboratories — each occupies differentiated niches from high-volume immunoassays and mass-spec consumables to point-of-care and decentralized testing options.
Strategically, incumbents differentiate on three vectors: analytical performance, integration into laboratory IT and automation ecosystems, and channel/service economics (pricing, reagent-on-contract, maintenance). New entrants that focus solely on analytical superiority without credible channel and reimbursement strategies face elongated commercialization timelines.
What the full report delivers (practical, transaction-ready content)
PW Consulting’s full market study is structured to be operational from day one. Highlights include:
- Proprietary market-sizing model (base year 2025) with a transparent forecast engine for 2026–2032, including scenario toggles for regulatory shifts, technology substitution rates, and pricing pressure.
- Competitive profiles and product mappings for the leading suppliers, with go-to-market playbooks tailored to instrument vendors, reagent-only suppliers, and diagnostics start-ups.
- Reimbursement & regulatory tracker that aggregates LCDs, CPT-level developments, and payer-specific policy updates impacting clinical access across major jurisdictions.
- Laboratory adoption curves and capital investment calculators that help hospital labs and reference networks evaluate the ROI of mass spectrometry versus automated immunoassay pathways.
- Commercial templates — segmented sales/marketing messages, pricing negotiation playbooks, and sample contracting language for reagent and service agreements.
- M&A and partnership intelligence: a proprietary list of likely targets, valuation benchmarks, and integration risk checklists for strategic acquirers and private equity investors.
- Risk heatmaps and sensitivity analyses: quantifying impact of potential policy changes (e.g., LCD revision, CPT retirements) on revenue and unit volumes across scenarios.
To preserve competitive confidentiality and to honor data-use agreements, this preview omits granular regional and application-level splits and the underlying tables; those detailed worksheets are accessible only in the full report package.
Strategic playbook for 2026
For executives making allocation decisions in 2026, PW Consulting recommends a three-part approach:
- Prioritize channel-aligned innovation. Invest selectively in test platforms whose deployment economics align with the target laboratory profile (centralized reference labs, hospital core labs, or decentralized clinic labs). Matching technical claims to purchaser pain points (turnaround time, cost per test, throughput) accelerates adoption.
- Lock in reimbursement pathways early. Create cross-functional teams (clinical affairs + reimbursement + commercial) to generate the evidence dossiers and coding strategies required to pass plan-level medical necessity reviews and to shepherd new assays through local coverage processes.
- Develop hedged commercialization scenarios. Use the PW forecast toggles to stress-test pricing and volume assumptions under alternative policy outcomes; maintain flexibility in supply chain and reagent-contract terms to respond to rapid shifts in demand.
For investors and M&A teams, the clearest opportunities will be targets that combine analytical differentiation with established lab channel access or that offer enabling software solutions (lab informatics, decision support) to lower the operational friction of adoption.
Methodology and credibility
The analysis reflects a blended-methods approach: triangulation of primary interviews with laboratory directors and procurement leads, contract-level intelligence, payer policy review, and bottom-up build of testing volumes from epidemiology and clinical practice patterns. Base-year alignment is to 2025, and the forecast horizon is 2026–2032. Concentration metrics (three‑firm and five‑firm concentration ratios) are calculated from supplier revenue estimates to indicate market structure and competitive intensity.
Next steps — why this matters for your 2026 plan
At market scale, the value pool is expanding—but the path to capture is becoming more conditional on regulatory alignment, lab capability, and channel economics than it was five years ago. PW Consulting’s full Vitamin D Testing Market report converts growth forecasts into executable strategies: bid-ready commercial materials, reimbursement dossiers, lab ROI calculators, and an opportunity map by buyer type. For teams evaluating product launches, capital investments, or acquisition targets, the report is designed to shorten the time from analysis to decision.
How to access the full study
This preview is intended to demonstrate the analytical depth and practical orientation of our work while preserving the proprietary data that underpins tactical decisions. To obtain the full dataset, detailed segment tables, and the interactive forecast model—required for transaction diligence or operational planning—please contact PW Consulting or visit our report page. Our advisory team can also arrange a tailored briefing that maps the report’s insights to your specific strategic questions.
For detailed analysis of this topic, please visit the official page: Vitamin D Testing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Shooting Market to Hit USD 343.48M by 2032 at 6.8% CAGR
By pmarketresearch, 2026-07-30
Shooting Market 2026: Strategic Imperatives from PW Consulting’s Market Outlook
Overview
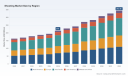
As organizations across manufacturing, retail, range operations, and training services look to 2026 as a year for decisive investment, PW Consulting’s Shooting Market study provides a data-driven compass for strategy. The sector has shown steady expansion through the first half of the decade, climbing from a clearly measurable base in 2020 to a substantially larger market in the base year of our study (2025). Our forecast through 2032 projects continued growth at a compound annual growth rate (CAGR) of 6.8% across the 2026–2032 horizon, culminating in a materially expanded market by 2032. These macro dynamics create both opportunity and urgency: the market is large enough to warrant scale plays, yet fragmented enough to reward targeted capability investments.
Shooting Market
Why this matters for 2026 decision-making
-
Capital allocation under uncertainty: With the market trajectory established and a mid-single-digit CAGR guiding expectations, capital planners should shift from defensive preservation to selective growth — prioritizing investments that shorten time-to-revenue and de-risk regulatory exposure. Our report includes modeled capex/opex scenarios that translate market growth assumptions into portfolio-level investment needs.
Shooting Market -
Product and portfolio strategy: The market’s expansion is uneven across use cases and product categories (as detailed in the full study). Firms that refine product mixes — balancing recreational, training, and competitive offerings — can capture premium pricing and higher lifetime value. We provide go-to-market playbooks for repositioning legacy products and introducing next-generation simulators and modular range systems.
Shooting Market -
Operational resiliency and cost management: Elevated labor and specialized maintenance costs are a recurring force in range operations and services. In 2026, operators will need precision staffing models and predictive maintenance programs to protect margins. Our benchmarking templates allow executives to stress-test labor and maintenance cost assumptions against the market forecast.
-
Regulatory and trade risk mitigation: Changes to export controls, licensing, and compliance frameworks are active and enforceable. The study synthesizes the practical impacts of recent regulatory updates — including export control adjustments and federal licensing revisions — and maps compliance checkpoints to product development, distribution, and aftermarket support.
-
M&A and partnership prioritization: The sector’s competitive structure signals opportunity for bolt-ons and capability buys, particularly where incumbents lack digital training platforms or advanced target systems. Our M&A playbook ranks acquisition archetypes by value capture potential and regulatory risk exposure.
What the PW Consulting report delivers (practical, executable tools)
The objective of this study is not merely to describe market growth but to equip leaders with operational instruments they can apply immediately. The report package includes:
-
A transparent forecast model (historical 2020–2025; base year 2025; forecast 2026–2032) with scenario toggles to evaluate alternative growth rates and demand shocks.
-
Commercial playbooks for range operators, manufacturers, and training-service providers — covering product roadmaps, pricing architectures, and channel strategies focused on accelerating adoption of simulators and low-cost training platforms.
-
Capital planning templates calibrated to the sector’s cost structure and investment cycles, including sensitivity analyses for labor and infrastructure cost inflation.
-
Regulatory compliance checklist tied to recent federal updates and export control changes, with practical steps for manufacturer and operator compliance workflows.
-
Competitive benchmarking tools and a short-list of strategic partnership archetypes, enabling faster diligence and integration planning.
-
Risk heatmaps and mitigation playbooks covering supply-chain disruption, regulatory shifts, and liability exposure for range operators.
For confidentiality and strategic clarity, the report intentionally abstracts certain granular segmental figures in public summaries; full segment-level tables and downloadable models are available in the comprehensive dataset.
Competitive landscape: structure and strategic moves
The shooting market presents a mixed structure: meaningful scale players operate alongside numerous specialized manufacturers and service providers. Market concentration metrics indicate a fragmented market where the largest three firms capture under a quarter of total revenue, and the top five only modestly more. That fragmentation validates varied strategic approaches — from scale-oriented consolidation to niche dominance through product differentiation.
-
Action Target — A range-systems integrator known for end-to-end facility delivery, Action Target remains a front-runner in commercial and tactical range infrastructure. Their platform-level innovations (for example, next-generation range control and target systems) and high-profile trade-show presence underscore their focus on productizing turnkey solutions for large-scale clients. Recent product showcases highlight their continued investment in smart range technologies that integrate moving targets and advanced safety systems.
-
Range USA, Inc. — As a supplier of range equipment and infrastructure, Range USA’s model emphasizes modular systems and retrofit capabilities. Companies seeking to upgrade existing facilities without full rebuilds will find their solutions strategically relevant; our benchmarking evaluates retrofit ROI under multiple utilization scenarios.
-
Cubic Corporation — Cubic’s strength is in training and simulation, where virtual and synthetic environments meet defense and law-enforcement buyers. Their offering illustrates the high-margin, software-enabled segment of the market. For firms exploring software–hardware bundles, Cubic’s approach provides important lessons about recurring revenue and customer lock-in.
-
Beretta USA, Kel-Tec, Air Arms, Weihrauch — These manufacturers represent diverse product strategies from premium precision airguns to compact firearms and accessories. Their presence highlights the continued relevance of product engineering, brand heritage, and distribution reach. Manufacturers with deep OEM or brand equity can leverage those assets to accelerate adoption of premium and training-oriented product lines.
-
NSSF — The industry association plays a coordinating role, publishing guidance and standards that shape compliance and best practices. For operators and manufacturers, engagement with NSSF’s resources is required to stay current with evolving safety, training, and regulatory expectations.
Recent industry developments — such as trade-show demonstrations of advanced range technologies — confirm that innovation remains a primary differentiator. At the same time, regulatory updates and infrastructure compliance requirements are re-shaping where and how investments are prioritized.
Regulatory and operational headwinds (and tactical responses)
-
Export controls and licensing: Updates to export controls and federal licensing frameworks in recent years are active considerations for 2026. Companies expanding cross-border must embed compliance into early-stage product design and contractual terms to avoid costly after-the-fact retrofits.
-
Infrastructure compliance and safety: NSSF guidance and federal revisions impose capital and operational requirements on range infrastructure. Operators will need to accelerate safety-system upgrades and document maintenance regimes; our templates calculate lifecycle costs and compliance timelines to support procurement planning.
-
Labor and operating cost inflation: Specialized staffing — from certified instructors to range technicians — drives operating expense growth. The report provides staffing models that connect utilization rates to break-even thresholds and margin sensitivity.
How executives should use this study in 2026
-
Use the forecast model as a planning anchor, then layer scenario analyses (regulatory tightening, supply-chain shock, rapid adoption of virtual training) to stress-test capital and resource allocation.
-
Prioritize initiatives that shorten payback: modular retrofits, software-enabled recurring revenue streams, and targeted channel partnerships deliver faster returns than large greenfield investments.
-
Operationalize compliance: integrate the report’s compliance checkpoints into procurement and product development cycles to reduce time-to-market and limit legal exposure.
-
Design M&A with integration playbooks: target acquisitions that fill capability gaps (simulation software, target systems, service networks) rather than purely revenue accretion; our diligence templates and integration checklists are ready for immediate use.
Next steps and access
PW Consulting’s Shooting Market study is designed as an operative briefing for executives making allocation decisions in 2026. It combines a rigorously documented macro forecast (historical 2020–2025; base year 2025; forecast 2026–2032 with a 6.8% CAGR), practical toolkits, and competitive diagnostics that translate insight into action. To preserve strategic value in a contested market, this public summary intentionally omits detailed segment tables and company-level scorecards; these are available in the full report package, which includes downloadable models, segment-level demand drivers, and supplier scorecards.
For organizations evaluating capital projects, market-entry strategies, or M&A targets this year, the full dataset and executable playbooks will materially reduce timeline and execution risk. Contact PW Consulting through our report access page to retrieve the full intelligence suite and a customized briefing for your executive team.
For detailed analysis of this topic, please visit the official page: Shooting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Bolt Market to Reach $115.3M by 2032 at 3.48% CAGR — PW Consulting Insight
By pmarketresearch, 2026-07-30
Bolt (Fastener) Market: A 2026 Strategic Primer for Executive Decision‑Making
As PW Consulting’s lead industry analyst, I present an executive introduction to our latest Bolt (Fastener) Market study — designed explicitly to equip corporate leaders with the actionable perspective they need in 2026. The global market, measured on a USD Million basis, has expanded from roughly USD 71.0 Million in 2020 to a 2025 base of about USD 91.04 Million, and our forward view projects continued expansion to the low‑hundreds by the end of the 2026–2032 forecast window (reaching roughly USD 115.3 Million by 2032). That represents a steady compound annual growth rate of approximately 3.48% across the forecast period. These headline numbers frame the opportunity set; the strategic aim of this primer is to translate them into practical choices for procurement, manufacturing, portfolio, and M&A leaders.
Bolt (Fastener) Market
Why this research matters for 2026 decisions
- Timing capital investments: Moderate but persistent growth and the uneven year‑to‑year cadence we observe in the 2026–2032 forecast imply that plant expansion and automation investments should be staged and tied to demand triggers rather than broad, front‑loaded capacity builds.
- Supply‑chain risk management: Raw material volatility and labor constraints are recurrent pressures — procurement teams must adopt hedging, multi‑sourcing, and inventory optimization strategies to avoid margin erosion.
- Commercial segmentation and pricing: End‑market cyclicality (notably automotive, construction, and industrial machinery) requires differentiated go‑to‑market and pricing playbooks rather than a one‑size‑fits‑all approach.
- M&A and partnership prioritization: Mid‑market consolidation dynamics create windows for bolt‑and‑nut players to scale through targeted acquisitions or logistics/technology partnerships — but value realization depends on playbook execution.
- ESG and standards compliance: Emerging standards activity and sustainability expectations are reshaping supplier qualification and product claims, with implications for certification costs and market access.
Key market dynamics shaping 2026 strategy
- Raw materials and price pressure: Steel remains the dominant cost driver. As of early June 2026, benchmark steel pricing stood at approximately 3,152 CNY per tonne — up around 6.9% year‑on‑year — transmitting cost pressure across the value chain and compressing margins for players unable to pass through increases.
- Standards and technical governance: Industry institutions have intensified standards stewardship. Notably, the Industrial Fasteners Institute ran its inaugural Standards Camp in mid‑2026 and continues to steer technical committee work — an operational reality for product engineers and compliance teams.
- Workforce and capacity constraints: The fastener sector remains labor‑intensive; global employment metrics indicate a workforce base in the millions with ongoing localized shortages that complicate ramp schedules and increase unit labor costs.
- Trade shows and knowledge flows: 2026 saw key convenings — Fastener Fair USA in May and the International Fastener Expo in October — which catalyzed a wave of product and logistics innovations visible across suppliers and OEM procurement teams.
- Macro oversupply/industry cycles: Broader metal industry signals — including international dialogues on steel excess capacity — inject episodic price and trade‑policy risk into fastener sourcing strategies.
Competitive landscape — who matters and why
The market structure is neither fully fragmented nor dominated by a tiny oligopoly. Top players exert meaningful influence through distribution networks, specialty product portfolios, and value‑added services, but there remains room for nimble competitors to capture niche or regional positions.
Bolt (Fastener) Market
- Würth Group (Künzelsau, Germany): A distribution and branch network powerhouse, Würth’s global footprint and extensive product range create a strong platform for integrated logistics and small‑lot servicing to construction and industrial buyers.
- LISI Group (Grandvillars, France): A specialist in high‑spec fasteners for aerospace, automotive, and medical applications — their engineering depth and certification credentials position them for higher‑margin segments.
- Bossard Group (Zug, Switzerland): Notable for fastening technology and logistics systems; Bossard’s focus on assembly efficiency and inventory services makes it a preferred partner for lean manufacturers.
- SFS Group (Heerbrugg, Switzerland): Precision fastening and assemblies for industrial customers; strengths include close engineering collaboration and custom component supply.
- Bulten AB (Gothenburg, Sweden): An automotive‑focused fastener supplier with deep OE and tier‑1 relationships, tuned to the vehicle manufacturers’ quality and scale requirements.
- Hilti Corporation (Schaan, Liechtenstein): Although broader than just fasteners, Hilti’s construction‑grade fasteners and tools combine product differentiation with strong brand recognition in building markets.
- Precision Castparts Corp (Lake Oswego, USA): Supplier of investment castings and high‑strength forged components — positioned for high‑value aerospace and power‑generation fastener requirements.
Strategically, these companies represent four archetypes: distribution and branch scale, engineered‑component specialists, logistics/assembly service innovators, and multi‑segment OEM partners. The competitive implications for 2026 are straightforward: scale matters for price and reach, engineering depth wins certified and high‑margin work, and logistics/automation capability is becoming a defensible competitive moat.
Bolt (Fastener) Market
What the PW Consulting report delivers (practical contents)
Our full report goes well beyond headline growth figures to deliver deployable intelligence across decision horizons. Key elements include:
- Methodology and transparent assumptions underpinning our historical reconstruction (2020–2025) and the 2026–2032 forecast.
- Market sizing and scenario tables (interactive dashboards) that let executives model demand on alternative macro and end‑market trajectories.
- Supply‑chain mapping and cost build‑ups — from raw‑steel price sensitivity to labor and logistics components — to support margin and sourcing stress tests.
- Regulatory and standards matrix with compliance impact scoring tailored by product families and end uses.
- Comprehensive company profiles, capability maps, and partnership/opportunity heatmaps for M&A and supplier selection.
- Commercial playbooks for procurement, pricing, aftermarket, and product standardization to improve working capital and reduce SKU complexity.
- Risk registers and a prioritized mitigation roadmap (covering raw materials, labor, trade policy, and climate‑related supply disruptions).
Note: this introduction intentionally emphasizes the strategic contours. Detailed tables that break down type, application, and regional splits (and the company‑level KPIs that drive M&A screens) are available in the full report and via the source page.
Actionable strategic recommendations for 2026
- Hedge steel exposure and adopt trigger‑based procurement: Combine multi‑tier supplier contracts with indexed pricing clauses and a calibrated buffer inventory to smooth volatility without tying excessive capital.
- Prioritize automation in assembly and logistics: Target investments that reduce dependence on scarce labor and shorten lead times — robotics in sorting and automated replenishment systems offer the fastest payback in many plants.
- Shift to modular standardization: Rationalize SKUs and push commonality across platforms to reduce inventory carrying costs and simplify supplier management.
- Develop service and aftermarket revenue streams: For distribution players, create bundled installation, inspection, and certified repair services to extend customer lifetime value.
- Selective M&A and strategic partnerships: Acquire engineering‑led niche manufacturers to access certified product lines, or partner with logistics tech providers to accelerate distribution efficiency.
- Invest in standards and certification capability: Be proactive in standards committees (technical participation) to shape specifications and reduce compliance surprises.
- Address workforce gaps with training and automation: Combine targeted recruitment with reskilling programs linked to automation projects to maintain throughput and quality.
How senior teams should use this report in 2026
- Board level: Use the forecast scenarios to stress‑test capital allocation and M&A authorization thresholds.
- CFO/Procurement: Incorporate price‑sensitivity models and supply‑chain risk heatmaps into budgeting and supplier scorecards.
- COO/Manufacturing: Apply the operational playbooks and benchmarking to prioritize automation, floor‑plan changes, and SKU rationalization pilots.
- Corporate development: Filter acquisition targets through our capability maps and integration templates to accelerate due diligence.
Closing: where to find the full intelligence
This primer is intentionally selective — a “trailer” that demonstrates the analytical depth and practical orientation of PW Consulting’s Bolt (Fastener) Market study while preserving the granular subsegment and company metrics that give competitors their commercial edge. For access to the full dataset, interactive dashboards, and the detailed segmentation tables (by type, application, and region), please consult the full report and our data portal. PW Consulting’s team stands ready to tailor the findings into a decision package that fits your 2026 strategic planning cycle.
For detailed analysis of this topic, please visit the official page: Bolt (Fastener) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Locker Locks Market Poised for 5.0% CAGR from 2026–2032
By pmarketresearch, 2026-07-30
Locker Locks Market: Strategic Insights for 2026 Decision-Making
Executive snapshot
As organizations recalibrate physical-security investments in a post-pandemic, data-conscious world, the global locker locks market stands at a meaningful inflection. Our analysis uses 2025 as the base year, traces developments since 2020, and projects through 2032. The market—which expanded from a clear five-year historical base—registered measured growth to approximately USD 125 million in 2025 and is expected to continue on a steady trajectory (approximate CAGR 5.0% over the forecast window). Concentration remains material: the top three vendors account for roughly 70% of revenue, and the top five capture about 85%, underscoring a market where scale, channel reach and product breadth matter for sustained leadership.
Locker Locks Market
Why this research matters for 2026 decision cycles
- Timing: 2026 is the first full planning year following several product refreshes from major OEMs and a fresh wave of regulatory clarifications affecting electronic access systems. Tactical choices made this year—on product roadmaps, OEM partnerships, and procurement standards—will govern multi-year market share outcomes.
- Risk management: New privacy and safety requirements (notably GDPR-driven audit-trail expectations, CE marking regimes in the EU, and U.S. workplace safety rules relating to lockout/tagout) mean that product compliance, data architecture and after-sales processes are now strategic risk vectors rather than checkbox items.
- Return optimization: With a steady mid-single-digit CAGR anticipated, volume alone will not deliver outsize returns. Winning players will differentiate through adjacent services, platform integrations and channel economics.
Market trajectory and structural signals
The market’s historical performance from 2020 through 2025 shows a stable expansion path, and our forecast through 2032 projects continued single-digit growth moderated by periodic product refreshes and adoption cycles of smarter, networked solutions. That pattern reflects two interacting dynamics: first, mature replacement and retrofit cycles in institutional and corporate environments; second, incremental new demand driven by digital access requirements, hospitality and multi-family housing conversions.
Locker Locks Market
Important structural characteristics include:
- Relatively high market concentration—indicating scale advantages in manufacturing, distribution and brand-driven procurement.
- Product diversification across mechanical, electronic and hybrid systems—where different value propositions (cost, convenience, compliance) map to different buyer segments and procurement levers.
- Emerging cost complexities for networked systems—install-time cabling (PoE) versus battery-powered wireless solutions meaningfully changes total installed cost and upgrade pathways.
Drivers, constraints and regulatory overhangs
Demand drivers are a combination of secular and tactical factors: workplace reopenings and reconfigurations, multi-family property upgrades, locker-as-a-service deployments in shared-economy venues, and institutional investments in asset security. On the technology front, the adoption of Bluetooth, NFC and cloud-managed locker management platforms is accelerating, but buyers remain sensitive to life-cycle cost, interoperability and data-security assurances.
Two regulatory/standards developments deserve special attention for 2026 planning:
- Data privacy and audit trails: Enforcement and buyer expectations stemming from GDPR-like regimes are raising the bar for encrypted logs and proof-of-access. For vendors, this transforms software modules and firmware architecture from differentiation points into table stakes.
- Safety and access control standards: OSHA-style lockout/tagout requirements and CE conformity frameworks are tightening acceptance windows for new products in certain geographies. Compliance timelines and third-party testing windows must be integrated into product launch plans.
Competitive landscape — what to watch
The competitive map is balanced between long-established mechanical specialists and more recent electronic/smart entrants. Notable companies shaping market dynamics include:
- Master Lock Company (United States) — a legacy brand with broad commercial and consumer offerings, increasingly active in smart commercial locks and partnerships targeting multi-family and SMB segments.
- Abloy Oy (Finland) — recognized for high-security mechanical and hybrid electronic locking solutions, often positioned in high-assurance institutional installations.
- Codelocks (United Kingdom) — a fast-moving innovator in compact digital and kit-lock systems; recent launches broaden their addressable installations and suggest an aggressive mid-market push.
- Lowe & Fletcher, Digilock, EMKA, Hettich and Häfele — firms with strong OEM or distribution capabilities, supplying integrated furniture, cabinet and locker-specific hardware solutions.
- Allegion, Ojmar, LockeyUSA, Zephyr Lock — established access-control players increasingly layering smart features or distribution partnerships to defend installed bases.
- China-based suppliers (e.g., Be-Tech, MAKE, Ningbo Wangtong) — competitive on cost and feature-rich electronic options; critical as contract manufacturing and OEM-sourced components become more prominent in procurement decisions.
Recent product activity—multiple launches from both traditional names and newer entrants—indicates the market is in a phase of feature consolidation (miniaturization, dual-function locks, stronger enclosures) and platform evolution (integration with building management and locker-management SaaS). This intensifies competition on product roadmap, channel partner coverage and software ecosystems rather than on purely hardware price.
Strategic implications and recommended actions for 2026
For incumbent suppliers, challengers and buyers, the following decision levers will materially influence outcomes in 2026 and beyond:
- Portfolio strategy: Prioritize modular architectures that allow mechanical lockbacks and electronic upgrades without full cabinet replacement. This minimizes customer friction in upgrade cycles and protects installed-base value.
- Compliance-first product development: Embed encryption, audit trails and third-party certification plans into R&D roadmaps. Non-compliant launches risk procurement delays and contract penalties in regulated environments.
- Channel and service economics: Reconfigure go-to-market to favor value-added installers and systems integrators that can deliver turn-key locker systems—bundling hardware, cabling decisions (PoE vs. battery) and software subscription offerings.
- M&A and partnerships: Use M&A to close capability gaps—software platforms, secure cloud services, or regional distribution. For larger incumbents seeking growth, bolt-on acquisitions of niche smart-lock vendors or SaaS locker-management firms can accelerate access to recurring revenue models.
- Supply-chain resilience: Hedge component concentration, especially for electronics and battery modules. Consider dual-sourcing for critical subassemblies and negotiating long-lead commitments tied to compliance documentation.
- Pricing and TCO selling: Shift purchasing conversations to total-cost-of-ownership narratives that account for installation labor, cabling, firmware updates and data-compliance costs—this preserves margins on higher-value, integrated offerings.
What our full report delivers — practical, execution-ready content
This research is deliberately structured to be operational for 2026 planners. Highlights include:
- Quantitative market sizing and a transparent forecast model (2026–2032) built on validated install-base and replacement-rate assumptions.
- Scenario analyses mapping regulatory and technology adoption variants to revenue and margin outcomes—enabling contingency planning.
- Channel economics and buyer persona matrices that convert macro trends into procurement playbooks for sales, product management and M&A teams.
- Vendor scorecards and comparative capability maps that evaluate product breadth, compliance readiness and software ecosystems—designed to support short-listing and supplier negotiations.
- Implementation toolkits: sample RFP clauses for encrypted audit-trails and safety compliance, installation cost worksheets contrasting PoE vs. battery-powered architectures, and a checklist for field retrofits to minimize downtime.
Data integrity, methodology and what we intentionally withhold
Our base year is 2025; the historical window spans 2020–2025 and the forecast horizon is 2026–2032. We triangulated primary interviews, OEM public disclosures, installer surveys and transactional pricing data to arrive at the market model. To preserve the report’s commercial value and adhere to a “teaser” approach, this introduction omits the granular regional and application splits and specific segment revenue figures that are included only in the full report. The detailed segmentation, supplier share matrices (down to five-player concentration by subsegment), and the underlying model spreadsheets are accessible via the source download.
Quick read on near-term signals to act on in 2026
- Prioritize product launches that combine strong physical robustness with encrypted software logs—these will cross the compliance bar faster and shorten sales cycles.
- If you are a buyer, insist on testable audit trails and a documented CE/GDPR/OSHA compliance matrix during RFP evaluation to avoid post-deployment surprises.
- If you are a vendor, accelerate partnerships with locker-management SaaS providers or certify your APIs to be integrable with leading building-management platforms—this unlocks higher-margin recurring revenue.
- Evaluate aftermarket service and retrofit offers as a defensive play to monetize the large installed base while slowing customer churn.
Closing—how PW Consulting can accelerate your 2026 roadmap
Our Locker Locks Market study is designed to translate market metrics into executable choices. Whether your priority is defending share, entering new geographies, or building a software-enabled recurring business, the report supplies the data, competitive context and procurement instruments to reduce execution risk. For procurement teams, product executives, M&A sponsors and channel strategists, 2026 is a planning inflection: the decisions made now will determine who captures disproportionately more of the modest-but-stable growth that the market offers.
To access the full dataset, segmentation breakdowns, vendor scorecards and the forecast model, consult the PW Consulting report landing page (full access available for licensed clients). Our team is available for tailored briefings and to run custom scenario models aligned with your product and go-to-market priorities.
For detailed analysis of this topic, please visit the official page: Locker Locks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High Voltage Cables Market to Grow to USD 63.81M by 2032 (6.08% CAGR)
By pmarketresearch, 2026-07-30
High Voltage Cables Market — Strategic Preview for 2026 Decision-Makers
As energy systems accelerate toward higher-capacity transmission, deeper subsea links and widespread renewable integration, decisions made in 2026 will set the competitive trajectory for the next decade. PW Consulting’s High Voltage Cables Market study (base year 2025; forecast period 2026–2032) synthesizes historical performance, a rigorous forecast framework and project-level intelligence to translate market signals into executable strategies. The market has expanded materially from the early 2020s — rising from roughly USD 25–26 million in 2020 to an estimated USD 42.4 million in 2025 — and is projected to continue growing through 2032, reaching about USD 63.8 million under our central case. The 2026–2032 compound annual growth rate (CAGR) underpins that trajectory at approximately 6.08%.
High Voltage Cables Market
Why this study matters in 2026
-
Timing: 2026 is a hinge year for capex cycles and project awards across offshore wind, long‑distance DC transmission and national grid reinforcements. Several high‑value projects that will consume high‑voltage (HV) cable capacity are moving from feasibility to firm procurement, making supplier selection, manufacturing commitments and installation scheduling urgent.
High Voltage Cables Market -
Input‑cost volatility: raw materials and installation inputs remain a critical margin driver. For example, copper wire pricing and availability materially affect tender pricing and sourcing strategies; industry indices showed copper electric wire costs near USD 416 per thousand linear feet in April 2026, creating immediate implications for bids, hedging and contract structure.
High Voltage Cables Market -
Regulatory and system‑operator momentum: major system owners continue to propose and sanction sizeable HVDC programmes — exemplified by a multi‑billion capital plan submitted for an HVDC upgrade between major islands — and cross‑TSO coordination initiatives are forming new infrastructure corridors, especially in the North Sea and other offshore zones. These are structural demand drivers, not one‑off phenomena.
-
Technology and execution complexity: recent project milestones, including world‑record subsea installation depths and multiple high‑voltage contract awards, demonstrate rapidly evolving technical capability among suppliers and raise the bar for delivery risk management and installation logistics.
What this report delivers (practical, operational intelligence)
-
Market sizing and granular forecasting: transparent methodology and scenario outputs that translate macro drivers into a validated, project‑level demand runway for 2026–2032 (base year 2025).
-
Supply‑side capability maps: manufacturing capacity, installation fleet availability, lead times, and an assessment of technological readiness across AC and DC product families.
-
Procurement and cost modelling toolkit: indexed cost build‑ups that incorporate raw material trends, manufacturing yield assumptions, transport and installation risk premia — designed to be drop‑tested against live tenders.
-
Project pipeline and tender tracker: a curated dataset of near‑term to mid‑term projects, procurement windows and counterparty profiles to prioritize commercial effort and resource allocation.
-
Commercial playbooks: tailored go‑to‑market strategies for suppliers, utilities and investors — from pricing templates and risk allocation clauses to JV frameworks for offshore installation.
-
Risk matrices and scenario stress tests: quantified implications of material price shocks, permit delays, and installation failures on cash flows and delivery schedules.
Competitive landscape — who matters and what they signal
The market exhibits moderate concentration at the top: the top three groups account for a substantial share of global volume and capability, while the top five capture just over half the market by revenue and capability metrics. This concentration creates a dual dynamic — a small set of suppliers able to execute very large, complex projects, and a long tail of regional manufacturers and integrators competing on lead time, local content and aftermarket services.
-
Nexans (Paris, France) — Demonstrated capability in deep subsea HVDC with recent installation milestones at world‑record depths. Their execution competence for complex subsea links makes them an obvious counterparty for projects requiring novel installation techniques and risk‑sharing structures.
-
Prysmian Group (Milan, Italy) — Continued focus on high‑voltage HVAC solutions for floating offshore wind and integrated offshore platforms. Prysmian’s portfolio suggests strategic emphasis on adaptable HVAC systems that reduce offshore interface complexity.
-
NKT A/S (Copenhagen, Denmark) — Large, firm contracts for HVDC power cable systems demonstrate a leaning toward utility‑scale grid reinforcement projects. Their recent award for a major grid reinforcement underscores appetite for long‑duration contracts with system operators.
-
Sumitomo Electric Industries Ltd (Tokyo, Japan) — Strong in very high‑voltage HVDC lines and major subsea link supply. Recent contract awards for 525 kV HVDC projects show the company’s technical positioning at the highest voltage classes.
-
LS Cable & System Ltd (Seoul, South Korea) — Growing presence in high‑voltage HVDC applications and strategic programmes in Asia; capabilities suggest a focus on large interconnector and national transmission projects.
-
Regional and specialist players — Several firms from established manufacturing hubs (including Italy, India and elsewhere) provide competitive depth up to specific voltage classes and are often preferred for local content, shorter lead times and aftermarket services.
Recent developments provide telling market signals: Nexans’ completion of a record‑depth subsea 500 kV HVDC installation (Jan 2026) confirms both technology maturity and the premium buyers will pay for proven installation capability; Sumitomo’s late‑2025 contract for a 525 kV HVDC Sea Link underscores high‑voltage demand in national interconnection projects; and NKT’s firm contract wins (Mar 2026) highlight sizeable programme awards becoming available to bidders in 2026.
Market dynamics and near‑term headwinds
-
Input price inflation and hedging complexity — Copper and polymer feedstock price swings compress margins and complicate fixed‑price contracting. Buyers and suppliers must consider indexation, pass‑through clauses, or hedged procurement strategies.
-
Manufacturing bottlenecks and lead times — High‑voltage cable production and jointing capacity are capital‑intensive; firms that secure long‑lead manufacturing slots will gain bidding advantage for multi‑year programmes.
-
Regulatory programme timing — Decisions by TSOs and national governments (including multi‑billion capex proposals and coordinated offshore initiatives) will create concentrated procurement windows that favor vertically integrated suppliers or consortiums.
-
Installation risk and technical escalation — Deepwater and ultra‑high voltage projects carry installation and testing complexity; record installations signal capability but also raise the stakes on insurance, indemnities and performance bonds.
Practical recommendations — what executives should do in 2026
-
Procurement readjustments — Move from single‑round, fixed‑price tenders to staged contracting with material price indexation and firm slots for critical long‑lead items. Shortlist suppliers with demonstrable recent installation performance.
-
Supply‑chain hedging — Lock in raw‑material forward contracts where justified; use layered buying to smooth exposure and include contingency margins in financial models.
-
Strategic partnerships — Pursue consortiums for high‑risk offshore or HVDC projects to combine manufacturing scale, installation vessels and local permitting expertise.
-
Capability building — For suppliers: invest selectively in high‑voltage HVDC manufacturing lines and jointing technology. For buyers: expand in‑house project‑management teams with subsea and HVDC execution experience.
-
M&A and market entry — Target acquisitions that provide either installation fleet access or specialized jointing/termination capabilities rather than pure volume players. Assess targets against capacity, certificates and recent project track record.
-
Scenario planning — Run stress tests for +20% raw material shock, 6–12 month permit delays and a concentrated procurement window to quantify working capital and schedule impacts before committing to awards.
How boards, CFOs and operations teams should use this research
-
Boards : Use the report’s scenario suite to validate strategic capital allocation, JV structures and M&A prioritization before approving multi‑year commitments.
-
CFOs : Leverage the procurement and cost‑modeling toolkit to refine bid/no‑bid thresholds, approve hedging instruments, and structure payment milestones tied to installation milestones and CPI‑linked indices.
-
Operations and procurement : Adopt the supplier capability matrices and project pipeline tracker to optimize lead‑time sequencing, prequalify partners and align internal resourcing to the procurement calendar.
Conclusion — a strategic preview, not the full map: This article has outlined the strategic contours derived from PW Consulting’s High Voltage Cables Market study and highlighted the core commercial and technical levers that will matter in 2026. We have deliberately presented top‑line market growth indicators and synthesized directional competitive and technical signals to support boardroom decision‑making. For the full, actionable intelligence — including project‑level demand schedules, downloadable financial models, voltage‑class build‑outs, regional pipelines, and supplier scoring matrices — access the comprehensive report and dataset. That is where programmatic procurement decisions, M&A screening and capital planning for the next decade are executable with confidence.
For detailed analysis of this topic, please visit the official page: High Voltage Cables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Drugs for Schistosomiasis Market: Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a forward-looking briefing that situates the Drugs for Schistosomiasis market within the strategic decision cycle for 2026. This preview highlights the macro trajectory, risk vectors, competitive dynamics, and the actionable themes executives must address to convert epidemiological need into resilient commercial and public-health outcomes. It intentionally surfaces high-value signals and practical implications while reserving granular segmentation and proprietary model outputs for our full market study.
Drugs for Schistosomiasis Market
Why this market matters in 2026
Schistosomiasis remains a high-priority neglected tropical disease with concentrated programmatic spending, frequent mass drug administration (MDA) campaigns, and evolving pharmaceutical supply needs. The overall market shows steady, predictable expansion: from an estimated USD 118.5 Million in 2020 to USD 160.0 Million in our base year (2025), with a compounded annual growth rate of approximately 6.4% through the forecast window to 2032. Under our central forecast the market approaches a mid-to-high two-hundred million USD valuation by 2032, reflecting continued demand for praziquantel-based treatments, pediatric formulations, and emerging combination therapies.
Drugs for Schistosomiasis Market
For corporate leaders—pharma CEOs, commercial heads, supply-chain chiefs, and public-sector procurement officers—this trajectory matters because it combines programmatic predictability with episodic volatility. That combination creates differentiated opportunity windows for manufacturers, contract manufacturers, logistics providers, and private–public partnership investors who can align production, pricing and access strategies with MDA cycles and WHO-driven procurement channels.
Drugs for Schistosomiasis Market
Core dynamics shaping 2026 strategic choices
-
Demand stability vs. episodic shocks: Endemic-country programs and donor-funded MDA create a baseline, predictable demand profile. However, geopolitical tensions, export restrictions, and capacity constraints in specialized manufacturing periodically compress supply—generating short-term price and access shocks that can disrupt national elimination campaigns.
-
Product evolution and access policy: The arrival of pediatric dispersible formulations and WHO prequalification of newer treatment variants has shifted procurement preferences in favor of child-friendly therapies, changing tender dynamics and enabling preferential pricing frameworks in many endemic countries.
-
Competitive structure and cost pressure: Off-patent status for core molecules has fostered a robust generic supply base from cost-optimized manufacturers, increasing price competition for large tenders while concentrating premium value on differentiated formulations and supply reliability.
-
Distribution and last-mile requirements: MDA programs rely on a mix of institutional channels—hospital and community health platforms, government procurement routes, and NGO distribution networks—with growing attention to cold chain simplification, dosing accuracy for children, and on-the-ground logistics capacity.
What this means for strategic planning in 2026
-
Manufacturing and capacity decisions: Firms must balance capitalizing on baseline growth with resilience to episodic supply disruptions. Options include selective capacity expansion, dual-sourcing of active pharmaceutical ingredients (APIs), and strategic contract manufacturing partnerships that prioritize regulatory readiness (e.g., WHO prequalification) for high-volume tenders.
-
Portfolio and product strategy: Plain dose competition will intensify. Margin protection will come from pediatric formulations, combination therapies, and value-added services (e.g., packaging for MDA distribution, integrated training materials). Early investment in child-specific formulations and scalable blister/pediatric packaging is likely to accelerate tender share in the 2026–2028 window.
-
Procurement and pricing playbooks: Buyers—governments and donors—are increasingly awarding contracts based on a mix of price, supply assurance, and WHO prequalification status. Suppliers should construct tiered pricing structures that reflect long-term procurement commitments and include volume and delivery guarantees to win multiyear tenders while preserving commercial viability.
-
Partnership and access models: Success will depend on hybrid models combining commercial distribution with NGO and multilateral partnerships. Strategic alliances with program implementers and funders—particularly those focused on pediatric access—can accelerate adoption while sharing implementation risk.
-
M&A and licensing considerations: Given the market’s moderate scale and the concentration of capability in a subset of suppliers, targeted acquisitions or licensing arrangements—especially for pediatric formulations, WHO-prequalified lines, or regional manufacturing footholds—are an efficient route to scale and tender eligibility.
Competitive landscape: capabilities that matter in 2026
The market is anchored by a small group of established manufacturers and a broader field of generics that serve government procurements. Strategic differentiation is not purely about price; it is about supply reliability, regulatory positioning, and formulation innovation.
-
Large innovator and established suppliers: Global players with WHO-prequalified products and partnerships with implementation bodies are positioned to capture premium opportunities tied to pediatric and program-integrated deliveries. Recent distribution and partnership moves that target preschool-aged children reflect a strategic shift toward integrated public-health engagement models.
-
Generic manufacturers in cost-competitive markets: Established producers in India and East Asia have strong cost positions and are primary contenders for large-volume tenders. Patent expiries have enabled wider participation, making procurement dynamics highly price-sensitive for commoditized formulations.
-
Regional and emerging suppliers: Smaller regional players can win on agility, local regulatory knowledge, and faster lead times—but they must demonstrate consistent quality standards and tend to be disadvantaged in large multilateral tenders without prequalification credentials.
Notable recent developments underscore the market’s practical dynamics: targeted delivery of pediatric formulations in field studies, strategic partnerships between suppliers and elimination-focused NGOs, and episodic production discontinuations that require rapid procurement adjustments. These events crystallize the competitive premium on program-aligned supply models and regulatory readiness.
Report contents — what PW Consulting delivers
Our full Drugs for Schistosomiasis Market report goes beyond top-line forecasting to deliver operationally actionable intelligence for 2026 planning cycles. Key inclusions:
- Robust market-sizing and growth scenarios (historical baseline 2020–2025; detailed forecasts through 2032) with sensitivity analysis to key variables such as API cost, tender volumes, and geopolitical disruption intensity.
- Segmentation analysis across product type, distribution channels and end-user cohorts—presented with commercial-grade assumptions and an interactive dashboard that supports “what-if” tender and pricing modeling.
- Supply-chain and manufacturing capacity maps, including concentration risk heatmaps and recommended dual-sourcing strategies to mitigate single-point failures.
- An operational playbook for winning institutional procurement (tender-response checklists, pricing templates, compliance milestones including WHO prequalification pathways).
- Competitive profiles and strategic scorecards for the key incumbents and high-potential entrants, including assessment of R&D pipelines for pediatric and combination therapies, regulatory posture, and historical tender performance.
- Risk register and mitigation matrix covering regulatory changes, logistics interruptions, reputational exposures, and demand variability tied to program funding cycles.
- Investor and M&A guidance: valuation frameworks, target screening criteria, and integration checklists tailored to the sector’s scale and concentration dynamics.
How to use this intelligence in 90–180 day planning
-
90-day tactical moves: Secure contingent API contracts, validate WHO prequalification status for product lines, and structure price-volume commitments for near-term tenders. Initiate conversations with program partners to align clinical acceptability and distribution readiness for pediatric formulations.
-
180-day strategic moves: Commit to capacity investments or contract manufacturing agreements, deploy a segmented pricing strategy for institutional vs. private-channel customers, and finalize at least one collaboration or distribution partnership in an endemic region to establish a procurement track record.
Bottom line for 2026 decision-makers
The schistosomiasis drugs market is not a high-margin blockbuster sector, but it is strategically significant for companies that can combine product reliability, regulatory readiness, and programmatic alignment. The predictable baseline growth—anchored by steady program funding and evolving pediatric needs—creates a durable commercial case for investments that enhance supply resilience and formulation differentiation. Conversely, failure to secure quality-certified capacity or to partner effectively with procurement stakeholders will relegate suppliers to cyclical, price-driven tendering with narrow margins.
PW Consulting’s full market study contains the granular segmentation, tender-level benchmarking, and proprietary scenario outputs required to operationalize these recommendations. For commercial teams, supply-chain leaders, and strategic planners who must present a defensible 2026 plan to boards or donors, the detailed appendices and playbooks in our report are the tools to close the gap between strategy and execution.
Next steps
To access the full dataset, tender-level intelligence, and the executable playbooks referenced here, consult the PW Consulting report page for the Drugs for Schistosomiasis Market. Our team is prepared to run a condensed, client-specific workshop to translate the findings into a 12–24 month action plan tailored to your organization’s role in the value chain.
For detailed analysis of this topic, please visit the official page: Drugs for Schistosomiasis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Telepsychiatry Market to Hit USD 1,917M by 2032 at 19.8% CAGR — PW Consulting
By pmarketresearch, 2026-07-30
Telepsychiatry Market 2026: Strategic Imperatives for Executives — A PW Consulting Preview
As telepsychiatry moves from pandemic-era emergency response to a mainstream care modality, 2026 will be the year organizations translate program pilots into durable clinical, financial, and digital platforms. Our new Telepsychiatry Market study (base year 2025, forecast 2026–2032) quantifies that transition and turns it into actionable priorities for health systems, payers, vendors, and investors. The global market — measured on a consistent USD revenue basis — has grown rapidly from a modest base in 2020 and is projected to expand at a compound annual growth rate of approximately 19.8% through the forecast window. That trajectory reflects accelerating adoption, favorable reimbursement shifts, and measurable operational efficiencies in high-value sites of care.
Telepsychiatry Market
Why this study matters for 2026 decisions
-
Policy and reimbursement are converging to reduce execution risk. Recent federal actions — from extended Medicare telehealth flexibilities through late 2027 to 2026 Medicare fee-schedule refinements that add remote physiologic monitoring and streamline telehealth eligibility reviews — materially change the economics of virtual behavioral health. Executives who do not re-price and re-contract in light of these changes will leave margin on the table.
Telepsychiatry Market -
Regulatory clarity on controlled substance prescribing remains provisional but consequential. The DEA’s extension of tele-prescribing flexibilities through the end of 2026 keeps a high-risk, high-value revenue stream accessible to telepsychiatry providers — but with an expectation of tightened compliance oversight. Operational playbooks must anticipate narrower guardrails by design.
Telepsychiatry Market -
Programs with mature measurement frameworks are demonstrably better investments. Public reports from statewide programs show quantifiable cost avoidance and reduced acute utilization when telepsychiatry is embedded into referral pathways and ED diversion protocols. Those results change valuation metrics for buyers and the ROI thresholds used by CFOs evaluating scale-up investments.
-
Technology and security remain non-negotiable. As platforms handle higher acuity and more integrated data flows, encrypted communications and executed Business Associate Agreements are baseline compliance. Organizations that treat security as a strategic enabler rather than a checkbox are winning enterprise-level contracts.
Market trajectory — what the numbers signal
The telepsychiatry market recorded sustained growth from 2020 through our 2025 base year, reflecting both demand-side expansion in mental health service utilization and supply-side innovations in clinical staffing and virtual care delivery. Under our central forecast, the market continues to scale rapidly through 2032, driven by accelerated adoption across hospitals, outpatient clinics, correctional facilities, schools, and home-based care models. The near-term growth rate and longer-term compounding effects mean that organizations planning capacity, hiring, or M&A in 2026 will be entering a substantially larger market environment than even a year prior — and those plans must be calibrated to multi-year growth rather than short-term trends.
What this study delivers — practical outputs for strategic teams
-
Investment-grade market sizing and scenario models (baseline, upside, downside) tuned to reimbursement and regulatory permutations to support board-level capital allocation.
-
Go-to-market playbooks for health systems, payers, and vendor partners — including contracting approaches, pricing levers, and win themes for enterprise RFPs.
-
Operational blueprints: staffing models for hybrid telepsychiatry teams, scheduling algorithms to optimize provider productivity, and KPI sets that tie clinical outcomes to utilization and revenue impact.
-
Compliance and clinical risk matrices aligned to current prescribing and privacy guidance, with recommended governance checklists for legal and risk teams.
-
M&A and partnership screening tools: candidate attributes, integration playbooks, and earn-out constructs tailored to the telepsychiatry value chain.
-
Vendor evaluation frameworks and a confidential vendor scorecard synthesizing product, clinical depth, integration capability, and commercial traction.
Competitive landscape — how leading providers are positioning
The competitive set is varied: national virtual-first providers, system-facing partners, specialty telepsychiatry networks, and vertically integrated platforms that stitch together therapy, psychiatry, and population health services. Below are strategic profiles and implications for 2026 planning.
-
Array Behavioral Care (Chicago) — Array has built a differentiated model by delivering integrated virtual psychiatry and therapy across diverse settings including hospitals, homes, correctional facilities, and universities. Their multi-site operational experience and on-demand/scheduled service mix make them a preferred partner for institutions needing rapid deployment and closed-loop care coordination. Strategic implication: health systems seeking turnkey, fidelity-assured programs should evaluate Array for partnership or acquisition to shorten time-to-live.
-
Telemynd (Maynard, MA) — Telemynd emphasizes a national network of licensed providers, focusing on scalable online consultations. Their play is volume + provider coverage density, which suits payers and employers looking for broad network access. Strategic implication: payers should test blended reimbursement pilots with network partners that can deliver both urgent access and longitudinal continuity.
-
American Telepsychiatrists (Sacramento) — A specialist in delivering board-certified psychiatrists to underserved populations via telepsychiatry programs. Their core competency is clinical depth in high-need catchments. Strategic implication: community health centers and safety-net systems should consider engagement models that leverage such specialist networks to fill local provider gaps without compromising quality.
-
Iris Telehealth (Austin) — Iris positions itself as a telebehavioral health partner to health systems and clinics across ages and acuity levels. Recent strategic moves include the integration of smaller, system-focused providers to deepen inpatient and specialty program capabilities. Strategic implication: health systems evaluating in-house versus outsourced builds will find Iris’s integration experience relevant to minimizing operational disruption.
-
MDLIVE (Miramar) — A national telehealth stalwart offering 24/7 mental health and behavioral health services via a broad clinician network. Their strength is continuous access and consumer-facing distribution channels. Strategic implication: employers and retail health participants should align with platforms like MDLIVE to scale benefit designs and on-demand offerings.
-
innoVA TEL — Historically focused on integrating telepsychiatry into health system programs; recent consolidation into larger system-facing platforms illustrates the current consolidation dynamic where domain specialists are folded into scale partners. Strategic implication: potential targets for strategic acquisition will often be chosen for integration speed and clinical protocol portability rather than brand equity alone.
Dynamic forces shaping winners and losers in 2026
-
Reimbursement rules and coding changes are the primary commercial accelerant. Organizations that align contracting, billing workflows, and provider compensation with the updated Medicare and state-level rules will convert capacity into realized revenue faster.
-
Workforce economics — specifically access to board-certified psychiatrists and the ability to scale mid-level clinicians under appropriate supervision — will determine margin outcomes. Platforms that optimize clinician utilization via scheduling algorithms and cross-coverage models will achieve structural cost advantages.
-
Site-of-care expansion is a differentiator. Programs that credibly operate across emergency departments, inpatient consult services, correctional facilities, and home-based care create defensible value propositions because they substitute high-cost utilization and embed into referral flows.
-
Compliance and digital trust are table stakes. Beyond HIPAA-aligned encryption and Business Associate Agreements, organizations must be ready for increased audit rigor linked to tele-prescribing and care continuity for controlled substances.
Recommended executive plays for 2026
-
Execute focused capacity investments: prioritize specialties and sites with demonstrable ROI (e.g., ED diversion, population-health case management) and staff these programs with mixed-license clinician teams.
-
Refresh contracting and payer negotiations to reflect CMS code changes and state-level reimbursement updates; build starter pilots that can convert to value-based arrangements within 12–18 months.
-
Accelerate vendor consolidation where operational scale matters, but retain niche partnerships for high-acuity or underserved segments. Use M&A selectively to acquire access to provider panels and clinical protocols rather than commoditized tech.
-
Institutionalize measurement and outcomes: link clinical outcomes to utilization and financial KPIs and publish program-level results internally to inform resource allocation.
-
Strengthen compliance infrastructure to anticipate tighter scrutiny of tele-prescribing and privacy safeguards; make updated governance a precondition for any vendor or partnership approval.
What we intentionally withhold here — and where to find it
This preview highlights the strategic direction and tactical levers that will matter in 2026. To preserve the actionable edge for subscribing decision-makers, detailed segment tables, regional and service-type revenue splits, pricing benchmarks, vendor scorecards with quartile rankings, and downloadable financial models are available in the full PW Consulting Telepsychiatry Market report and data pack. Those materials provide the granular inputs your finance, strategy, and operations teams need to build executable plans and board-ready investment cases.
For executives preparing 2026 strategic plans, the choice is clear: act now to reshape care pathways, capture newly accessible reimbursement, and lock in partnership architectures that deliver scale and clinical quality. Our full study provides the roadmaps, models, and vendor intelligence required to make those decisions with conviction.
For detailed analysis of this topic, please visit the official page: Telepsychiatry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Thermoplastic Polyamide Market Set for 5.85% CAGR (2026–2032)
By pmarketresearch, 2026-07-30
Thermoplastic Polyamide Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest Thermoplastic Polyamide Market study (base year 2025, forecast 2026–2032) provides a pragmatic, decision-focused roadmap for executives and strategy teams navigating the next phase of value creation in polyamide-based engineering polymers. The market, measured in USD Million, has expanded from a post‑pandemic base and reached roughly 2,215 USD Million in 2025. Under our central scenario—reflecting material substitution trends, regulatory shifts, and feedstock price dynamics—the market is expected to grow at a compound annual growth rate (CAGR) of 5.85% through 2032, reaching an estimated 3,290 USD Million by the end of the forecast horizon. Early 2026 figures point to a near-term market value of about 2,386 USD Million, underlining momentum entering the new planning cycle.
Thermoplastic Polyamide Market
Why this research matters for 2026 corporate decision-making
- Priority setting under uncertainty: 2026 is a year when many OEMs, compounders, and chemical majors will rebase their capital allocation and procurement plans. Our study translates market growth and volatility drivers into a prioritized set of investment and sourcing options.
- Supply‑chain resilience: Volatility in caprolactam and PA feedstocks has resumed. Executives need clear stress-tests and hedging strategies; the report maps supplier concentration, logistics chokepoints, and tariff exposures that materially affect margins.
- Regulatory and standards readiness: New tariff listings and emerging product standards are changing cost and compliance equations—this study decodes regulatory impacts and indicates where compliance spend becomes strategic rather than merely defensive.
- Commercial differentiation: As demand expands, winners will be those who convert technical capabilities (e.g., specialty PA12, bio‑circular PA11) into sustainable value propositions. The study identifies premium pockets and the commercial plays to capture them.
What the report delivers — practical components for action
- Robust historic and forecast market sizing (2020–2032) with scenario variants that reflect feedstock shocks, regulatory shifts, and accelerated electrification of mobility.
- Demand-driver analytics: material substitution matrices, use‑case adoption curves, and end‑market sensitivity to cost and regulatory changes.
- Supply‑side mapping and competitive benchmarking: production capacities, regional footprint analysis, technology differentiation, and an up‑to‑date roll of key producers and compounders.
- Raw‑material and price‑pass‑through modelling, including caprolactam and upstream petrochemical sensitivities, plus stress‑test outputs for procurement teams.
- Regulatory and standards impact assessment that quantifies the near‑term commercial implications of tariff reclassification and ISO updates.
- Commercial playbooks and go‑to‑market frameworks: win‑loss archetypes, pricing tactics, and partner ecosystem strategies for rapid market entry or share defense.
- Opportunity heatmaps and M&A scorecards: where to deploy capital for capacity rollouts, technology bolt‑ons, or tuck‑in acquisitions to capture premium margins.
- Primary research appendices: supplier interviews, plant‑level intelligence, and proprietary transaction comparables to support diligence.
Market dynamics shaping 2026 strategy
The outlook for thermoplastic polyamides this year is being rewritten by a confluence of demand-side transformation and supply-side constraints. Mobility electrification, continued emphasis on component lightweighting, growth in medical device applications, and the packaging sector’s selective move toward higher‑performance polymers are all expanding the addressable market. At the same time, raw material volatility is back on the agenda: caprolactam bid tones climbed meaningfully in late January 2026 amid continued volatility in feedstock prices, underscoring the sensitivity of PA6 value chains to crude‑oil swings and concentrated APAC supply dynamics.
Thermoplastic Polyamide Market
Regulatory changes are also material. In 2026 the U.S. Customs and Border Protection updated the Harmonized Tariff Schedule to clarify the classification of several polyamide grades, creating new tariff and documentation implications for cross‑border flows. Concurrently, ISO 21036:2025 now governs plastics piping systems for PA12 line pipe, raising compliance thresholds for producers and installers in infrastructure markets. These two changes alter cost structures and route‑to‑market decisions for manufacturers and downstream integrators alike.
Thermoplastic Polyamide Market
Competitive landscape — players, moves, and strategic implications
The market exhibits moderate concentration: leading multi‑national producers capture a meaningful share of high‑performance grades, while a broad base of regional compounders serves application‑specific needs. Strategic implications for incumbents and challengers include the need to balance scale benefits with technical differentiation and sustainability credentials.
- BASF SE (Ludwigshafen, Germany): A technology leader with a broad range of thermoplastic polyamide grades, including PA66, PA6, and copolymers for engineering applications. Recent product activity—such as a 2025 launch of a thermoplastic polyamide with high water permeability and collaborations on specialty consumer products—signals an R&D push into application‑led differentiation.
- Evonik Industries AG (Essen, Germany): Focused strength in PA12 and related resins, with established positions in automotive, sports, and oil & gas components. Evonik’s portfolio is aligned with safety‑critical and performance‑sensitive applications where premium pricing persists.
- Arkema S.A. (Colombes, France): Supplier of Nylon 12 resins and bio‑circular PA11, positioning itself at the intersection of performance and sustainability—an increasingly salient commercial axis for OEM procurement teams.
- Ascend Performance Materials LLC (Charlotte, USA): One of the largest vertically integrated PA66 producers, with capabilities in flame‑retardant chemistries for electrical and automotive markets; scale and integration remain its chief competitive levers.
- UBE Industries, Ltd. (Tokyo, Japan): Offers a suite of nylon polymers for fibers, industrial yarns, and engineering plastics; valuable for regional supply security and specialty grades.
These manufacturers’ 2024–2026 product and partnership moves indicate dual strategies: (a) defend core volume streams through integration and cost control; and (b) capture margin upside through differentiated, high‑performance and sustainability‑oriented grades. For potential entrants or investors, mid‑sized compounders that can combine nimble application development with selective upstream integration look especially attractive.
Implications for sourcing, product, and M&A strategy
For procurement leaders, the near term requires a two‑track approach: tactical hedges to manage immediate caprolactam price oscillations and strategic diversification of feedstock sourcing to mitigate regional concentration risk. Manufacturers should prioritize contractual flexibility (indexation, formula pricing) and re‑examine inventory policies against the cost of disruption.
Product teams should accelerate the commercialisation of bio‑circular and specialty PA grades that address OEM sustainability mandates while commanding premium pricing. Standards such as ISO 21036:2025 will create entry barriers for non‑compliant suppliers; early certification and targeted partnerships with downstream integrators can convert compliance into a competitive advantage.
For corporate development, the market’s growth profile and moderate concentration support both bolt‑on acquisitions (to acquire niche grades, customer access, or regional plants) and greenfield investments where long‑lead capacity can secure advantaged positions in growing end‑markets. The report’s M&A scorecard outlines target characteristics and valuation sensitivities under different scenarios.
Actionable frameworks included
- 3‑Step Investment Filter: Economic defensibility (margin under stress), strategic fit (channel & tech), and execution risk (capex & permitting timelines).
- Supplier Resilience Matrix: A diagnostic for ranking suppliers on feedstock exposure, logistic risk, and contractual flexibility.
- Go‑to‑Market Playbook: Tactical moves for launching specialty grades—pricing, channel selection, and co‑development models with OEMs.
How to use this study in 2026 planning cycles
Strategy teams should integrate the study’s scenarios into their 2026 planning cycle in four places: (1) capital allocation reviews—budget potential capacity and upgrades against forecasted price and demand scenarios; (2) procurement negotiations—use the raw‑material modelling to renegotiate terms and secure contingency capacity; (3) product roadmaps—prioritise development of PA grades that align with regulatory and sustainability signals; and (4) M&A pipeline prioritisation—rank targets using the report’s value creation templates.
Importantly, while this overview synthesizes the market’s trajectory and strategic levers, the full intelligence—including granular regional flows, application heatmaps, supplier scorecards, and downloadable modelling tools—is available in the complete PW Consulting report for teams preparing high‑stakes decisions in 2026.
Conclusion
The thermoplastic polyamide market is entering a phase where aggregate growth (CAGR ~5.85% to 2032) coexists with renewed feedstock volatility and tightening regulatory demands. That combination favors players who can marry technical differentiation and sustainability credentials with rigorous supply‑chain resilience. PW Consulting’s Thermoplastic Polyamide Market study equips leadership teams with the scenarios, financial sensitivities, and commercial playbooks required to convert the 2026 inflection into sustainable advantage.
For organisations that must translate these strategic insights into executable plans—procurement hedges, product investments, or acquisition screening—the full report contains the empirical detail and modelling tools necessary to underwrite decisions. Contact the PW Consulting research desk to access the complete dataset, forecast models, and custom advisory offerings that support rapid implementation.
For detailed analysis of this topic, please visit the official page: Thermoplastic Polyamide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Robotics Market to Grow from USD 100M (2025) to USD 157M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-30
Robotics Market 2026: Strategic Imperatives for Executive Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, high-impact preview of our full Robotics Market research — the essential briefing for executives who must decide where to allocate capital, prioritize pilots, and shape supply-chain resilience through 2026 and beyond. This introduction demonstrates the analytical depth and practical orientation of the full study while preserving the proprietary granularity that motivates a deeper read.
Robotics Market
Why this study matters in 2026
Robotics is no longer a niche engineering discussion: it is a strategic lever for productivity, resilience, and new service models across manufacturing, logistics, healthcare, and consumer applications. Our research uses 2025 as the base year and projects a steady, compounding expansion of the market through 2032, driven by accelerating automation adoption, modular robotic architectures, and improved software intelligence. The market’s projected compound annual growth rate (CAGR) of 6.98% underpins a meaningful growth trajectory that executives need to internalize when setting three- to five-year plans.
Robotics Market
For corporate leaders making 2026 decisions, this study converts macro momentum into operational choices: where to pilot, what partner models to prefer, which sourcing risks to hedge, and how to quantify the total cost of ownership for robotics investments. We frame these choices with scenario-based risk assessments that reflect near-term policy shocks, raw-material constraints, and ongoing unit-cost deflation trends that have reshaped robotics economics over recent decades.
Robotics Market
Market trajectory: a pragmatic view
Using historical observations (2020–2025) and forward-looking modeling (2026–2032), PW Consulting’s forecast balances adoption curves, component supply dynamics, and shifts in labor economics. The report anchors to a widely understood base year and shows how steady growth compounds across the forecast window — demonstrating both the size of the opportunity and the pace at which competitive positions will consolidate. We also quantify concentration at the supplier level, showing a market where leading firms command material but not absolute dominance, creating fertile ground for both incumbents and challengers.
Key dynamics shaping strategy
-
Regulatory and geopolitical pressure: New export controls and national security reviews are reshaping where key components and subsystems can be sourced and how supply chains are architected. Firms must design procurement and inventory strategies that anticipate sudden shifts in export policy and import-restriction regimes.
-
Component and raw-material volatility: The supply of specialty materials and battery-related technologies has become a strategic variable. Engineering teams and procurement functions should adopt dual-sourcing and modular design principles to reduce single-point exposures.
-
Unit-cost deflation and modularization: Long-run declines in average unit prices — driven by production scale, modular designs, and software-enabled capabilities — expand addressable use cases. Your ROI thresholds and payback models should be recalibrated to reflect shorter deployment horizons and faster capability turnover.
-
Labor dynamics and value migration: Rising labor costs and chronic skills shortages in many developed markets continue to accelerate robotics adoption. The strategic lens shifts from cost-replacement to capability augmentation — redefining job roles, training pipelines, and human-robot interaction standards.
-
Standards and certification: Convergence on industrial and safety standards has lowered barriers for integrators and promoted interoperability — but certification milestones also create competitive gatekeepers. Practical compliance playbooks are needed to move pilots to scale with minimal rework.
What the full report delivers (operational, decision-ready content)
Our full Robotics Market report translates the macro narrative into practical tools for executives, investors, and product leaders. Core deliverables include:
-
Market sizing and validated forecasts — model-driven projections from 2026 through 2032, with sensitivity bands that reflect policy shocks and supply-chain scenarios.
-
Adoption playbooks — sector-specific templates for pilot design, performance metrics, and scaling thresholds, enabling rapid move-from-prototype to profitable deployment.
-
Total cost of ownership (TCO) models — leveled cost frameworks that fold in CapEx, integration, downtime risk, upgrade cycles, and workforce transition costs, with plug-and-play inputs for company-level customization.
-
Vendor due diligence and partner maps — structured assessment criteria for selecting OEMs, integrators, and software providers, supported by comparative profiles and deal playbooks.
-
M&A and investment diagnostic — valuation levers, synergies playbooks, and red-flag indicators tailored to robotics startups and adjacent technology bets.
-
Regulatory & compliance tracker — a living appendix of recent and pending regulatory actions that materially affect cross-border sourcing, import/export, and certification pathways.
Competitive landscape: who matters and why
The market is shaped by a mix of established industrial OEMs, specialized cobot vendors, and a growing cohort of mobile and humanoid robotics innovators. The competitive concentration underscores meaningful leadership by a handful of firms while leaving room for differentiated entrants focusing on software, integration, or niche use cases.
-
ABB Ltd. (Zurich): Strengths lie in modular industrial and collaborative systems and deep enterprise integration experience. ABB is a logical partner for large-scale factory modernization where modularity and standardized control architectures matter.
-
Fanuc Corporation (Japan): Known for high-precision industrial robots and CNC systems, Fanuc remains a go-to supplier for high-throughput automotive and electronics lines where deterministic performance is essential.
-
KUKA AG (Germany): KUKA’s advanced robotic platforms and end-to-end production solutions make it a strategic match for vehicle manufacturers and complex assembly environments seeking integrated automation roadmaps.
-
Yaskawa Electric (Japan): With a broad portfolio spanning SCARA to collaborative robots and increasing AI integration, Yaskawa is well-positioned in mixed-technology factory ecosystems.
-
Universal Robots (Denmark): As a pioneer of cobots, Universal Robots continues to lower adoption friction for human-robot collaboration in small and mid-sized enterprises where safety and ease-of-programming unlock ROI.
-
Mitsubishi Electric & Epson Robots (Japan): Both bring strengths in precision manufacturing use cases, with Epson leading in compact high-speed applications and Mitsubishi in system-level automation.
-
Kawasaki Heavy Industries (Japan): A trusted provider of robotic arms and automation systems for traditional industrial environments, with a long track record in heavy-duty use cases.
-
Innovators & challengers (U.S. entrants): Firms such as Agility Robotics, Serve Robotics, Boston Dynamics, and Simbe Robotics exemplify how mobility, autonomy, and specialized sensing are expanding robotics beyond the factory floor into logistics, delivery, retail, and dynamic industrial tasks.
Our competitive mapping in the full report includes strategic positioning matrices, go-to-market archetypes, partnership network overlays, and M&A activity heatmaps — all calibrated to help acquirers, partners, and procurement teams make evidence-based choices.
Recent developments you cannot ignore
-
Industry datasets report continued deployment momentum of industrial robots globally, reinforcing the case for capital investment in robotics-enabled modernization at scale.
-
Major industry events and trade shows in 2026 highlighted rapid advances in humanoid robotics and AI-driven autonomy — signaling that software and perception stacks are now central to commercial differentiation.
-
Notable commercial milestones — from strategic partnerships enabling autonomous delivery to safety certifications for retail robotics — illustrate the fast pace at which pilot projects are crossing into regulated, revenue-generating deployments.
-
Policy moves on export controls and national security investigations have already shifted supplier discussions and compelled executives to run contingency scenarios for critical components and subsystems.
How leaders should act in 2026
-
Prioritize modular pilots: Start with modular, interoperable systems that allow you to iterate quickly and redeploy capacity as needs evolve.
-
Adopt a supply-chain war room: Maintain rolling risk assessments for component sourcing, regulatory exposures, and alternate suppliers.
-
Invest in integration capabilities: The long-term value accrues to organizations that combine system engineering with operations and software lifecycle management.
-
Use standards to accelerate scale: Certification and adherence to emerging safety standards materially reduce deployment friction in regulated environments; include compliance costs in your ROI models from day one.
-
Scan for strategic partnerships: Co-invest with software firms, system integrators, or niche hardware specialists to de-risk innovation and shorten time to value.
Next step: what the full PW Consulting report provides that this preview does not
This briefing intentionally highlights the strategic contours and actionable recommendations you need in 2026 while withholding the proprietary segment-level allocations and granular vendor scoring that make the full report indispensable for transaction teams and deployment planners. The full study contains detailed, downloadable tables, segment-specific scenario outcomes, contract negotiation playbooks, and customizable financial models aligned to your use-case mix.
For decision-makers preparing capital plans, procurement strategies, or M&A activity in 2026, PW Consulting’s Robotics Market report transforms broad trends into executable strategies. Access the comprehensive intelligence hub to view the full segmentation, vendor scorecards, and exportable TCO workbooks that senior teams use to finalize budgets and board-level recommendations.
For detailed analysis of this topic, please visit the official page: Robotics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com