

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Locker Locks Market Poised for 5.0% CAGR from 2026–2032

Locker Locks Market: Strategic Insights for 2026 Decision-Making
Executive snapshot
As organizations recalibrate physical-security investments in a post-pandemic, data-conscious world, the global locker locks market stands at a meaningful inflection. Our analysis uses 2025 as the base year, traces developments since 2020, and projects through 2032. The market—which expanded from a clear five-year historical base—registered measured growth to approximately USD 125 million in 2025 and is expected to continue on a steady trajectory (approximate CAGR 5.0% over the forecast window). Concentration remains material: the top three vendors account for roughly 70% of revenue, and the top five capture about 85%, underscoring a market where scale, channel reach and product breadth matter for sustained leadership.
Locker Locks Market
Why this research matters for 2026 decision cycles
- Timing: 2026 is the first full planning year following several product refreshes from major OEMs and a fresh wave of regulatory clarifications affecting electronic access systems. Tactical choices made this year—on product roadmaps, OEM partnerships, and procurement standards—will govern multi-year market share outcomes.
- Risk management: New privacy and safety requirements (notably GDPR-driven audit-trail expectations, CE marking regimes in the EU, and U.S. workplace safety rules relating to lockout/tagout) mean that product compliance, data architecture and after-sales processes are now strategic risk vectors rather than checkbox items.
- Return optimization: With a steady mid-single-digit CAGR anticipated, volume alone will not deliver outsize returns. Winning players will differentiate through adjacent services, platform integrations and channel economics.
Market trajectory and structural signals
The market’s historical performance from 2020 through 2025 shows a stable expansion path, and our forecast through 2032 projects continued single-digit growth moderated by periodic product refreshes and adoption cycles of smarter, networked solutions. That pattern reflects two interacting dynamics: first, mature replacement and retrofit cycles in institutional and corporate environments; second, incremental new demand driven by digital access requirements, hospitality and multi-family housing conversions.
Locker Locks Market
Important structural characteristics include:
- Relatively high market concentration—indicating scale advantages in manufacturing, distribution and brand-driven procurement.
- Product diversification across mechanical, electronic and hybrid systems—where different value propositions (cost, convenience, compliance) map to different buyer segments and procurement levers.
- Emerging cost complexities for networked systems—install-time cabling (PoE) versus battery-powered wireless solutions meaningfully changes total installed cost and upgrade pathways.
Drivers, constraints and regulatory overhangs
Demand drivers are a combination of secular and tactical factors: workplace reopenings and reconfigurations, multi-family property upgrades, locker-as-a-service deployments in shared-economy venues, and institutional investments in asset security. On the technology front, the adoption of Bluetooth, NFC and cloud-managed locker management platforms is accelerating, but buyers remain sensitive to life-cycle cost, interoperability and data-security assurances.
Two regulatory/standards developments deserve special attention for 2026 planning:
- Data privacy and audit trails: Enforcement and buyer expectations stemming from GDPR-like regimes are raising the bar for encrypted logs and proof-of-access. For vendors, this transforms software modules and firmware architecture from differentiation points into table stakes.
- Safety and access control standards: OSHA-style lockout/tagout requirements and CE conformity frameworks are tightening acceptance windows for new products in certain geographies. Compliance timelines and third-party testing windows must be integrated into product launch plans.
Competitive landscape — what to watch
The competitive map is balanced between long-established mechanical specialists and more recent electronic/smart entrants. Notable companies shaping market dynamics include:
- Master Lock Company (United States) — a legacy brand with broad commercial and consumer offerings, increasingly active in smart commercial locks and partnerships targeting multi-family and SMB segments.
- Abloy Oy (Finland) — recognized for high-security mechanical and hybrid electronic locking solutions, often positioned in high-assurance institutional installations.
- Codelocks (United Kingdom) — a fast-moving innovator in compact digital and kit-lock systems; recent launches broaden their addressable installations and suggest an aggressive mid-market push.
- Lowe & Fletcher, Digilock, EMKA, Hettich and Häfele — firms with strong OEM or distribution capabilities, supplying integrated furniture, cabinet and locker-specific hardware solutions.
- Allegion, Ojmar, LockeyUSA, Zephyr Lock — established access-control players increasingly layering smart features or distribution partnerships to defend installed bases.
- China-based suppliers (e.g., Be-Tech, MAKE, Ningbo Wangtong) — competitive on cost and feature-rich electronic options; critical as contract manufacturing and OEM-sourced components become more prominent in procurement decisions.
Recent product activity—multiple launches from both traditional names and newer entrants—indicates the market is in a phase of feature consolidation (miniaturization, dual-function locks, stronger enclosures) and platform evolution (integration with building management and locker-management SaaS). This intensifies competition on product roadmap, channel partner coverage and software ecosystems rather than on purely hardware price.
Strategic implications and recommended actions for 2026
For incumbent suppliers, challengers and buyers, the following decision levers will materially influence outcomes in 2026 and beyond:
- Portfolio strategy: Prioritize modular architectures that allow mechanical lockbacks and electronic upgrades without full cabinet replacement. This minimizes customer friction in upgrade cycles and protects installed-base value.
- Compliance-first product development: Embed encryption, audit trails and third-party certification plans into R&D roadmaps. Non-compliant launches risk procurement delays and contract penalties in regulated environments.
- Channel and service economics: Reconfigure go-to-market to favor value-added installers and systems integrators that can deliver turn-key locker systems—bundling hardware, cabling decisions (PoE vs. battery) and software subscription offerings.
- M&A and partnerships: Use M&A to close capability gaps—software platforms, secure cloud services, or regional distribution. For larger incumbents seeking growth, bolt-on acquisitions of niche smart-lock vendors or SaaS locker-management firms can accelerate access to recurring revenue models.
- Supply-chain resilience: Hedge component concentration, especially for electronics and battery modules. Consider dual-sourcing for critical subassemblies and negotiating long-lead commitments tied to compliance documentation.
- Pricing and TCO selling: Shift purchasing conversations to total-cost-of-ownership narratives that account for installation labor, cabling, firmware updates and data-compliance costs—this preserves margins on higher-value, integrated offerings.
What our full report delivers — practical, execution-ready content
This research is deliberately structured to be operational for 2026 planners. Highlights include:
- Quantitative market sizing and a transparent forecast model (2026–2032) built on validated install-base and replacement-rate assumptions.
- Scenario analyses mapping regulatory and technology adoption variants to revenue and margin outcomes—enabling contingency planning.
- Channel economics and buyer persona matrices that convert macro trends into procurement playbooks for sales, product management and M&A teams.
- Vendor scorecards and comparative capability maps that evaluate product breadth, compliance readiness and software ecosystems—designed to support short-listing and supplier negotiations.
- Implementation toolkits: sample RFP clauses for encrypted audit-trails and safety compliance, installation cost worksheets contrasting PoE vs. battery-powered architectures, and a checklist for field retrofits to minimize downtime.
Data integrity, methodology and what we intentionally withhold
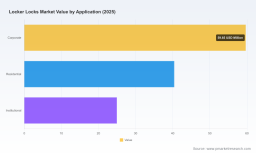
Our base year is 2025; the historical window spans 2020–2025 and the forecast horizon is 2026–2032. We triangulated primary interviews, OEM public disclosures, installer surveys and transactional pricing data to arrive at the market model. To preserve the report’s commercial value and adhere to a “teaser” approach, this introduction omits the granular regional and application splits and specific segment revenue figures that are included only in the full report. The detailed segmentation, supplier share matrices (down to five-player concentration by subsegment), and the underlying model spreadsheets are accessible via the source download.
Quick read on near-term signals to act on in 2026
- Prioritize product launches that combine strong physical robustness with encrypted software logs—these will cross the compliance bar faster and shorten sales cycles.
- If you are a buyer, insist on testable audit trails and a documented CE/GDPR/OSHA compliance matrix during RFP evaluation to avoid post-deployment surprises.
- If you are a vendor, accelerate partnerships with locker-management SaaS providers or certify your APIs to be integrable with leading building-management platforms—this unlocks higher-margin recurring revenue.
- Evaluate aftermarket service and retrofit offers as a defensive play to monetize the large installed base while slowing customer churn.
Closing—how PW Consulting can accelerate your 2026 roadmap
Our Locker Locks Market study is designed to translate market metrics into executable choices. Whether your priority is defending share, entering new geographies, or building a software-enabled recurring business, the report supplies the data, competitive context and procurement instruments to reduce execution risk. For procurement teams, product executives, M&A sponsors and channel strategists, 2026 is a planning inflection: the decisions made now will determine who captures disproportionately more of the modest-but-stable growth that the market offers.
To access the full dataset, segmentation breakdowns, vendor scorecards and the forecast model, consult the PW Consulting report landing page (full access available for licensed clients). Our team is available for tailored briefings and to run custom scenario models aligned with your product and go-to-market priorities.
For detailed analysis of this topic, please visit the official page: Locker Locks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com