

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Workshoes Market to Reach USD 344.8M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-30
Workshoes Market 2026: Strategic Imperatives from PW Consulting’s New Market Study
As companies plan capital allocation, product roadmaps, and go‑to‑market moves for 2026, the Workshoes Market presents a profile that is simultaneously attractive and nuanced. Our latest PW Consulting market study — built on a five‑year historical series (2020–2025) with a base year of 2025 and a forward forecast to 2032 — quantifies a steady expansion pathway: the global market grew from the low‑hundreds of USD Million in 2020 to an estimated USD 215.0 Million in 2025, and it is forecast to continue expanding through 2032 at a compound annual growth rate (CAGR) of 6.98%, reaching roughly USD 345 Million by the end of the forecast horizon.
Workshoes Market
Why this matters for 2026 corporate decision cycles
-
Predictable, mid‑single‑digit growth with upside for premiumization: A near‑7% CAGR makes the sector an appealing target for investment that seeks reliable volume expansion while still leaving room for margin improvement through premium product introductions and value‑added services.
Workshoes Market -
Fragmented competitive landscape: The market remains relatively unconsolidated, with the top players occupying only a modest share of total demand. This fragmentation creates room for targeted M&A, strategic alliances, and differentiated brand plays.
Workshoes Market -
Regulation and standards are a driver and a de‑risker: The revision of safety footwear standards and the codification of test requirements (including updated compression, impact, and electrical hazard tests effective in 2026) shift the basis of competition toward compliance capability and documented performance.
-
Input cost volatility and material innovation shape margin trajectories: Leather, polymers, and advanced composite materials are driving input cost fluctuations; at the same time, higher‑cost composite toe technologies (material cost premiums that can exceed steel alternatives) create product differentiation opportunities for targeted end‑users.
What PW Consulting’s study delivers — the practical toolkit
-
Strategic playbooks: Scenario‑based action plans for manufacturers, retailers, and institutional buyers focused on 12–36 month horizons (pricing responses, inventory hedging, sourcing diversification).
-
Regulatory impact assessment: Clear implications of the ASTM F2413 updates and related testing expectations, including recommended lab investments and compliance timelines for market entry in key jurisdictions.
-
Go‑to‑market playbooks: Channel strategies for balancing direct‑to‑worker, retail partnerships, and private‑label agreements (including frameworks for negotiating retailer SKUs, co‑branding, and licensing deals).
-
Cost and margin stress tests: Sensitivity analyses that map raw‑material price scenarios to product SKU profitability and identify which design choices (steel vs. composite toe; polymer vs. leather uppers) meaningfully change margin ladders.
-
Technology and product roadmaps: Prioritized R&D themes (waterproofing membranes, lightweight composites, slip‑resistant sole compounds) with estimated time‑to‑market and investment ranges.
-
M&A and partnership diagnostics: Target profiles and integration checklists for acquiring scale or capability in manufacturing, certification lab ownership, and distribution reach.
Competitive landscape — strategic takeaways on core players
The industry is characterized by distinct clusters of competitors: legacy North American manufacturers focused on “Made‑in‑USA” provenance and premium construction; Asian producers emphasizing cost‑efficiency and scale; European firms advancing high‑performance materials and testing; and non‑traditional entrants partnering on licensed footwear lines for mass retail. Key dynamics for 2026 decisions include:
-
Legacy US manufacturers (e.g., Red Wing, Thorogood, Belleville, Carolina, Double H, Danner, Chippewa, Wolverine, Rocky Brands): These incumbents benefit from deep brand equity, union/made‑in‑country narratives, and established relationships with industrial buyers. Their strategic advantages in premium segments include superior fit, materials provenance, and compliance track records. For these players, the near‑term playbook should focus on defensible premiumization, selective SKU rationalization to improve margins, and investment in rapid certification pathways to meet the 2026 standard changes.
-
Comfort and lifestyle‑oriented work lines (e.g., Keen Utility): Winning share through comfort engineering and lightweight safety solutions is a viable route for capturing end‑users who prioritize wearability over price. Partnerships with occupational health teams and ergonomic trials become high‑ROI investments.
-
Asia‑based manufacturers (e.g., Dursafety, Xiamen WorkWay, Safetoe): Their strength lies in cost‑competitive manufacturing, rapid scale, and component innovation (composite toes, chemical resistance). For decision makers, these suppliers are flexible partners for private label and retail partnerships but require rigorous quality and compliance audits to satisfy evolving ASTM requirements.
-
European safety specialists (e.g., uvex safety group, Delta Plus): These firms lead on materials science (polymer compounds, nitrile chemistry) and high‑temperature/chemical resistance applications. Recent trade show activity underscores their commitment to product innovation and visibility in professional safety channels. European technology can be an attractive acquisition or licensing target for companies seeking differentiated premium offerings.
-
Retail and licensing entrants (e.g., Bobcat Company collaboration via national retail partners): Strategic alliances with mass‑market retailers create rapid national reach and scale. Such moves alter channel economics and compress price tiers; incumbents must weigh direct retail access against brand dilution risks.
Recent industry signals that should influence 2026 actions
-
Standards tightening: The updated ASTM F2413 revisions raise the bar for compression and impact tests and add electrical hazard considerations effective in 2026, formalizing what product teams must deliver. Firms that build testing and certification capabilities ahead of peers will face lower time‑to‑market friction and reduced recall risk.
-
Trade show & visibility moves: European players showcased advanced welder and foundry boots at major fairs in late 2025, signaling product segments where professional end‑users will accept premium pricing for demonstrable performance.
-
Retail partnerships accelerating distribution shift: New licensed collections launched through big‑box retail in 2026 indicate an acceleration of private‑label and licensed branding strategies to capture utility‑oriented shopper segments.
-
Input cost and design tradeoffs: Volatility in leather and polymer markets, and material differentials for composite toe constructions, are forcing companies to redesign SKU portfolios and reprice. Our modeling shows composite toe solutions can increase unit material cost substantially versus steel alternatives — a direct lever for product segmentation strategies.
Recommended 2026 strategic playbook (prioritized)
-
Invest in compliance infrastructure now. Prioritize lab partnerships or in‑house testing capacity for ASTM F2413 to avoid downstream bottlenecks as procurement cycles tighten.
-
Adopt a dual‑track SKU strategy. Maintain a premium, highly certified line for institutional buyers and a cost‑engineered range for retail/private label — each with separate sourcing and inventory policies.
-
Hedge raw material exposure. Lock multi‑tiered supply agreements and explore strategic inventory captures for leather and key polymers while piloting alternative materials that preserve safety credentials.
-
Pursue targeted bolt‑on M&A. Prioritize acquisition targets that add certification credentials, specialized materials know‑how, or established distribution partnerships to accelerate scale.
-
Monetize fit and lifecycle services. Integrate digital sizing, fit analytics, and accelerated replacement cycles into commercial offers for large accounts — a proven route to raise lifetime value and create switching costs.
-
Champion sustainability narratives where feasible. Lifecycle cost comparisons and reduced waste messaging resonate with procurement teams and can justify modest price premiums.
KPIs to monitor in 2026
-
Time to certification for new SKUs (days from design freeze to certified product).
-
Input cost variance vs. budget (quarterly leather and polymer indices).
-
Channel margin delta (direct vs. retail/private label).
-
Replacement frequency and lifetime cost of ownership for institutional buyers.
-
Share of revenue from premium certified SKUs vs. cost‑engineered SKUs.
Final counsel
The Workshoes Market in 2026 is a market of two simultaneous truths: structurally durable growth with predictable demand, and rising technical/regulatory complexity that rewards those who invest early in compliance, materials, and trusted distribution. The competitive map is wide open for targeted consolidation, technology licensing, and channel innovation. Companies that build certification and testing capability, hedge input risks, and segment their product and distribution strategies will be best positioned to harvest the ~7% CAGR and capture premium margins.
PW Consulting’s full Workshoes Market report provides the granular dashboards, scenario models, and playbooks that operational leaders and investors will need to quantify tradeoffs and execute in 2026. For the detailed segmentation matrices, company scorecards, and our proprietary cost‑to‑produce models — which we have deliberately withheld here to preserve the strategic value of the full study — please consult the full report.
For detailed analysis of this topic, please visit the official page: Workshoes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Metal Cutting Tools Market to Reach USD 119,133 Million by 2032 at 5.82% CAGR
By pmarketresearch, 2026-07-30
Metal Cutting Tools Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a forward-looking synthesis designed to equip executives, investors, and operational leaders with the strategic context they need entering 2026. Our latest Metal Cutting Tools Market study combines robust macro forecasting with operational playbooks and competitive diagnostics to support high-stakes decisions across supply chain design, product investment, pricing, and M&A. This introduction highlights the report’s strategic value, the dynamics shaping the sector, and the implication set we believe will matter most next year — while intentionally reserving the full, granular splits and proprietary scoring matrices for the full report available on our website.
Metal Cutting Tools Market
Market Snapshot: Size, Trajectory, and Concentration
The metal cutting tools market has transitioned from steady recovery to a structurally stronger growth path. Using 2025 as the base year, our top-line forecast shows the market growing at a compound annual growth rate (CAGR) of approximately 5.82% across the 2026–2032 horizon. That trajectory reflects a continuation of recovery that began in the early 2020s, building on accelerating equipment utilisation, reshoring initiatives, and higher content-per-part as manufacturers pursue tighter tolerances and higher productivity.
Metal Cutting Tools Market
To frame scale: the market has expanded meaningfully since 2020 and, under our central scenario, is projected to approach the triple-digit billion-dollar realm by the end of the forecast window. Importantly, market concentration remains relatively low by conventional industrial metrics (CR3 roughly in the mid‑20s percent range; CR5 under 30%), signaling a highly fragmented competitive field where differentiated tooling solutions, service models, and supply-security propositions can still move the needle.
Metal Cutting Tools Market
Why This Matters in 2026: Dynamics that Demand Executive Attention
-
Raw material volatility is a strategic risk, not a cyclical nuisance. Manufacturers report sharp increases in tungsten carbide rod prices and constrained capacity in key precursor materials. In some pockets of the supply chain, raw-material costs have more than doubled in under two years, compressing margins and compelling buyers to renegotiate long-term contracts, hedge inputs, or shift to alternative grades and tool architectures.
-
Demand patterns are bifurcating. Machine shops and highly automated OEM lines are demonstrating renewed capital intensity and higher tool consumption per unit of output, while lower-tier manufacturing pockets remain price sensitive. Recent industry shipment reports indicate a strong uptick in cutting-tool demand seasonally and year-over-year, underscoring the uneven but robust pull through in critical markets.
-
Standards and institutional shifts are altering competitive boundaries. Industry associations and evolving certification regimes are raising entry and compliance expectations for manufacturers and re-manufacturers. These changes create both barriers for informal players and premium opportunities for suppliers that can demonstrate certified quality, traceability, and environmental stewardship.
-
Technology and services are converging. Toolmakers are increasingly selling productivity — not just inserts or end mills. Coatings, geometry innovation, prescriptive tool libraries, telemetry-enabled toolholders, and digital tool-life management are now competitive differentiators that impact customers’ total cost of ownership (TCO) assessments.
What the PW Consulting Report Delivers (Selected Practitioner Capabilities)
-
Scenario-based top-line and demand forecasting (2026–2032) calibrated to multiple macroeconomic and raw-material outlooks — enabling capital-plan stress testing and year-by-year cash-flow impact estimates.
-
Competitive benchmarking and capability maps for market leaders and challengers, including strategic positioning, product-platform breadth, channel models, and aftermarket footprints.
-
Supplier risk heatmaps and actionable mitigation playbooks — from hedging strategies and consignment stock models to nearshoring and dual-sourcing decision frameworks.
-
Go-to-market and pricing playbooks tailored to tiered customers (precision OEMs, contract manufacturers, repair & overhaul shops), with contract clause templates and margin management levers.
-
M&A and partnership screens: target archetypes, valuation heuristics, and integration checklists focused on capabilities that move value (coatings, regrinding & reconditioning, digital tool-management, local service networks).
-
Regulatory and standards impact assessment with compliance timelines and cost-to-certify estimates for critical markets and production footprints.
Competitive Landscape: Players, Strategic Postures, and Opportunity Spaces
The market is populated by a mix of global platform players, regional specialists, and highly focused niche innovators. The companies we reviewed exemplify the strategic archetypes in play:
-
Kennametal Inc. — A broad industrial platform with strengths in indexable inserts, carbide tooling, milling cutters, and holemaking. Kennametal’s scale and distribution network enable it to bundle tooling with application engineering services. Watch for continued emphasis on application-specific solutions (e.g., fastener industry tooling demonstrated at regional exhibitions) and for regional market plays that leverage local manufacturing to offset raw-material pressures.
-
Sandvik AB — A technology-led competitor emphasizing carbide inserts, turning and milling tools, and advanced metal-cutting solutions. Sandvik’s R&D cadence and strong OEM relationships position it to capture share in higher-margin, precision segments; however, the company’s premium positioning requires continued evidence of measurable productivity gains to justify price points in cost-sensitive pockets.
-
ISCAR Ltd. — A fast-mover in carbide inserts, drills, and indexable tooling, with a manufacturing base fully certified to international quality and environmental standards. ISCAR’s certified operations and systematic quality assurance are differentiators in customer segments where traceability and compliance matter.
-
OSG Corporation — Known for high-performance drills, taps, and end mills, OSG’s focus on engineered tools for precision applications makes it a natural beneficiary of rising demand in electronics, medical, and high-tolerance manufacturing.
-
Walter AG — Offers indexable inserts, turning and milling solutions, and modular systems that appeal to manufacturers seeking flexible tooling platforms. Modularization and systems thinking give Walter levers for aftermarket services and lifecycle revenue.
-
Ceratizit Group — A carbide tools and high-performance cutting specialist with a growing emphasis on tailored tool geometries and coatings. Ceratizit is a candidate for partnership plays around co-development and regional tooling centres of excellence.
-
TaeguTec Ltd. — A competitive supplier of carbide inserts and drills with strong regional manufacturing advantages and a product portfolio that targets mid‑to‑high end application needs.
Across these players, strategic differentiation falls into four visible vectors: (1) raw-material integration and inventory management, (2) application-engineering and digital services, (3) premium product innovation (coatings and ceramics), and (4) regional service networks and aftermarket reconditioning. Given the market’s fragmentation, mid‑market players that master one or two vectors can substantially improve their valuation multiples or become attractive acquisition targets.
Strategic Recommendations for 2026
-
Prioritise raw-material resilience: implement multi-year hedges, establish consigned inventory with key suppliers, and evaluate vertical integration or strategic stakes in critical precursor suppliers where scale justifies it.
-
Shift commercial focus from price-per-unit to productivity-per-hour: measure and sell the TCO delta that your tools deliver, and price according to demonstrable lifecycle value rather than entry price alone.
-
Invest selectively in digital tooling and analytics: even modest telemetry and tool-life modelling can unlock lower warranty costs, higher repeat-purchase rates, and closer OEM partnerships.
-
Target aftermarket and reconditioning as margin lever: tooling regrind, certification, and reman operations can be both defensive and accretive, particularly in markets facing raw-material scarcity.
-
Use M&A to fill capability gaps, not just add capacity: seek targets that add geometry or coating expertise, scale in a strategic geography, or an installed-service capability that accelerates cross-sell.
-
Prepare contract playbooks for 2026 procurement negotiations: include raw-material price-pass clauses, minimum take-or-pay bands, and shared inventory programs to mitigate input-cost volatility.
Closing: How PW Consulting’s Study Supports Your 2026 Playbook
This report synthesises market-scale forecasting, supplier and raw-material risk analysis, and a pragmatic set of go-to-market and operational interventions designed for immediate application. It is specifically calibrated to inform capital allocation and commercial planning for 2026 — from sourcing leaders and plant managers to corporate development and private-equity sponsors. If your team needs the granular regional, product-type, and application-level splits, the proprietary company scorecards, or the full scenario-model workbooks that underpin our recommendations, those datasets and interactive tools are available exclusively in the full PW Consulting report and client portal.
Contact PW Consulting to schedule a briefing with our metal-cutting tools practice; we will walk you through the models, stress scenarios, and opportunity screens that matter to your strategy in 2026.
For detailed analysis of this topic, please visit the official page: Metal Cutting Tools Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Moissanite Market to Reach USD 344.79M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-30
Moissanite Market 2026 Strategic Preview — A PW Consulting Brief
As PW Consulting’s lead industry analyst, I present a high-level strategic introduction to our full Moissanite Market study (base year: 2025; historical coverage: 2020–2025; forecast: 2026–2032). This brief is designed as a “trailer”: it surfaces the most consequential insights and implications that should shape executive decisions in 2026 while deliberately withholding detailed segment-level tables and proprietary models to encourage access to the complete report. All monetary figures in the full study are reported in USD Million.
Moissanite Market
Market trajectory at a glance
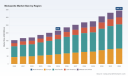
The global moissanite market has shown steady expansion through the early 2020s and is projected to continue growing at a robust compound annual growth rate (CAGR) of 6.98% over the 2026–2032 forecast horizon. After recovering from the pandemic-era disruptions, the market reached approximately 215.0 (USD Million) in 2025 and is forecast to approach roughly 344.8 (USD Million) by 2032. This growth path reflects a mix of expanding consumer acceptance, channel evolution, and increasingly sophisticated manufacturing and certification capabilities.
Moissanite Market
Why 2026 is a strategic inflection point
- Normalization of consumer preferences: By 2026, moissanite has moved beyond niche curiosity to become a mainstream alternative in key jewelry use-cases. That transition shifts decision criteria from novelty to quality, certification, and brand provenance.
- Channel evolution: Direct-to-consumer (DTC) platforms, vertical retailers, and traditional wholesale networks are entering distinct maturity phases. 2026 will be a decisive year for channel investment allocation.
- Cost and supply dynamics: Technology improvements in lab growth and cutting, coupled with supply-chain scaling in manufacturing clusters, are compressing unit costs—but also creating new quality and ethical standards that market-leading firms must adopt to sustain premium positioning.
- Regulatory and certification momentum: Expectations for transparent origin and grading are rising. Firms that proactively integrate traceability and independent certification will command competitive advantage.
Data-driven signals every executive must track
Our full study provides granular dashboards; the executive summary highlights the signals that will most influence outcomes in 2026:
Moissanite Market
- Market scale and growth rate: Use the market-level trajectory and 6.98% CAGR to stress-test revenue and investment scenarios for the next three-to-five years.
- Margin pressure vs. premiumization: Track unit-cost improvements against retail price elasticity. Some players are able to preserve margins by monetizing ethical sourcing and bespoke design; others compete on price—leading to divergent margin profiles.
- Channel mix shifts: Online and omnichannel sales continue to gain share; wholesale relationships and trade customers remain essential for scale.
- Quality and certification adoption: Certification frameworks are becoming decision gates for premium buyers; absence of recognized quality signals narrows addressable premium segments.
- Geopolitical and supply risk indicators: Manufacturing concentration and cross-border logistics exposures should be continuously monitored—especially for players relying on concentrated supplier bases.
Competitive landscape — profiles and strategic postures
The market comprises a mix of specialized retailers, branded player-manufacturers, wholesalers, and export-oriented producers. Notable competitive archetypes illustrated in our analysis include:
- Established branded innovators: Charles & Colvard, Ltd. (pioneer of the “Forever One” lab-grown moissanite) and Brilliant Earth emphasize brand, provenance, and ethical positioning. They pursue premiumization strategies and often control aspects of the vertical value chain.
- Design-led DTC specialists: MoissaniteCo combines an extensive design catalog with GIA-aligned quality processes, leaning into handcrafted and experiential positioning in the U.S. market.
- Wholesale & B2B enablers: Stuller, Inc. and similar suppliers serve professional jewelers with scale assortments, logistics integration, and trade credit—acting as distribution hubs for both finished goods and stones.
- Manufacturing and export clusters: Producers in China and India (including Wuzhou Changsheng, Stars Gem, Unimoss, HRB Exports, and Anand Gems) drive global supply with cost-competitive volume, while increasingly moving up the value chain through certification and finishing capabilities.
Market concentration is moderate-to-low: the top three and top five firms together capture a relatively small share of the total market (CR3 ~24.6%; CR5 ~26.2%), indicating a fragmented competitive field with meaningful opportunities for consolidation and differentiation.
Strategic playbook for 2026 decision-makers
Based on our scenario analysis and client engagements, we recommend executives consider the following strategic levers in 2026:
- Portfolio triage and SKU rationalization: Identify high-margin designs and certifications that deserve investment; prune low-turn, low-margin SKUs. Layer a “halo” premium collection with traceable provenance to capture margins while maintaining a competitive baseline assortment.
- Channel-tailored go-to-market: Differentiate offerings across DTC, wholesale, and retailer partnerships. Use DTC for storytelling and premium uplift; use wholesale for scale and trade credibility.
- Quality assurance & certification roadmap: Invest in third-party grading and traceability systems. For premium segments, certification is no longer optional—it's part of the product value proposition.
- Supply resilience and nearshoring options: Diversify supplier footprint and evaluate nearshore finishing capacity to reduce lead times and currency/transport exposure.
- Brand & sustainability positioning: Translate ethical sourcing and carbon footprints into tangible customer value—e.g., lifetime guarantees, trade-in programs, or transparent LCA (life-cycle analysis) claims.
- M&A and partnership playbook: Given fragmentation, bolt-on acquisitions of regional producers, finishers, or DTC brands can accelerate access to markets and capabilities. Target assets should add complementary capabilities (e.g., certification labs, bespoke manufacturing, or unique design IP).
- Price architecture and dynamic markdowns: Move away from static long-term price tiers. Implement dynamic pricing informed by inventory days, channel velocity, and seasonal demand.
Risk scenarios and mitigations
The moissanite market is attractive but not risk-free. Our report models three plausible scenarios (conservative, base, and accelerated growth) with corresponding stress tests. Key risks include:
- Regulatory & labeling shifts: Stricter rules on disclosure or grading could raise compliance costs. Mitigation: adopt proactive disclosure and invest in certification systems early.
- Substitution from lab-grown diamonds: Advances or price moves in lab-grown diamonds could compress moissanite’s addressable market. Mitigation: differentiate via design, certification, and cost-efficient manufacturing.
- Reputational incidents: Supply-chain controversies or quality failures damage premium positioning. Mitigation: implement traceability, supplier audits, and consumer-facing guarantees.
- Macroeconomic sensitivity: Luxury and discretionary spending influence demand volatility. Mitigation: diversify price points and increase penetration into affordable accessory segments.
What the PW Consulting report delivers (practical contents)
While this preview focuses on strategic implications, the full PW Consulting study delivers actionable tools and datasets that empower 2026 decision-making, including:
- Forward financial models (2026–2032) with scenario analysis and sensitivity toggles.
- Granular demand and channel forecasts, with elasticity matrices and price/volume trade-offs.
- Competitive benchmarking templates and capability heatmaps for the dozen-plus leading firms.
- Supplier mapping and a procurement playbook highlighting risk exposures and nearshoring levers.
- Go-to-market playbooks for premium, mid-market, and value segments—each with marketing KPIs and activation budgets calibrated to convert in 2026.
- Targeted M&A screening criteria and a short list of archetypal acquisition targets aligned to different strategic objectives.
- Case studies and interview summaries with category leaders and supply-side executives that reveal operational best practices.
To preserve competitive value and adhere to our “trailer” principle, the full report contains the detailed split tables, regional and application-level percentages, and downloadable models that underpin these recommendations. Those datasets are available via PW Consulting’s report portal.
Conclusion — actionable next steps for 2026
For executives preparing budgets and strategic plans in 2026, the moissanite market presents a clear growth runway underpinned by consumer acceptance, manufacturing maturity, and expanding retail formats. However, success will hinge on timely investments in certification, channel segmentation, supply resilience, and brand differentiation. Use the 6.98% CAGR and the market scale trajectory as boundary conditions in your planning models, then apply the playbook above to convert market growth into durable competitive advantage.
PW Consulting’s full Moissanite Market study is designed to move your strategy from insight to execution. Contact our advisory team to access the complete dataset, scenario models, and an implementation workshop tailored to your organization’s strategic priorities.
For detailed analysis of this topic, please visit the official page: Moissanite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Lift Chair Market 2026: Strategic Imperatives for Decision-Makers
As PW Consulting’s Senior Industry Analyst, I present a concise strategic preview of our comprehensive Lift Chair Market study (base year 2025; historical 2020–2025; forecast 2026–2032). The sector is entering a decisive phase: after a period of steady recovery and product refresh, the global market reached approximately USD 3,400 million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 7.5% through the 2026–2032 forecast window, crossing the multi‑billion threshold by the end of the period. For corporate leaders planning 2026 investments, M&A activity, or operational pivots, this report translates market momentum into actionable choice architecture—without giving away the granular segmentation that forms the core of our premium deliverable.
Lift Chair Market
Why 2026 Is a Strategic Inflection Point
- Demographics and reimbursement converge: An aging population and established reimbursement pathways have created a persistent demand base that is now being amplified by product innovation and distribution realignment.
- Manufacturing localization and supply resilience: Recent industry moves toward domestic manufacturing capacity reflect a broader re‑pricing of supply‑chain risk—an important factor for capital allocation and sourcing strategy.
- Product and service differentiation: The market is shifting from basic utility to wellness‑centric and integrated solutions, increasing the premium potential for differentiated players while compressing margins for undifferentiated OEMs.
What the Report Delivers (Practical Content Overview)
- Robust market sizing and validated growth scenarios: We model demand across 2020–2032, offering base, upside, and downside scenarios that isolate drivers such as reimbursement policy shifts, raw material price shocks, and aging‑population variants.
- Channel & commercial playbooks: Detailed go‑to‑market options for direct OEM retail, DME supplier partnerships, healthcare procurement, and e‑commerce—with impact matrices that quantify sales, margin and service cost sensitivities.
- Competitive benchmarking: A qualitative and quantitative framework to evaluate incumbents and challengers across product breadth, manufacturing footprint, regulatory positioning, and channel control—ranked on strategic levers rather than merely revenue share.
- Product roadmaps and white‑space analysis: Identifies high‑value product features (positioning systems, motors, ergonomic design, integrated therapy) and suggests prioritization paths for R&D investment that align with reimbursement incentives.
- Supply‑chain stress tests and cost buckets: Scenario analysis on critical inputs—high‑torque motors, scissor mechanisms, and steel—plus sourcing levers to reduce lead‑time risk and total landed cost.
- M&A and partnership playbooks: Criteria and shortlists for bolt‑on acquisitions, manufacturing JV targets, and channel alliances that accelerate scale while protecting margin.
- Implementation toolkit: Executive dashboards, ROI calculators, and a 90‑ to 180‑day rollout checklist for commercialization and operational adjustments.
Macro and Structural Dynamics Shaping Strategy
Three structural forces deserve immediate attention from C‑suite and corporate development teams:
Lift Chair Market
- Reimbursement complexity and clinical pathway integration. Lift chairs are often procured through healthcare channels because they qualify as durable medical equipment under Medicare Part B; crucially, coverage typically extends to the motorized lifting mechanism (subject to clinical documentation and supplier enrollment) rather than the furniture shell. This creates a two‑tier commercial landscape where the product and the clinical claim must be aligned—an area where partnerships with enrolled DME suppliers or new in‑house reimbursement capabilities can create defensible margins.
- Product safety and regulatory posture. Leading manufacturers market devices that meet medical‑device classifications and weight/safety standards; this raises the bar for product development and post‑market surveillance, but also creates opportunity for premiumization through verified clinical claims and ergonomics validated for chronic conditions such as arthritis and lower‑back disorders.
- Material and mechanical dependencies. Performance, serviceability and cost are driven by key components—high‑torque motors, robust scissor lift mechanisms and steel structural parts. Firms that de‑risk these inputs through alternate sourcing, supplier partnerships or vertical integration will enjoy superior uptime and service economics.
Competitive Landscape: Strategic Positions to Watch
The market comprises established furniture brands, specialized mobility manufacturers, and retail‑focused incumbents. Our research highlights several archetypes and current strategic moves:
Lift Chair Market
- Specialized mobility leaders: Companies with deep clinical positioning and dedicated mobility portfolios have translated product engineering into durable competitive advantage. Their strengths include regulatory knowhow, clinical claims, and distribution via enrolled DME networks.
- Furniture brands moving up‑market: Major furniture manufacturers are leveraging design heritage, retail reach and brand equity to capture wellness‑seeking consumers, often adding features such as heat/massage and premium upholstery to differentiate in retail channels.
- Integrated OEM‑retailer hybrids: Some market participants combine manufacturing scale with retail distribution, enabling faster product feedback cycles and closer control of margins and service.
Recent corporate developments point to tactical priorities: one leading manufacturer reduced lead times and extended model variants to address availability and fit; another expanded domestic manufacturing capacity to strengthen “made‑in‑USA” value propositions; and a market‑leading manufacturer earned industry recognition for product quality—signals that manufacturing agility and brand trust are central to near‑term competition.
Regulatory and Reimbursement Implications for 2026 Decisions
- Reimbursement as a strategic channel: Because motorized lifting mechanisms can be reimbursed under certain conditions, firms should assess whether to build in‑house clinical documentation and DME enrollment capabilities or to create partnership models with certified suppliers.
- Regulatory labeling and claims: Manufacturers that can demonstrate compliance with medical‑device classifications and safety standards will access institutional buyers and clinical referral pathways more readily; this requires investment in testing, documentation, and post‑market vigilance.
- Procurement friction points: The dual nature of sellable goods (chair + lift kit) introduces billing and warranty complexities that must be anticipated in pricing, contract terms and customer support planning.
Strategic Playbook for 2026
We outline five prioritized actions for executives preparing decisions in 2026. Each is linked to the commercial levers that will most influence returns in a market growing at c.7.5% per annum.
- Prioritize channel modernization. Invest in DME partnerships and digital ordering for clinical channels while refining premium retail assortments for direct‑to‑consumer sales. Test hybrid pricing pilots that separate the lift mechanism and furniture in controlled geographies.
- Secure critical component supply. Negotiate multi‑year contracts for motors and structural steel, pursue dual sourcing for high‑failure items, and evaluate nearshoring for the highest‑risk components to reduce lead time and tariff exposure.
- Differentiate through verified functionality. Allocate R&D to clinically‑validated positioning systems and ease‑of‑use features for elderly and bariatric users; small feature premiums can compound into significant margin improvement when aligned with reimbursement pathways.
- Operationalize service as a competitive moat. Develop warranty and aftercare programs, including technician networks and remote diagnostics, to convert one‑time buyers into service revenue streams and to reduce return rates.
- Evaluate M&A selectively. Target bolt‑ons that add DME enrollment capabilities, proprietary lift mechanisms, or regional manufacturing footprints that accelerate time‑to‑market and reduce unit costs.
Where the Report Helps You Now
For executives evaluating capital allocation and strategic initiatives in 2026, our study functions as both map and toolkit. It blends macro sizing and scenario planning with a practical set of deliverables: market models you can stress test, competitor dossiers you can use in diligence, and playbooks that can be operationalized within 90–180 days. The core segmentation and financial detail are intentionally reserved for the full report—this preview surfaces the directional insights that matter for confidential boardroom decisions while steering interested teams to the commissioned study for the detailed segment economics, regional breakdowns and company‑level revenue mixes.
Conclusion: From Insight to Competitive Action
The lift chair market is no longer a niche appliance category; it sits at the intersection of healthcare economics, aging‑population dynamics, and consumer wellness trends. With a 2025 market base in the billions (USD) and a mid‑single‑digit to high‑single‑digit CAGR ahead, firms that move early to secure component supply, build reimbursement competence, and differentiate through validated features will capture disproportionate value. PW Consulting’s full Lift Chair Market study provides the granular segmentation, competitor financials and prioritized implementation playbooks required to turn these strategic possibilities into measurable outcomes in 2026.
Contact PW Consulting to access the full market model, company profiles, and the decision‑ready implementation toolkit that underpin this preview.
For detailed analysis of this topic, please visit the official page: Lift Chair Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Grippers Market at USD 1,755M in 2025, Poised for 9.4% CAGR (2026–32)
By pmarketresearch, 2026-07-30
Grippers Market: Strategic Imperatives for 2026 — A PW Consulting Industry Brief
As global manufacturers accelerate automation strategies to solve persistent labor shortages, tighten safety compliance, and squeeze greater flexibility from production lines, grippers — the end-effectors that enable robots to touch, move, and manipulate — are no longer a commodity. They are a strategic lever. PW Consulting’s Grippers Market study (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes market dynamics, competitive positioning, regulatory shifts, and technology roadmaps to equip executives with the decision-grade intelligence required for 2026 and beyond.
Grippers Market
Why 2026 Is a Pivotal Year for Gripper Strategy
After steady expansion through the early 2020s, the grippers market enters the 2026 planning horizon with renewed urgency. Our base-year analysis concludes that market growth momentum—anchored by a compound annual growth rate (CAGR) of 9.4% across the 2026–2032 forecast window—will reshape supplier economics and buyer choices. In practical terms, companies that define gripper strategy in 2026 will lock in unit economics, ecosystem partnerships, and compliance postures that determine competitiveness for the remainder of the decade.
Grippers Market
High-Level Market Trajectory (Macro View)
- Base and historical framing: The study includes a robust historical series (2020–2025) and detailed forecasting from 2026 through 2032 to support short- and medium-term capital planning.
- Forecast growth dynamics: The projected 9.4% CAGR reflects an interplay of automation adoption, rising sophistication of collaborative and adaptive grippers, and replacement cycles driven by evolving safety standards and modular robotic platforms.
- Market structure: The market exhibits moderate concentration — our analysis shows the top three players account for a meaningful portion of value (CR3 at 45%), while the top five compress further (CR5 at 55%) — leaving room for focused challengers and niche innovators.
Dynamics Driving Adoption
- Labor constraints and operational continuity: By Q3 2025 manufacturers reported an average of 4.2% of roles unfilled, with a sizable subset facing vacancy pressures above 5%. These labor realities are pushing OEMs and end-users toward gripper-led automation for repetitive, ergonomically risky, or precision tasks.
- Regulation and safety: The 2025 revision of ISO 10218-2 embeds force and speed limits and expanded guidance for end-of-arm tooling. For firms deploying collaborative systems, compliance is not optional; end-effectors must now meet explicit thresholds and documented risk assessments for dropped loads and pinch points.
- Segment evolution: Demand motion is shifting from simple, high-throughput pneumatic designs toward hybrid solutions — electric actuation, integrated sensing, soft- and vacuum-based delicate handling — enabling new use cases in food, electronics, and medical device assembly.
Technology and Product Innovation — What to Watch in 2026
Innovation is converging on three vectors: intelligence at the end-effector (embedded sensors and tactile feedback), hygienic or food-safe materials, and plug-and-play integration for collaborative robots. Recent vendor activity illustrates these trends:
Grippers Market
- Destaco’s eRDH electric parallel gripper (launched mid-2025) emphasizes teachable sensors and configurable grip modes targeted at high-mix automotive cells.
- Festo’s late-2025 adaptive gripper introduces food-grade silicone and bionic handling concepts for hygienic pick-and-place applications.
- Robotiq’s early-2026 tactile fingertip integration signals a broader move to tactile-enabled manipulation that reduces vision dependency in unstructured pick tasks.
- Piab’s 2026 soft gripper for confectionery highlights how vacuum and soft-robotic hybrids are unlocking previously inaccessible categories.
Competitive Landscape: How to Read the Field
Our competitive analysis synthesizes vendor capabilities, route-to-market, and innovation pipelines. Key players profiled in the report include legacy industrial automation specialists, cobot-native entrants, and niche innovators:
- SCHUNK GmbH & Co. KG — modular systems portfolio spanning pneumatic, electric, and adaptive grippers tailored to industrial robotics platforms.
- OnRobot A/S — a leader in plug-and-play collaborative grippers and EOAT optimized for cobots and light-duty cells.
- DESTACO (Stabilus Group) — focused on electric and pneumatic parallel grippers with teachable sensor features for machine tending.
- Piab AB — vacuum and soft-grip expertise for packaging, palletizing, and delicate parts handling.
- Zimmer Group, Robotiq, Weiss Robotics, ATI Industrial Automation, Festo, and Schmalz — each brings differentiated strengths in intelligent gripping, force/torque integration, hygiene-compliant materials, or system-level integration.
While the market contains dominant incumbents, there is ample space for specialist providers that combine material science, sensing, and software integration to capture premium segments. The report offers supplier scorecards, partnership archetypes, and negotiating playbooks suited to OEMs, system integrators, and end-users.
What PW Consulting’s Grippers Market Report Delivers (Practical, Actionable Content)
We structured the study to be immediately operational for commercial planning and procurement cycles in 2026:
- Executive strategy frameworks — decision trees for make vs. buy, modularization priorities, and portfolio rationalization across product lines.
- Commercial models — TCO and ROI templates calibrated to gripper lifecycle drivers (actuation type, maintenance cadence, sensor integration), with sensitivity analyses for price, uptime, and labor substitution.
- Procurement playbook — supplier scorecards, SLA templates, and criteria for vendor qualification that factor in regulatory compliance, service coverage, and software interoperability.
- Integration and deployment blueprints — recommended control architectures, safety validation checklists aligned to ISO 10218-2:2025, and pragmatic steps for achieving collaborative safety without sacrificing throughput.
- Strategic scenario planning — three demand scenarios (baseline, accelerated automation, and constrained-capex) with corresponding capital and sourcing pathways for 2026–2028.
- M&A and partnership guidance — target profiles for bolt-on technologies, due-diligence checklists for IP and field reliability, and valuation sensitivities tied to modularity and software capability.
- Market and technology roadmaps — timelines of expected adoption inflection points for electric actuation, soft gripping, integrated tactile sensing, and standardization trends.
- Field intelligence — anonymized use cases and measured KPIs from deployments across high-turnover sectors to illustrate real-world payback periods and pitfalls.
Methodology and Forecast Rigor
The report’s forecast blends bottom-up shipment and pricing models with macro adoption curves and historical data (2020–2025). We triangulate primary interviews with OEMs, system integrators, and leading suppliers with secondary sources to stress-test assumptions. Scenario sensitivity allows users to adjust key inputs — adoption rate, price erosion, and regulatory compliance costs — to quantify outcomes across CAPEX cycles.
Strategic Recommendations for 2026 Decision-Makers
- Prioritize modularity: Insist on grippers with standardized mechanical interfaces and documented electrical/software APIs to preserve future flexibility and reduce lock-in.
- Treat sensing as a first-class requirement: Tactile and force sensing transform grippers from passive tools into active decision points that reduce vision dependency and increase yield in mixed-SKU lines.
- Embed compliance early in procurement: With ISO 10218-2:2025 tightening requirements for end-effectors, integrate safety validation into vendor selection rather than as a retrofit project.
- Build hybrid sourcing strategies: Combine long-term strategic agreements with niche buys to balance cost, innovation access, and risk mitigation — particularly for food-safe and soft-grip applications.
- Plan for total cost, not unit price: Evaluate maintenance, downtime risk, spare-parts availability, and software update pathways during capex approval stages.
How to Use This Report to Gain Competitive Advantage
For manufacturers, the study functions as a procurement and line-engineering playbook that shortens deployment timelines and clarifies ROI. For suppliers, the report is a go-to-market manual, defining whitespace opportunities, vertical use case primers, and partnership models that accelerate adoption. Investors gain an evidence-based lens into concentration dynamics and the competitive swaths most likely to reap scale economies.
Closing Perspective
By 2026, grippers will be judged not only by grip force or cycle time, but by their contribution to a resilient, compliant, and flexible production system. PW Consulting’s Grippers Market report offers the strategic scaffolding to transform gripper choices from tactical purchases into strategic enablers of productivity and safety. The report reveals the data, templates, and competitive intelligence you need to make informed decisions; it intentionally reserves proprietary segment-level granularity and supplier share tables for the full report to preserve client value and ensure rigorous interpretation.
To access the complete dataset, supplier scorecards, and executable playbooks that underpin these insights, visit the report page or contact PW Consulting’s industry team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Grippers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Turbomolecular Pumps Market to Hit USD 2,460M by 2032 at 5.5% CAGR
By pmarketresearch, 2026-07-30
Turbo Molecular Pumps Market — 2026 Strategic Preview
By PW Consulting — Senior Strategic Advisor / Head of Industry Analysis
This briefing frames the strategic decisions that matter in 2026 for executives operating in or adjacent to the turbomolecular pumps market. Drawing on our PW Consulting market model (base year 2025; historical window 2020–2025; forecast horizon 2026–2032) and primary research across OEMs, integrators and end-users, this preview highlights where value will accrue, where risk is concentrating, and which tactical moves buy time versus create durable advantage. The purpose is to demonstrate technical and commercial depth while reserving core segmented datasets for the full report.
Turbo Molecular Pumps (Turbomolecular Pumps) Market
Market snapshot — macro trajectory you can act on
The turbomolecular pumps market reached approximately USD 1.69 billion in 2025 and is forecast to grow at a steady compound annual growth rate of about 5.5% over the 2026–2032 period, reaching roughly USD 2.46 billion by 2032 under our base scenario. After a measured recovery from 2020–2023, the market experienced an acceleration in 2024 and 2025 driven by capacity build-outs in semiconductor and advanced materials processing, and the maturation of higher-throughput maglev and hybrid solutions. Market concentration is meaningful: the top three vendors account for a majority share of revenue, and the top five raise that concentration modestly further — an important structural feature for pricing dynamics, aftermarket opportunity and M&A playbooks.
Turbo Molecular Pumps (Turbomolecular Pumps) Market
Key demand & supply dynamics shaping 2026 decisions
-
Policy and procurement are now technical levers. Energy-efficiency directives in major jurisdictions have already pushed OEMs to deliver lower-wattage drives and intelligent standby modes. Public-sector procurement and large-system integrators are explicitly scoring energy intensity and lifecycle emissions, creating a near-term bid advantage for pump platforms with validated efficiency credentials.
Turbo Molecular Pumps (Turbomolecular Pumps) Market -
Net-zero roadmaps impose multi-year product and capital cycles. Net-zero energy-intensity requirements in Europe and North America extend planning horizons for manufacturers (multi-year compliance windows), forcing choices between incremental efficiency upgrades and more fundamental architecture changes (e.g., wider adoption of magnetic levitation and smart power electronics).
-
Semiconductor and life-science ecosystems are demand multipliers. Policy stimuli and domestic fab programs are sustaining demand for higher pumping speeds and lower base pressures in select submarkets; procurement timelines and qualification hurdles remain long, making early engagement and co-development with strategic customers a high-return activity.
-
Raw-material and component risk is concentrated but manageable. Bearings made from advanced stainless steels such as Cronidur 30 extend service life and lower total cost of ownership, but rare-earth magnet supply risk for maglev rotors is prompting design responses — dual sourcing, magnet-reduced rotor concepts and increased tolerance for lower dysprosium content.
Technology trajectories and product strategy
-
Magnetic levitation versus mechanical bearings. Maglev platforms continue to advance performance, reliability and maintenance economics; however, they introduce different supply-chain exposures (rare-earth magnets, specialized power electronics). Mechanical (oil-lubricated and ball-bearing) architectures remain attractive for certain industrial coatings and retrofit niches because of lower upfront cost and established service networks.
-
Hybrid architectures as a pragmatic bridge. Hybrid designs that combine elements of maglev control with mechanical resilience are emerging as a strategic compromise for customers unwilling to accept full maglev life-cycle trade-offs immediately.
-
Software and systems matter as much as spinning hardware. Digital features — predictive maintenance, remote diagnostics, and intelligent standby — now materially affect procurement choices. OEMs that bundle proven software services alongside validated power-efficiency metrics capture higher aftermarket revenue and improve retention.
Supply chain and cost resilience — what to prioritize now
-
Dual-source critical magnets and bearings. Short-term supplier diversification for rare-earth magnets and advanced stainless alloys is a high-payoff defensive move. Firms should invest in audited second-source qualification and flexible bill-of-materials testing.
-
Vertical or contractual integration for power electronics. Control boards and motor drives are an underappreciated source of differentiation. Securing capacity or preferred pricing for advanced inverter components reduces time-to-market risk for new maglev platforms.
-
Aftermarket and service-first strategies. With replacement cycles longer but service margins higher, developing modular upgrade kits (efficiency retrofits, maglev upgrade paths) and standardized field-service training yields durable margin expansion.
Competitive landscape — who to watch and why
The field is characterized by a mix of established vacuum OEMs and technology-led entrants. The following firms are active players we tracked closely; each has distinct strategic strengths that make them potential partners, competitors or acquisition targets depending on your objectives:
-
Edwards Vacuum — Burgess Hill, United Kingdom — https://www.edwardsvacuum.com. Strengths: broad mechanical turbomolecular ranges (nEXT and STP series) and expanding maglev offerings; notable go-to-market across industrial and analytical segments. Recent visibility at Analytica 2026 underscores channel engagement and field validation efforts.
-
Pfeiffer Vacuum — Aßlar, Germany — https://www.pfeiffervacuum.com. Strengths: comprehensive TURBOPUMPS portfolio spanning mechanical, magnetic and hybrid bearings with strong positioning in high/ultra-high vacuum applications and systems integration capability.
-
Ebara Corporation — Tokyo, Japan — https://www.ebara.com. Strengths: high-throughput maglev turbopumps and strong manufacturing throughput; emphasis on performance and throughput metrics for industrial customers.
-
Leybold — Cologne, Germany — https://www.leybold.com. Strengths: robust TURBOVAC i/iX family tailored to industrial coating and research use-cases; recent product expansion signals continued focus on hardening designs for tough working environments.
-
ULVAC — Chigasaki, Japan — https://www.ulvac.com. Strengths: desktop and mid-range maglev and ball-bearing series with channel focus in Asia; modular product platforms that appeal to OEM integrators.
-
Agilent Technologies — Santa Clara, CA, USA — https://www.agilent.com. Strengths: analytical and research-grade high-vacuum turbo pumps backed by broad customer relationships in instruments and laboratories.
Recent market signals
-
Edwards Vacuum showcased nEXT and STP series alongside T-Station pumping solutions at Analytica 2026 — a signal of continued investment in channel demonstration and turnkey pumping solutions (March 2026).
-
Leybold expanded its TURBOVAC i/iX family with robust variants aimed at industrial coating and research applications — a reminder that ruggedized mechanical platforms retain clear niche relevance (March 2026).
Strategic playbook for 2026 — actions by role
-
OEMs: Prioritize a three-track product roadmap: immediate low-power drive retrofits, medium-term maglev proliferation with supply-chain hardening, and long-term platform redesigns that lower lifecycle emissions. Pair product launches with service bundles to capture recurring revenue.
-
Component suppliers: Move from spot-selling into co-development agreements for bearings and magnet systems. Offer qualification packages and extended warranties to shorten OEM certification cycles.
-
Systems integrators and large end-users: Lock multi-year service contracts and negotiate upgrade credits tied to energy-efficiency performance. Early engagement in OEM R&D roadmaps reduces qualification risk and shortens adoption timelines.
-
Private equity and corporate development teams: Look for tuck-in opportunities in aftermarket services, software-enabled maintenance platforms, and regional service centers to leverage the concentrated market structure and aftermarket margins. Use buy-and-build plays to capture retrofit demand.
What PW Consulting’s full report delivers (practical modules)
-
Detailed market sizing and 2026–2032 forecasts with scenario and sensitivity analyses, including upside and downside demand drivers.
-
Segment-level demand maps (by region, product architecture, and application) and prioritized TAM/SAM/SOM frameworks for commercial planning.
-
Vendor benchmarking with product matrices, technology scorecards, go-to-market positioning, and aftermarket revenue models.
-
Supply-chain risk register (critical components, second-source options, and cost-inflation scenarios) and an implementation playbook for mitigation actions.
-
Commercial playbooks: pricing levers, qualification pathways for semiconductor and life-science customers, RFQ templates, and retrofit upgrade pricing guide.
-
M&A and partnership screening toolkits with candidate lists, valuation guardrails, and integration risk checklists.
Concluding perspective
The turbomolecular pumps market in 2026 is neither nascent nor fully commoditized — it sits in a phase where technical differentiation (bearing architecture, electronics, and software) and regulatory-driven efficiency credentials meaningfully influence commercial outcomes. Firms that move early to secure critical materials, offer service-forward total-cost-of-ownership propositions, and align roadmaps with public-sector energy/CHIPS-driven demand will create asymmetric returns. PW Consulting’s full study provides the granular segment-level maps, vendor scorecards and executable playbooks executives need to prioritize investment and M&A through 2026 and beyond.
To access the complete dataset, supplier scorecards, and the operational playbook referenced above, contact PW Consulting or visit our report portal for licensing and tailored advisory options.
For detailed analysis of this topic, please visit the official page: Turbo Molecular Pumps (Turbomolecular Pumps) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Heat Guns Market to Hit USD 2,185.8M by 2032 at 4.3% CAGR
By pmarketresearch, 2026-07-30
Heat Guns Market 2026 Strategic Brief: Why This Report Will Shape Your Decisions
Executive summary
As strategic decision-makers prepare plans for 2026, understanding the structural trajectory of the heat guns market is no longer optional — it is mission critical. PW Consulting’s latest market research uses a 2025 base year and a 2026–2032 forecast window to map a market that has moved from recovery into structurally supported expansion. Our topline model places the global market at approximately USD 1,613.6 Million in 2025 and projects it to reach roughly USD 2,185.8 Million by 2032, reflecting a compound annual growth rate (CAGR) of 4.3% across the forecast period. Historical trends from 2020 through 2025 show steady expansion with episodic volatility tied to macro cycles and supply-side shocks — context that underpins our forward scenarios.
Heat Guns Market
Beyond raw growth, market structure matters. Competitive concentration is meaningful: the three largest manufacturers control a clear majority of industry revenue, while the five largest firms account for an even larger share. This dynamic creates both barriers and levers for incumbents and challengers — scale delivers distribution and R&D advantages, while pockets of fragmentation leave room for targeted disruption.
Heat Guns Market
What the PW Consulting report delivers (practical, actionable content)
This study is designed for executives, corporate development teams, product leaders, and commercial strategists who need immediately actionable insight rather than academic description. Key deliverables include:
Heat Guns Market
- Robust market sizing and forecasting models (base year 2025; forecast 2026–2032) with transparent assumptions and scenario variants (baseline, upside, downside).
- Proprietary demand-driver decomposition that links end-market activity, channel shifts, and technology adoption to volume and revenue outcomes.
- Competitive benchmarking across product capabilities, channel reach, and non-price propositions (warranty, service, digital features).
- Commercial playbooks for product portfolio optimization, channel segmentation, pricing strategies, and after-sales monetization.
- Supply chain and cost-structure maps highlighting supplier concentration, single-sourcing risks, and relocation options.
- M&A target screening and value creation templates for bolt-on and roll-up scenarios, together with integration risk checklists.
- Regulatory and safety compliance matrix with jurisdictional triggers and cost-to-compliance estimates.
- Excel-based sensitivity tools and slide-ready strategic roadmaps that can be adapted to corporate constraints and investment horizons.
We intentionally present synthesis, strategic implications, and diagnostic tools in this brief; detailed subsegment-level datasets (by type, application, and region), including granular percentage splits and downloadable tables, are reserved for the full report and our client portal.
Strategic implications for 2026 decision-makers
The macro trajectory (CAGR 4.3% to 2032) and the concentration profile produce a set of strategic priorities you should adopt immediately if you want to convert market tailwinds into durable advantage:
- Prioritize product differentiation linked to professional use-cases. Growth is being driven by professional and industrial demand that values robustness, temperature precision, and serviceability. Commodity models will face margin pressure — invest selectively in features and extended warranties that create lock-in.
- Accelerate cordless and energy-efficiency roadmaps. Advances in battery chemistry and motor efficiency are enabling cordless form factors that are attractive to professional users and retrofit channels. Early movers who combine battery systems with proprietary thermal control software capture premium price points.
- Design channel strategies for dual distribution models. The market favors both traditional distributor networks (professional/industrial buyers) and big-box/DIY channels. Successful firms maintain differentiated SKUs, pricing ladders, and logistics playbooks for each channel rather than a one-size-fits-all approach.
- Monetize after-sales services and consumables. Consumable elements (nozzles, filters), maintenance contracts, and rapid-replacement programs are low-effort levers to increase lifetime value in a market where product cycles are measured in years.
- Use M&A to fill capability gaps, not just revenue. With top players holding a majority of market share, disciplined bolt-ons that add battery expertise, heat-control electronics, or service networks often unlock more value than horizontal roll-ups alone.
- Fix supply-chain resilience as a strategic objective. Raw-material swings and component shortages materially affect lead times. Dual-sourcing strategies, near-shore options, and inventory-as-a-service should be stress-tested in 2026 budgets.
- Embed sustainability and safety in product roadmaps. Regulatory scrutiny and procurement preferences are shifting to lower embodied energy and safer end-of-life profiles. These are not compliance costs alone — they are differentiators.
Competitive landscape: what the leading manufacturers are signaling
Our competitive analysis profiles the major incumbents and their strategic postures. Across the landscape, several consistent patterns emerge:
- Large global tool OEMs — including established players headquartered in Japan, Germany, and the United States — leverage strong channel partnerships and broad product portfolios to defend professional and consumer demand. Their assets include scale manufacturing, recognized brands, and deep distribution.
- Specialist manufacturers — focused on hot-air technology and professional applications — compete on thermal control, ergonomics, and service propositions. For many buyers, product-level performance and trusted durability trump headline price.
- Newer entrants and regional specialists — particularly those emphasizing cordless and energy-efficient designs — are using narrow product differentiation and aggressive channel partnerships to gain footholds.
Company-level strategies that matter in 2026:
- Invest in cordless ecosystems: firms that can pair heat guns to a common battery platform across tools create cross-selling synergies and higher customer switching costs.
- Optimize aftermarket revenue: warranty extensions, consumables, and service contracts are practical routes to margin expansion even in mature segments.
- Leverage distribution intelligence: real-time channel analytics and differentiated SKUs per channel reduce stock-outs and deepen shelf presence.
For organizations evaluating partnerships, licensing, or acquisition targets, our report includes an executable matrix that ranks prospective counterparties by technology fit, geographic reach, and integration complexity.
Risks and leading indicators to monitor through 2026
Strategic planning must be scenario-ready. Monitor these leading indicators closely to recalibrate decisions mid-course:
- Battery and component cost curves — significant improvements will accelerate cordless adoption and compress price elasticities.
- Regulatory shifts in electrical safety and emissions — new standards can create short-run compliance costs and long-run market advantage for early adopters.
- Construction and industrial activity indices — demand sensitivity remains highest to capex and renovation cycles.
- Channel inventory and sell-through rates — divergence between distributor inventories and point-of-sale can signal pending price competition or supply constraints.
- Consolidation activity among mid-tier suppliers — rapid roll-ups can change supplier bargaining power overnight.
How PW Consulting can accelerate your 2026 agenda
PW Consulting couples deep industry bench strength with hands-on commercial execution. If you engage with us, we will:
- Deliver a compact executive dashboard (KPIs and triggers) tailored to your product portfolio and markets of interest.
- Run a rapid commercial due diligence stream for M&A targets, with integration playbooks and 100-day value-capture plans.
- Co-create product and channel pilots that test cordless, service-based, and premium-performance propositions in controlled geographies.
- Provide workshop-based alignment with sales, product, and operations to translate market scenarios into 2026 budgets and R&D roadmaps.
Next steps — why the full report matters
This brief highlights the strategic vectors that will shape success in 2026. To act with conviction, you need the full set of granular inputs that inform investment sizing, SKU-level pricing, and regional go-to-market sequencing. While this introduction surfaces the market’s trajectory, concentration dynamics, and practical implications for corporate strategy, the detailed subsegment datasets (by type, application, and region), supplier lists, and modeled scenarios are intentionally withheld here to preserve actionable exclusivity in the full PW Consulting deliverable.
For leaders who must translate a 4.3% forecast CAGR and a structurally consolidating landscape into profitable action: secure the full report, adopt a prioritized execution plan, and treat 2026 as the year to convert product and channel investments into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Heat Guns Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Gibberellin Acid Market Poised for 8.15% CAGR Through 2032 — PW Consulting
By pmarketresearch, 2026-07-30
Gibberellin Acid (GA) Market — Strategic Outlook for 2026 Decision-Makers
Executive summary: why this briefing matters for 2026 strategy
As companies reset budgets and strategic priorities for 2026, plant growth regulators — and gibberellin acids (GAs) in particular — have moved from niche tool to an operational lever across fruit production, specialty crops, malting and turf management. Our market modelling shows a clearly accelerating revenue trajectory from a 2025 base to 2032, underpinned by sustained demand for yield/quality improvement, regulatory reclassifications, and manufacturing innovation. The market, measured in USD Million, grew through 2020–2025 and, with a compound annual growth rate of 8.15% over the forecast window, reaches materially higher absolute scale by 2032.
Gibberellin Acid (GA) Market
For executives evaluating portfolio allocation, M&A, commercial expansion or manufacturing investments in 2026, this report functions as both a decision support tool and a competitive intelligence compass: it validates the commercial opportunity in headline metrics while reserving the granular, actionable segment tables and price-volume curves for licensed subscribers.
Gibberellin Acid (GA) Market
Market trajectory at a glance (base year and forecast)
- Base year: 2025 (established as our anchor for model calibration)
- Forecast horizon: 2026–2032
- Compound annual growth rate (CAGR): 8.15% across the forecast period
- Our bottom-line view: the GA industry transitions from steady supplementation to strategic crop-management adoption, with 2026 representing the inflection year when product innovation and regulatory clarity converge to expand commercial pathways.
To give executives a sense of scale without substituting for contract-level market data: the modelled market expands meaningfully year-on-year from the 2025 anchor into the 2026–2032 window, reflecting both volume-driven adoption and value accrual from higher-margin formulation innovations. Our financial modelling is denominated in USD Million and supports scenario analysis at range-bound, base-case and upside assumptions — all available in the full report.
Gibberellin Acid (GA) Market
Key dynamics shaping the GA market in 2026
- Regulatory clarity and re-registration cycles. Recent regulatory activity at both regional and federal levels has reduced compliance uncertainty. Notable administrative updates and renewal processes in 2025–2026 have created predictable windows for formulators and registrants to secure or expand labeled uses. Firms with regulatory bandwidth can convert this predictability into faster label extensions and broader crop claims in 2026.
- Product innovation pushes premiumization. The market is seeing formulation-led differentiation — lower-volatility concentrates, organic-eligible registrations and crop-specific blends that unlock new use-cases (e.g., delayed ripening, shelf-life extension, cell expansion). Recent product introductions demonstrate the willingness of large agri-players to seek higher-margin, value-added PGR offerings.
- Manufacturing and input-cost evolution. Advances in fermentation and bioprocessing — including probiotic-enabled fermentations and other optimized bioproduction techniques adopted late in 2025 — have improved unit economics across the supply chain. This both compresses cost for bulk suppliers and permits reinvestment in formulation R&D for differentiated products.
- Commercialization and channel sophistication. Adoption is being driven not only by price and efficacy but by better integration into agronomic service models, supply-chain partnerships with packers/processors, and digital agronomy that quantifies GA impact on post-harvest value. Companies that treat GA products as a service — combining application timing, analytics and crop-rotation playbooks — will capture disproportionate share of value.
- Market structure and concentration. The competitive landscape is moderately fragmented: aggregate concentration metrics highlight that the top three to five players do not dominate to the degree seen in other agrochemical segments. This structural openness creates opportunity for fast-followers and specialists to scale via targeted shelf-space, channel partnerships and formulation niches.
Competitive landscape — how leading players are positioning (implications for partners and rivals)
The GA market combines legacy agrochemical incumbents, specialty formulators, and large regional producers. Key actors illustrate distinct strategic archetypes:
- Platform incumbents focused on brand & channel (example: Valent BioSciences, Nufarm, Corteva). These players leverage established distribution networks, registered labels, and brand trust to commercialize full-channel rollouts. Their advantage lies in integrated marketing to growers and in regulatory resources to expand labeled uses. Expect these firms to prioritize high-visibility crop segments and formulations with clear ROI stories.
- Specialty formulators and turf/aquatic specialists (example: Fine Americas, SePRO, Greenleaf Chemical). These companies compete on tailored formulations and technical support for horticulture, ornamentals and turf. They are natural partners for packers and nursery chains seeking customized dosing and application timing.
- Cost-competitive bulk producers (example: Jiangsu Fengyuan, Zhengzhou Delong). Producers with scale in bulk GA synthesis or fermentation can underwrite competitive pricing and supply reliability. Their strategic path is either to remain B2B suppliers to formulators or to pursue forward integration into branded lines where channel access exists.
- New product entrants and organic-eligible offerings (example: Corteva's recent launch). Companies launching low-volatile, organic-eligible formulations are targeting premium segments and sustainability-focused customers. These launches signal that regulator-approved, market-differentiated GA products can command higher price points and may catalyze adoption in crops previously unconvinced by conventional formulations.
For 2026, strategic actions by competitors will cluster around three playbooks: (1) accelerate label expansion and OMRI/organic clearances; (2) scale margin-enhancing formulations and service bundles; (3) secure raw-material sourcing via long-term supply agreements or backward integration. Firms pursuing multiple tracks simultaneously will require careful capital allocation and disciplined go-to-market sequencing.
Where the commercial opportunities lie — pragmatic scenarios for 2026
- Premiumization in high-value fruit and specialty crops. Grower willingness to pay increments for quality and shelf-life improvements creates an attractive avenue for higher-margin formulations. Sales teams should refocus on packer contracts and post-harvest service propositions.
- Service-led adoption in malting and industrial crops. In segmented, process-sensitive applications, integrating product application with agronomic advisory services reduces user hesitation and locks in annuity revenues.
- Channel rollups and co-pack agreements. Distributors and regional formulators can secure supply and margins by signing multi-year supply or co-manufacturing deals with bulk producers — an effective hedge against short-term price volatility.
- Regulatory arbitrage through targeted registrations. Prioritize territories and label claims where the regulatory timeline offers first-mover advantage in 2026–2027.
What the full report contains — practical deliverables for strategy teams
Our full Gibberellin Acid Market study is structured for operational use by commercial, regulatory, and M&A teams. It includes:
- Detailed historical and forecast revenue series (2020–2032) denominated in USD Million, with scenario sensitivity and unit-volume drivers;
- Segment-level demand drivers, pricing dynamics and margin matrices (note: granular segment tables and proprietary share estimates are gated for subscribers);
- Regulatory matrix and timeline by jurisdiction, highlighting re-registration windows, label extension pathways and compliance cost estimates;
- Supplier and channel maps with risk heatmaps for raw-material concentration, logistics exposure and single-source dependencies;
- Commercial playbooks — go-to-market frameworks for branded formulations, service bundles, and contract manufacturing partnerships;
- Due-diligence checklist and valuation heuristics for potential M&A targets in bulk, formulation, and channel assets;
- Appendix of primary and secondary sources, including recent product launches and regulatory notices for 2025–2026.
How to use the insights in 2026 planning cycles
- Board level: Use our scenario outputs to stress-test capex asks tied to new formulation lines or fermentation capacity, and to inform M&A premium tolerance for strategic acquisitions.
- Commercial leaders: Revisit channel incentives and pricing tiers using the report’s margin ladder and breakeven timelines; prioritize crops and packer relationships where shelf-life premiumization creates the sharpest ROI.
- R&D and registration teams: Align pipeline priorities with regulatory windows and product features that unlock premium status (e.g., low-volatility, organic-eligible formulations).
- Supply chain and procurement: Reconfigure supply agreements to insulate against feedstock volatility and to capture benefits from improved bioprocess economics.
Closing — the strategic playbook for 2026
Gibberellin acids are no longer a specialist curiosity: they are a strategic lever in crop-value engineering. Our modelling — anchored on a 2025 base year and projecting forward to 2032 at a compound annual growth rate of 8.15% — shows a market that rewards both operational excellence in production and commercial sophistication in go-to-market. The competitive field is sufficiently open that disciplined entrants can capture share, but success in 2026 will be decided by three capabilities: regulatory execution, formulation differentiation, and integration into customer value chains.
This article is a high-level preview of the analytical depth available in PW Consulting’s full Gibberellin Acid (GA) Market report. To review the complete segment matrices, proprietary share estimates, and ready-to-execute playbooks that support board-level decisions in 2026, please consult the full study on our website.
For detailed analysis of this topic, please visit the official page: Gibberellin Acid (GA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Natural Rubber market to hit USD 344.8M by 2032 at 5.86% CAGR
By pmarketresearch, 2026-07-30
Natural Rubber Market 2026: Strategic Outlook and Decision-Grade Insights
As PW Consulting’s senior industry analyst, I present a concise, decision-focused preview of our 2026 Natural Rubber Market study. This briefing synthesizes the authoritative market sizing, trajectory and strategic implications that corporate leaders, procurement heads and investors need to act with confidence in 2026 — while preserving the granular, transaction-grade datasets for readers who access the full report.
Natural Rubber Market
Executive snapshot
The natural rubber market has demonstrated steady recovery and expansion through the 2020–2025 historical window, with our base year set at 2025. Measured in USD (Million), total market revenue moved from an earlier cycle low to an elevated 2025 level and — under our central forecast path — is projected to continue growing through 2032 at a compound annual growth rate (CAGR) of approximately 5.86%. By 2032 the market reaches a materially larger scale, reflecting demand resilience in key applications and structural supply dynamics that will shape strategic choices in 2026.
Natural Rubber Market
Why this study matters for 2026 decision-making
- Actionable foresight: The report translates macro growth (2020–2025 history and a 2026–2032 forecast horizon) into tactical signals for procurement windows, contract tenors and inventory policy. It identifies time-sensitive inflection points where supply constraints and regulatory milestones converge.
- Risk-to-return mapping: We connect physical supply risks, commodity price drivers and evolving sustainability rules to quantify downside exposure for manufacturers and traders — enabling calibrated capital allocation and hedging strategies.
- Competitive advantage: The study surfaces strategic levers for producers and processors — from traceability investments and upstream partnerships to premium product positioning — that can convert regulatory compliance into price differentiation and margin capture.
Market trajectory and underlying drivers
The market’s recent expansion is neither accidental nor uniformly distributed: structural demand from mobility and industrial rubber goods plus cyclical restocking drove the recovery through 2025. Our forecast to 2032 assumes continued urbanization, vehicle parc growth in emerging markets and a shift in product mixes toward higher-value latex and specialty grades. On the supply side, natural rubber’s biological production cycles, land-use constraints and climate variability create a baseline of limited elasticity — meaning supply shocks propagate quickly into availability and commercial terms.
Natural Rubber Market
Key drivers that executives must monitor in 2026 include:
- Regulatory compliance costs and traceability requirements that raise the marginal cost of sourcing from opaque supply chains.
- Climate and weather risk affecting core producing regions and smallholder yields, which can compress supply in short windows.
- Downstream substitution and product innovation trends (e.g., synthetic blends, engineered elastomers) that alter premium spreads and long-term demand composition.
Regulatory inflection: EUDR and the new compliance horizon
Regulatory changes in 2026 create a firm, date-certain obligation for market participants interacting with the EU: supply-chain traceability and no-deforestation evidence will be mandatory for natural rubber and rubber-based products placed on the EU market. This is not a distant policy risk — it is a near-term operational reality that impacts onboarding, certification timelines and supplier qualification. Large operators should assume immediate resource needs for plot-level traceability, third-party verification pathways and supplier engagement protocols.
Supply dynamics and the short-term shock layer
Beyond structural constraints, the market’s short-term risk profile has been elevated by episodic production disruptions. Recent extreme-weather episodes in key producing geographies have tightened available volumes and exposed the limits of spot-market flexibility. For 2026 planning, commercial teams must treat weather-related production disruptions as persistent tail risks and stress-test supply scenarios across a range of durations and intensities.
Competitive landscape — what the market structure implies
The natural rubber processing and exporting segment is dominated by several integrated, vertically proficient players that combine plantation exposure, processing scale and global trading networks. These firms — ranging from large Thai processors to Malaysia- and Vietnam-based integrated groups — set commercial norms for quality specification, service levels and traceability capabilities. For buyers, this concentration translates into a twofold strategic reality:
- Counterparty stability: long-term contracts with established processors can reduce volatility in physical availability and support traceable sourcing commitments.
- Supplier power: concentrated processing capacity gives leading processors leverage to enforce premium structures for certified, compliant material and to set delivery terms during constrained periods.
Our full study profiles the leading processors and exporters in depth, assessing their asset footprints, sustainability programs and supply-chain reach. We identify which players are positioned to meet traceability requirements and which may face capital or operational constraints as compliance timelines accelerate.
What practical, operable content the full report contains
- Methodology and assumptions: base year (2025), historical window (2020–2025), forecast horizon (2026–2032), currency and units, and sensitivity scenarios around price and supply shocks.
- Top-line market sizing and growth trajectory, with scenario-based forecasts under alternative demand and supply pathways.
- Supply-chain mapping and risk heatmaps that identify geographic, operational and governance exposures at each node of the value chain.
- Regulatory impact assessment: compliance playbooks for EUDR readiness, auditability pathways and supplier engagement templates.
- Commercial playbook: procurement tactics, contract structures, inventory optimization heuristics and hedging instruments calibrated to rubber market behavior.
- Competitive benchmarking: executive summaries of major processors and suppliers, their strategic strengths and gaps, and M&A/partnership opportunities.
- Executive dashboards and data annexes: downloadable tables, forecast series and scenario outputs suitable for board-level briefings and procurement systems.
Practical strategic recommendations for 2026
Based on our integrated analysis, we recommend that market participants prioritize the following actions in 2026:
- Operationalize traceability now: invest in plot-level traceability pilots with a subset of suppliers and align contractual terms to on-ramp compliance documentation. Delay increases implementation risk and cost.
- Diversify sourcing across supplier archetypes: combine relationships with integrated processors, regional aggregators and certified smallholder cooperatives to balance cost, traceability and resilience.
- Adopt a layered procurement approach: blend short-term spot purchases (for flexibility) with multi-year supply agreements tied to sustainability milestones and index-linked pricing.
- Invest in supplier capacity building: co-fund yield-improvement and sustainability programs with trusted suppliers to reduce future compliance costs and secure preferential access to certified volumes.
- Prepare contingency capital: maintain liquidity buffers and pre-arranged credit lines to act quickly when physical availability tightens and premiums emerge.
- Assess strategic M&A and alliance targets: prioritize assets that provide traceable supply, processing control or technological capability (e.g., traceability platforms, analytics providers) that can be integrated within 12–18 months.
Implications for investors and financial sponsors
The market’s mid-term growth path and concentrated processing base create selective investment opportunities. Value capture will favor firms that can credibly de-risk supply chains against regulatory and climate shocks, demonstrate premium product differentiation and scale traceability economically. Our report surfaces targets and partnership models that can de-risk buyer portfolios and accelerate revenue capture in certified product lines.
Why this is a ‘trailer’ not the full movie
This article is intended to surface the strategic contours you need to act in 2026 — the full report contains the granular segmentation, regional allocation, application-level demand detail and downloadable time-series data you will require to operationalize the recommendations. We deliberately withhold the transaction-level tables and subsegment percentages here so that decision-makers can access the validated datasets through the report portal and apply them directly to commercial models, risk systems and board materials.
Next steps
- Procurement and supply-chain leaders should request our compliance playbook to begin traceability pilots this quarter.
- Strategy and corporate development teams should book a briefing to review our supplier scorecards and prioritized M&A targets.
- Investors and traders: contact PW Consulting for the full forecast tables, scenario outputs and bespoke valuation overlays.
PW Consulting’s Natural Rubber Market report is built to be a practical tool for 2026: rigorous in method, targeted in recommendations and executable at commercial scale. For the full datasets, segment-level analysis and proprietary company benchmarking that underpin these conclusions, please access the complete report on our website or contact our team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Natural Rubber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Physiological Saline Market to Reach USD 8.8B by 2032 at 7.4% CAGR
By pmarketresearch, 2026-07-30
Physiological Saline Market — Strategic Preview for 2026 Decision-Making
As health systems stabilize after recent supply shocks and as clinicians and procurement teams recalibrate sourcing strategies, physiological saline remains one of the most strategically important commodities in acute care and ambulatory settings. PW Consulting’s forthcoming market research, based on a 2025 base year and a 2026–2032 forecast horizon, synthesizes five years of historical performance (2020–2025) and projects forward under multiple scenario assumptions. At the macro level, the market is projected to expand at a compound annual growth rate (CAGR) of 7.4% from 2026 through 2032, progressing from an estimated USD 5,200 Million in 2025 to roughly USD 8,800 Million by 2032. This briefing previews the strategic intelligence in the full report and highlights the direct actions executives should be prioritizing in 2026.
Physiological Saline Market
Why this market matters in 2026
-
Operational leverage: Physiological saline is both a high-volume clinical input and a gateway product that shapes hospital procurement relationships, IV therapy formularies, and supplier contracting cycles.
Physiological Saline Market -
Margin and mix dynamics: While saline itself is a low-margin, high-volume item, packaging formats, proprietary container technologies, and supply reliability create differentiated value capture opportunities.
Physiological Saline Market -
Systemic risk mitigation: The industry’s recovery from prior shortages and the regulatory actions that followed mean supply-chain resilience now influences capital allocation and partnership strategies across hospital systems and manufacturers.
Market snapshot: growth trajectory and structural drivers
From a historical base of approximately USD 3,500 Million in 2020, the global physiological saline market experienced steady recovery and acceleration through 2025, driven by expanded elective care, increased outpatient hydration and infusion therapy utilization, and stabilization of manufacturing capacity. The market scale reached an estimated USD 5,200 Million in 2025. Under PW Consulting’s central forecast—reflecting demand normalization, moderate price pressure, and investment in non-PVC packaging—the market is expected to grow to about USD 5,464 Million in 2026 and to roughly USD 8,800 Million by 2032, representing a 7.4% CAGR over the forecast period. These headline figures underscore a resilient, mid-single-digit-to-low-double-digit growth market that rewards both scale and operational excellence.
What the report contains (practical, action-ready intelligence)
-
Executive dashboards: Clear KPIs for procurement, manufacturing, and commercial leaders—capacity utilization thresholds, reorder point frameworks, and packaging ROI models tailored for 2026 procurement cycles.
-
Demand modeling: Scenario-based demand curves that incorporate clinical utilization trends, outpatient infusion expansion, and potential episodic demand shocks—presented with sensitivity analyses to inform buffer-stock policies.
-
Supply map and risk heatmap: Granular supplier mapping, contract tenure analysis, and geographic fragility indices to guide near-term dual-sourcing or stockpiling decisions.
-
Commercial playbooks: Tender-winning approaches by region and channel, value-based contracting constructs for hospital networks, and pricing levers informed by reimbursement code dynamics.
-
Manufacturing and packaging assessment: Capex prioritization matrix for converters and OEMs, cost trade-offs between PVC vs. non-PVC containers, and guidance on lifecycle management of sterile fill lines.
-
M&A and partnership screening: Criteria-driven targets for bolt-on manufacturing capacity, regional distribution partnerships, and technology licensing opportunities.
-
Regulatory and reimbursement tracker: Up-to-date mapping of critical codes, policy changes, and shortage declarations that materially affect unit economics and procurement negotiation posture.
Competitive landscape: what leading firms are doing
The physiological saline market remains strategically contested by a set of established injectable and IV-fluid specialists. Leading manufacturers emphasize reliability, container innovation, and integrated hospital solutions rather than volume-only competition. Key strategic positions observed in the market include:
-
Baxter International: A long-standing leader in IV fluids, Baxter’s Viaflex and Viaflo systems continue to anchor hospital procurement lists. Recent commercial expansion initiatives in early 2026 indicate a push to broaden market access and reinforce supply commitments—moves that increase competitive pressure in markets where buyers prioritize single-supplier simplicity and validated logistics.
-
B. Braun Melsungen: With a portfolio built around extracellular fluid replacement in established container formats, B. Braun pursues a steady combination of clinical education and channel depth to defend share in hospital formularies where clinical familiarity and product interchangeability matter.
-
Fresenius Kabi: The company’s Freeflex bag strategy and its March 2026 distribution partnership reinforce a distribution-led expansion play. Fresenius is optimizing route-to-market strength to capture growth in markets with fragmented distribution and tender-driven procurement.
-
ICU Medical / Otsuka collaborations: Non-PVC/non-DEHP container offerings and joint manufacturing arrangements reflect a differentiation strategy pitched at hospital systems and procurement teams seeking compliance with emerging patient-safety and sustainability standards.
-
Grifols & Laboratorios Grifols: Positioning around polypropylene bags and plasma-donation applications anchors their relevance in integrated hospital-plasma ecosystems, where cross-selling saline for donation and inpatient use can create channel synergies.
-
Otsuka Pharmaceutical and AdvaCare: These players focus on regional partnerships and branded irrigation/indication-specific products, exploiting agility to serve targeted clinical use-cases and specialized channels.
Across the landscape, the market exhibits a degree of concentration around several incumbent players who control a majority of supply—making scale, validated quality systems, and logistics reliability decisive competitive advantages. The full report provides a deeper assessment of partner fit and competitive risk by scenario; those sub-segment tables and exact share estimates are reserved for the complete study.
Regulatory and reimbursement context shaping 2026 choices
-
Shortage resolution: The FDA formally declared the nationwide shortage of 0.9% sodium chloride injections resolved in August 2025. That regulatory milestone has immediate implications for inventory policies—hospitals that kept elevated safety stocks are now reviewing target levels, and manufacturers are recalibrating production schedules toward optimal utilization rather than emergency surge capacity.
-
Billing and reimbursement: HCPCS code J7030 (infusion normal saline solution, 1000 cc) remains a key billing code; Medicare reimbursement for this code historically averages in a low-single-digit-dollar range per unit depending on setting. Reimbursement nuance continues to affect how providers price outpatient infusion services and how suppliers justify value-added service charges.
-
Infusion service coding: Changes to CPT codes relevant to pre-packaged normal saline fluids (including revisions effective September 2025) affect documentation and reimbursement workflows for hydration services—an operational detail procurement teams must monitor to avoid unfavorable margin shifts in third-party clinic contracts.
Strategic playbook for 2026 — prioritized actions
-
Secure tiered supply: Immediate steps should include establishing multi-year supply agreements with clear capacity guarantees, indexed price collars, and accelerated fulfillment clauses for surge events. Where possible, negotiate inventory consignment or vendor-managed inventory (VMI) to reduce working capital.
-
Invest selectively in packaging: Prioritize conversion to non-PVC containers where clinical or regulatory trends favor them, but adopt a staged approach—pilots in high-volume hospital systems before large-scale capital deployment.
-
Pursue distribution partnerships: For manufacturers seeking market expansion, target partners with tender-execution strength and hospital contracting relationships. Distribution agreements can accelerate adoption without the time-to-market cost of new local manufacturing.
-
Refine commercial models: Align tender bids and private-label propositions with hospital reimbursement realities. For integrated providers, consider bundled care agreements that include infusion services and supply to capture downstream value.
-
Screen M&A targets for resilience and scale: Look for regional production sites with experienced sterile-fill capabilities, plus logistic assets that reduce lead times in priority geographies.
How executives should use this brief and next steps
This preview outlines the strategic imperatives PW Consulting anticipates will most influence decisions in 2026. The full market study contains the granular modeling, supplier scorecards, tender-performance benchmarks, and detailed segment-level estimations necessary to operationalize these recommendations. To protect competitive sensitivity and ensure consultative value, we intentionally withhold sub-segment-level tables and certain regional share breakdowns from this summary; the complete report includes those analytics together with an interactive decision-support toolkit.
If your planning cycle for 2026 encompasses procurement commitments, M&A scoping, or manufacturing investments, we recommend the following immediate next steps: obtain the full PW Consulting Physiological Saline Market report for supplier- and channel-level insight; run a rapid internal sourcing review using our scenario templates; and convene a cross-functional task force (procurement, clinical leads, manufacturing, and finance) to operationalize the priority playbook above.
Closing thought
Physiological saline may read as a commodity on the surface, but its strategic implications in 2026 are far from trivial. The market’s steady growth—anchored by an estimated USD 5.2 Billion base in 2025 and an expected rise to approximately USD 8.8 Billion by 2032 at a 7.4% CAGR—creates opportunities for players who combine scale, supply resiliency, and commercial innovation. PW Consulting’s full report converts these macro trends into executable choices; this preview is designed to orient leadership discussions and highlight where rapid action can lock in advantage in the year ahead.
For detailed analysis of this topic, please visit the official page: Physiological Saline Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com