

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Natural Rubber market to hit USD 344.8M by 2032 at 5.86% CAGR

Natural Rubber Market 2026: Strategic Outlook and Decision-Grade Insights
As PW Consulting’s senior industry analyst, I present a concise, decision-focused preview of our 2026 Natural Rubber Market study. This briefing synthesizes the authoritative market sizing, trajectory and strategic implications that corporate leaders, procurement heads and investors need to act with confidence in 2026 — while preserving the granular, transaction-grade datasets for readers who access the full report.
Natural Rubber Market
Executive snapshot
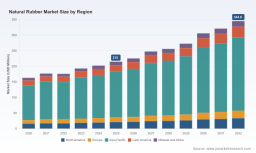
The natural rubber market has demonstrated steady recovery and expansion through the 2020–2025 historical window, with our base year set at 2025. Measured in USD (Million), total market revenue moved from an earlier cycle low to an elevated 2025 level and — under our central forecast path — is projected to continue growing through 2032 at a compound annual growth rate (CAGR) of approximately 5.86%. By 2032 the market reaches a materially larger scale, reflecting demand resilience in key applications and structural supply dynamics that will shape strategic choices in 2026.
Natural Rubber Market
Why this study matters for 2026 decision-making
- Actionable foresight: The report translates macro growth (2020–2025 history and a 2026–2032 forecast horizon) into tactical signals for procurement windows, contract tenors and inventory policy. It identifies time-sensitive inflection points where supply constraints and regulatory milestones converge.
- Risk-to-return mapping: We connect physical supply risks, commodity price drivers and evolving sustainability rules to quantify downside exposure for manufacturers and traders — enabling calibrated capital allocation and hedging strategies.
- Competitive advantage: The study surfaces strategic levers for producers and processors — from traceability investments and upstream partnerships to premium product positioning — that can convert regulatory compliance into price differentiation and margin capture.
Market trajectory and underlying drivers
The market’s recent expansion is neither accidental nor uniformly distributed: structural demand from mobility and industrial rubber goods plus cyclical restocking drove the recovery through 2025. Our forecast to 2032 assumes continued urbanization, vehicle parc growth in emerging markets and a shift in product mixes toward higher-value latex and specialty grades. On the supply side, natural rubber’s biological production cycles, land-use constraints and climate variability create a baseline of limited elasticity — meaning supply shocks propagate quickly into availability and commercial terms.
Natural Rubber Market
Key drivers that executives must monitor in 2026 include:
- Regulatory compliance costs and traceability requirements that raise the marginal cost of sourcing from opaque supply chains.
- Climate and weather risk affecting core producing regions and smallholder yields, which can compress supply in short windows.
- Downstream substitution and product innovation trends (e.g., synthetic blends, engineered elastomers) that alter premium spreads and long-term demand composition.
Regulatory inflection: EUDR and the new compliance horizon
Regulatory changes in 2026 create a firm, date-certain obligation for market participants interacting with the EU: supply-chain traceability and no-deforestation evidence will be mandatory for natural rubber and rubber-based products placed on the EU market. This is not a distant policy risk — it is a near-term operational reality that impacts onboarding, certification timelines and supplier qualification. Large operators should assume immediate resource needs for plot-level traceability, third-party verification pathways and supplier engagement protocols.
Supply dynamics and the short-term shock layer
Beyond structural constraints, the market’s short-term risk profile has been elevated by episodic production disruptions. Recent extreme-weather episodes in key producing geographies have tightened available volumes and exposed the limits of spot-market flexibility. For 2026 planning, commercial teams must treat weather-related production disruptions as persistent tail risks and stress-test supply scenarios across a range of durations and intensities.
Competitive landscape — what the market structure implies
The natural rubber processing and exporting segment is dominated by several integrated, vertically proficient players that combine plantation exposure, processing scale and global trading networks. These firms — ranging from large Thai processors to Malaysia- and Vietnam-based integrated groups — set commercial norms for quality specification, service levels and traceability capabilities. For buyers, this concentration translates into a twofold strategic reality:
- Counterparty stability: long-term contracts with established processors can reduce volatility in physical availability and support traceable sourcing commitments.
- Supplier power: concentrated processing capacity gives leading processors leverage to enforce premium structures for certified, compliant material and to set delivery terms during constrained periods.
Our full study profiles the leading processors and exporters in depth, assessing their asset footprints, sustainability programs and supply-chain reach. We identify which players are positioned to meet traceability requirements and which may face capital or operational constraints as compliance timelines accelerate.
What practical, operable content the full report contains
- Methodology and assumptions: base year (2025), historical window (2020–2025), forecast horizon (2026–2032), currency and units, and sensitivity scenarios around price and supply shocks.
- Top-line market sizing and growth trajectory, with scenario-based forecasts under alternative demand and supply pathways.
- Supply-chain mapping and risk heatmaps that identify geographic, operational and governance exposures at each node of the value chain.
- Regulatory impact assessment: compliance playbooks for EUDR readiness, auditability pathways and supplier engagement templates.
- Commercial playbook: procurement tactics, contract structures, inventory optimization heuristics and hedging instruments calibrated to rubber market behavior.
- Competitive benchmarking: executive summaries of major processors and suppliers, their strategic strengths and gaps, and M&A/partnership opportunities.
- Executive dashboards and data annexes: downloadable tables, forecast series and scenario outputs suitable for board-level briefings and procurement systems.
Practical strategic recommendations for 2026
Based on our integrated analysis, we recommend that market participants prioritize the following actions in 2026:
- Operationalize traceability now: invest in plot-level traceability pilots with a subset of suppliers and align contractual terms to on-ramp compliance documentation. Delay increases implementation risk and cost.
- Diversify sourcing across supplier archetypes: combine relationships with integrated processors, regional aggregators and certified smallholder cooperatives to balance cost, traceability and resilience.
- Adopt a layered procurement approach: blend short-term spot purchases (for flexibility) with multi-year supply agreements tied to sustainability milestones and index-linked pricing.
- Invest in supplier capacity building: co-fund yield-improvement and sustainability programs with trusted suppliers to reduce future compliance costs and secure preferential access to certified volumes.
- Prepare contingency capital: maintain liquidity buffers and pre-arranged credit lines to act quickly when physical availability tightens and premiums emerge.
- Assess strategic M&A and alliance targets: prioritize assets that provide traceable supply, processing control or technological capability (e.g., traceability platforms, analytics providers) that can be integrated within 12–18 months.
Implications for investors and financial sponsors
The market’s mid-term growth path and concentrated processing base create selective investment opportunities. Value capture will favor firms that can credibly de-risk supply chains against regulatory and climate shocks, demonstrate premium product differentiation and scale traceability economically. Our report surfaces targets and partnership models that can de-risk buyer portfolios and accelerate revenue capture in certified product lines.
Why this is a ‘trailer’ not the full movie
This article is intended to surface the strategic contours you need to act in 2026 — the full report contains the granular segmentation, regional allocation, application-level demand detail and downloadable time-series data you will require to operationalize the recommendations. We deliberately withhold the transaction-level tables and subsegment percentages here so that decision-makers can access the validated datasets through the report portal and apply them directly to commercial models, risk systems and board materials.
Next steps
- Procurement and supply-chain leaders should request our compliance playbook to begin traceability pilots this quarter.
- Strategy and corporate development teams should book a briefing to review our supplier scorecards and prioritized M&A targets.
- Investors and traders: contact PW Consulting for the full forecast tables, scenario outputs and bespoke valuation overlays.
PW Consulting’s Natural Rubber Market report is built to be a practical tool for 2026: rigorous in method, targeted in recommendations and executable at commercial scale. For the full datasets, segment-level analysis and proprietary company benchmarking that underpin these conclusions, please access the complete report on our website or contact our team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Natural Rubber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com