

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Heat Guns Market to Hit USD 2,185.8M by 2032 at 4.3% CAGR

Heat Guns Market 2026 Strategic Brief: Why This Report Will Shape Your Decisions
Executive summary
As strategic decision-makers prepare plans for 2026, understanding the structural trajectory of the heat guns market is no longer optional — it is mission critical. PW Consulting’s latest market research uses a 2025 base year and a 2026–2032 forecast window to map a market that has moved from recovery into structurally supported expansion. Our topline model places the global market at approximately USD 1,613.6 Million in 2025 and projects it to reach roughly USD 2,185.8 Million by 2032, reflecting a compound annual growth rate (CAGR) of 4.3% across the forecast period. Historical trends from 2020 through 2025 show steady expansion with episodic volatility tied to macro cycles and supply-side shocks — context that underpins our forward scenarios.
Heat Guns Market
Beyond raw growth, market structure matters. Competitive concentration is meaningful: the three largest manufacturers control a clear majority of industry revenue, while the five largest firms account for an even larger share. This dynamic creates both barriers and levers for incumbents and challengers — scale delivers distribution and R&D advantages, while pockets of fragmentation leave room for targeted disruption.
Heat Guns Market
What the PW Consulting report delivers (practical, actionable content)
This study is designed for executives, corporate development teams, product leaders, and commercial strategists who need immediately actionable insight rather than academic description. Key deliverables include:
Heat Guns Market
- Robust market sizing and forecasting models (base year 2025; forecast 2026–2032) with transparent assumptions and scenario variants (baseline, upside, downside).
- Proprietary demand-driver decomposition that links end-market activity, channel shifts, and technology adoption to volume and revenue outcomes.
- Competitive benchmarking across product capabilities, channel reach, and non-price propositions (warranty, service, digital features).
- Commercial playbooks for product portfolio optimization, channel segmentation, pricing strategies, and after-sales monetization.
- Supply chain and cost-structure maps highlighting supplier concentration, single-sourcing risks, and relocation options.
- M&A target screening and value creation templates for bolt-on and roll-up scenarios, together with integration risk checklists.
- Regulatory and safety compliance matrix with jurisdictional triggers and cost-to-compliance estimates.
- Excel-based sensitivity tools and slide-ready strategic roadmaps that can be adapted to corporate constraints and investment horizons.
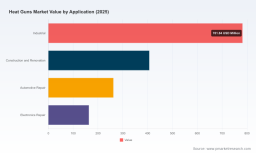
We intentionally present synthesis, strategic implications, and diagnostic tools in this brief; detailed subsegment-level datasets (by type, application, and region), including granular percentage splits and downloadable tables, are reserved for the full report and our client portal.
Strategic implications for 2026 decision-makers
The macro trajectory (CAGR 4.3% to 2032) and the concentration profile produce a set of strategic priorities you should adopt immediately if you want to convert market tailwinds into durable advantage:
- Prioritize product differentiation linked to professional use-cases. Growth is being driven by professional and industrial demand that values robustness, temperature precision, and serviceability. Commodity models will face margin pressure — invest selectively in features and extended warranties that create lock-in.
- Accelerate cordless and energy-efficiency roadmaps. Advances in battery chemistry and motor efficiency are enabling cordless form factors that are attractive to professional users and retrofit channels. Early movers who combine battery systems with proprietary thermal control software capture premium price points.
- Design channel strategies for dual distribution models. The market favors both traditional distributor networks (professional/industrial buyers) and big-box/DIY channels. Successful firms maintain differentiated SKUs, pricing ladders, and logistics playbooks for each channel rather than a one-size-fits-all approach.
- Monetize after-sales services and consumables. Consumable elements (nozzles, filters), maintenance contracts, and rapid-replacement programs are low-effort levers to increase lifetime value in a market where product cycles are measured in years.
- Use M&A to fill capability gaps, not just revenue. With top players holding a majority of market share, disciplined bolt-ons that add battery expertise, heat-control electronics, or service networks often unlock more value than horizontal roll-ups alone.
- Fix supply-chain resilience as a strategic objective. Raw-material swings and component shortages materially affect lead times. Dual-sourcing strategies, near-shore options, and inventory-as-a-service should be stress-tested in 2026 budgets.
- Embed sustainability and safety in product roadmaps. Regulatory scrutiny and procurement preferences are shifting to lower embodied energy and safer end-of-life profiles. These are not compliance costs alone — they are differentiators.
Competitive landscape: what the leading manufacturers are signaling
Our competitive analysis profiles the major incumbents and their strategic postures. Across the landscape, several consistent patterns emerge:
- Large global tool OEMs — including established players headquartered in Japan, Germany, and the United States — leverage strong channel partnerships and broad product portfolios to defend professional and consumer demand. Their assets include scale manufacturing, recognized brands, and deep distribution.
- Specialist manufacturers — focused on hot-air technology and professional applications — compete on thermal control, ergonomics, and service propositions. For many buyers, product-level performance and trusted durability trump headline price.
- Newer entrants and regional specialists — particularly those emphasizing cordless and energy-efficient designs — are using narrow product differentiation and aggressive channel partnerships to gain footholds.
Company-level strategies that matter in 2026:
- Invest in cordless ecosystems: firms that can pair heat guns to a common battery platform across tools create cross-selling synergies and higher customer switching costs.
- Optimize aftermarket revenue: warranty extensions, consumables, and service contracts are practical routes to margin expansion even in mature segments.
- Leverage distribution intelligence: real-time channel analytics and differentiated SKUs per channel reduce stock-outs and deepen shelf presence.
For organizations evaluating partnerships, licensing, or acquisition targets, our report includes an executable matrix that ranks prospective counterparties by technology fit, geographic reach, and integration complexity.
Risks and leading indicators to monitor through 2026
Strategic planning must be scenario-ready. Monitor these leading indicators closely to recalibrate decisions mid-course:
- Battery and component cost curves — significant improvements will accelerate cordless adoption and compress price elasticities.
- Regulatory shifts in electrical safety and emissions — new standards can create short-run compliance costs and long-run market advantage for early adopters.
- Construction and industrial activity indices — demand sensitivity remains highest to capex and renovation cycles.
- Channel inventory and sell-through rates — divergence between distributor inventories and point-of-sale can signal pending price competition or supply constraints.
- Consolidation activity among mid-tier suppliers — rapid roll-ups can change supplier bargaining power overnight.
How PW Consulting can accelerate your 2026 agenda
PW Consulting couples deep industry bench strength with hands-on commercial execution. If you engage with us, we will:
- Deliver a compact executive dashboard (KPIs and triggers) tailored to your product portfolio and markets of interest.
- Run a rapid commercial due diligence stream for M&A targets, with integration playbooks and 100-day value-capture plans.
- Co-create product and channel pilots that test cordless, service-based, and premium-performance propositions in controlled geographies.
- Provide workshop-based alignment with sales, product, and operations to translate market scenarios into 2026 budgets and R&D roadmaps.
Next steps — why the full report matters
This brief highlights the strategic vectors that will shape success in 2026. To act with conviction, you need the full set of granular inputs that inform investment sizing, SKU-level pricing, and regional go-to-market sequencing. While this introduction surfaces the market’s trajectory, concentration dynamics, and practical implications for corporate strategy, the detailed subsegment datasets (by type, application, and region), supplier lists, and modeled scenarios are intentionally withheld here to preserve actionable exclusivity in the full PW Consulting deliverable.
For leaders who must translate a 4.3% forecast CAGR and a structurally consolidating landscape into profitable action: secure the full report, adopt a prioritized execution plan, and treat 2026 as the year to convert product and channel investments into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Heat Guns Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com