

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Metal Cutting Tools Market to Reach USD 119,133 Million by 2032 at 5.82% CAGR

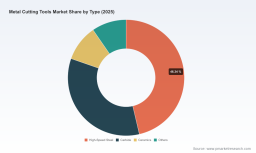
Metal Cutting Tools Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a forward-looking synthesis designed to equip executives, investors, and operational leaders with the strategic context they need entering 2026. Our latest Metal Cutting Tools Market study combines robust macro forecasting with operational playbooks and competitive diagnostics to support high-stakes decisions across supply chain design, product investment, pricing, and M&A. This introduction highlights the report’s strategic value, the dynamics shaping the sector, and the implication set we believe will matter most next year — while intentionally reserving the full, granular splits and proprietary scoring matrices for the full report available on our website.
Metal Cutting Tools Market
Market Snapshot: Size, Trajectory, and Concentration
The metal cutting tools market has transitioned from steady recovery to a structurally stronger growth path. Using 2025 as the base year, our top-line forecast shows the market growing at a compound annual growth rate (CAGR) of approximately 5.82% across the 2026–2032 horizon. That trajectory reflects a continuation of recovery that began in the early 2020s, building on accelerating equipment utilisation, reshoring initiatives, and higher content-per-part as manufacturers pursue tighter tolerances and higher productivity.
Metal Cutting Tools Market
To frame scale: the market has expanded meaningfully since 2020 and, under our central scenario, is projected to approach the triple-digit billion-dollar realm by the end of the forecast window. Importantly, market concentration remains relatively low by conventional industrial metrics (CR3 roughly in the mid‑20s percent range; CR5 under 30%), signaling a highly fragmented competitive field where differentiated tooling solutions, service models, and supply-security propositions can still move the needle.
Metal Cutting Tools Market
Why This Matters in 2026: Dynamics that Demand Executive Attention
-
Raw material volatility is a strategic risk, not a cyclical nuisance. Manufacturers report sharp increases in tungsten carbide rod prices and constrained capacity in key precursor materials. In some pockets of the supply chain, raw-material costs have more than doubled in under two years, compressing margins and compelling buyers to renegotiate long-term contracts, hedge inputs, or shift to alternative grades and tool architectures.
-
Demand patterns are bifurcating. Machine shops and highly automated OEM lines are demonstrating renewed capital intensity and higher tool consumption per unit of output, while lower-tier manufacturing pockets remain price sensitive. Recent industry shipment reports indicate a strong uptick in cutting-tool demand seasonally and year-over-year, underscoring the uneven but robust pull through in critical markets.
-
Standards and institutional shifts are altering competitive boundaries. Industry associations and evolving certification regimes are raising entry and compliance expectations for manufacturers and re-manufacturers. These changes create both barriers for informal players and premium opportunities for suppliers that can demonstrate certified quality, traceability, and environmental stewardship.
-
Technology and services are converging. Toolmakers are increasingly selling productivity — not just inserts or end mills. Coatings, geometry innovation, prescriptive tool libraries, telemetry-enabled toolholders, and digital tool-life management are now competitive differentiators that impact customers’ total cost of ownership (TCO) assessments.
What the PW Consulting Report Delivers (Selected Practitioner Capabilities)
-
Scenario-based top-line and demand forecasting (2026–2032) calibrated to multiple macroeconomic and raw-material outlooks — enabling capital-plan stress testing and year-by-year cash-flow impact estimates.
-
Competitive benchmarking and capability maps for market leaders and challengers, including strategic positioning, product-platform breadth, channel models, and aftermarket footprints.
-
Supplier risk heatmaps and actionable mitigation playbooks — from hedging strategies and consignment stock models to nearshoring and dual-sourcing decision frameworks.
-
Go-to-market and pricing playbooks tailored to tiered customers (precision OEMs, contract manufacturers, repair & overhaul shops), with contract clause templates and margin management levers.
-
M&A and partnership screens: target archetypes, valuation heuristics, and integration checklists focused on capabilities that move value (coatings, regrinding & reconditioning, digital tool-management, local service networks).
-
Regulatory and standards impact assessment with compliance timelines and cost-to-certify estimates for critical markets and production footprints.
Competitive Landscape: Players, Strategic Postures, and Opportunity Spaces
The market is populated by a mix of global platform players, regional specialists, and highly focused niche innovators. The companies we reviewed exemplify the strategic archetypes in play:
-
Kennametal Inc. — A broad industrial platform with strengths in indexable inserts, carbide tooling, milling cutters, and holemaking. Kennametal’s scale and distribution network enable it to bundle tooling with application engineering services. Watch for continued emphasis on application-specific solutions (e.g., fastener industry tooling demonstrated at regional exhibitions) and for regional market plays that leverage local manufacturing to offset raw-material pressures.
-
Sandvik AB — A technology-led competitor emphasizing carbide inserts, turning and milling tools, and advanced metal-cutting solutions. Sandvik’s R&D cadence and strong OEM relationships position it to capture share in higher-margin, precision segments; however, the company’s premium positioning requires continued evidence of measurable productivity gains to justify price points in cost-sensitive pockets.
-
ISCAR Ltd. — A fast-mover in carbide inserts, drills, and indexable tooling, with a manufacturing base fully certified to international quality and environmental standards. ISCAR’s certified operations and systematic quality assurance are differentiators in customer segments where traceability and compliance matter.
-
OSG Corporation — Known for high-performance drills, taps, and end mills, OSG’s focus on engineered tools for precision applications makes it a natural beneficiary of rising demand in electronics, medical, and high-tolerance manufacturing.
-
Walter AG — Offers indexable inserts, turning and milling solutions, and modular systems that appeal to manufacturers seeking flexible tooling platforms. Modularization and systems thinking give Walter levers for aftermarket services and lifecycle revenue.
-
Ceratizit Group — A carbide tools and high-performance cutting specialist with a growing emphasis on tailored tool geometries and coatings. Ceratizit is a candidate for partnership plays around co-development and regional tooling centres of excellence.
-
TaeguTec Ltd. — A competitive supplier of carbide inserts and drills with strong regional manufacturing advantages and a product portfolio that targets mid‑to‑high end application needs.
Across these players, strategic differentiation falls into four visible vectors: (1) raw-material integration and inventory management, (2) application-engineering and digital services, (3) premium product innovation (coatings and ceramics), and (4) regional service networks and aftermarket reconditioning. Given the market’s fragmentation, mid‑market players that master one or two vectors can substantially improve their valuation multiples or become attractive acquisition targets.
Strategic Recommendations for 2026
-
Prioritise raw-material resilience: implement multi-year hedges, establish consigned inventory with key suppliers, and evaluate vertical integration or strategic stakes in critical precursor suppliers where scale justifies it.
-
Shift commercial focus from price-per-unit to productivity-per-hour: measure and sell the TCO delta that your tools deliver, and price according to demonstrable lifecycle value rather than entry price alone.
-
Invest selectively in digital tooling and analytics: even modest telemetry and tool-life modelling can unlock lower warranty costs, higher repeat-purchase rates, and closer OEM partnerships.
-
Target aftermarket and reconditioning as margin lever: tooling regrind, certification, and reman operations can be both defensive and accretive, particularly in markets facing raw-material scarcity.
-
Use M&A to fill capability gaps, not just add capacity: seek targets that add geometry or coating expertise, scale in a strategic geography, or an installed-service capability that accelerates cross-sell.
-
Prepare contract playbooks for 2026 procurement negotiations: include raw-material price-pass clauses, minimum take-or-pay bands, and shared inventory programs to mitigate input-cost volatility.
Closing: How PW Consulting’s Study Supports Your 2026 Playbook
This report synthesises market-scale forecasting, supplier and raw-material risk analysis, and a pragmatic set of go-to-market and operational interventions designed for immediate application. It is specifically calibrated to inform capital allocation and commercial planning for 2026 — from sourcing leaders and plant managers to corporate development and private-equity sponsors. If your team needs the granular regional, product-type, and application-level splits, the proprietary company scorecards, or the full scenario-model workbooks that underpin our recommendations, those datasets and interactive tools are available exclusively in the full PW Consulting report and client portal.
Contact PW Consulting to schedule a briefing with our metal-cutting tools practice; we will walk you through the models, stress scenarios, and opportunity screens that matter to your strategy in 2026.
For detailed analysis of this topic, please visit the official page: Metal Cutting Tools Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com