

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Turbomolecular Pumps Market to Hit USD 2,460M by 2032 at 5.5% CAGR

Turbo Molecular Pumps Market — 2026 Strategic Preview
By PW Consulting — Senior Strategic Advisor / Head of Industry Analysis
This briefing frames the strategic decisions that matter in 2026 for executives operating in or adjacent to the turbomolecular pumps market. Drawing on our PW Consulting market model (base year 2025; historical window 2020–2025; forecast horizon 2026–2032) and primary research across OEMs, integrators and end-users, this preview highlights where value will accrue, where risk is concentrating, and which tactical moves buy time versus create durable advantage. The purpose is to demonstrate technical and commercial depth while reserving core segmented datasets for the full report.
Turbo Molecular Pumps (Turbomolecular Pumps) Market
Market snapshot — macro trajectory you can act on
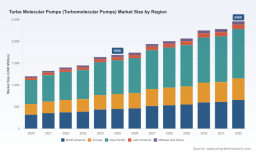
The turbomolecular pumps market reached approximately USD 1.69 billion in 2025 and is forecast to grow at a steady compound annual growth rate of about 5.5% over the 2026–2032 period, reaching roughly USD 2.46 billion by 2032 under our base scenario. After a measured recovery from 2020–2023, the market experienced an acceleration in 2024 and 2025 driven by capacity build-outs in semiconductor and advanced materials processing, and the maturation of higher-throughput maglev and hybrid solutions. Market concentration is meaningful: the top three vendors account for a majority share of revenue, and the top five raise that concentration modestly further — an important structural feature for pricing dynamics, aftermarket opportunity and M&A playbooks.
Turbo Molecular Pumps (Turbomolecular Pumps) Market
Key demand & supply dynamics shaping 2026 decisions
-
Policy and procurement are now technical levers. Energy-efficiency directives in major jurisdictions have already pushed OEMs to deliver lower-wattage drives and intelligent standby modes. Public-sector procurement and large-system integrators are explicitly scoring energy intensity and lifecycle emissions, creating a near-term bid advantage for pump platforms with validated efficiency credentials.
Turbo Molecular Pumps (Turbomolecular Pumps) Market -
Net-zero roadmaps impose multi-year product and capital cycles. Net-zero energy-intensity requirements in Europe and North America extend planning horizons for manufacturers (multi-year compliance windows), forcing choices between incremental efficiency upgrades and more fundamental architecture changes (e.g., wider adoption of magnetic levitation and smart power electronics).
-
Semiconductor and life-science ecosystems are demand multipliers. Policy stimuli and domestic fab programs are sustaining demand for higher pumping speeds and lower base pressures in select submarkets; procurement timelines and qualification hurdles remain long, making early engagement and co-development with strategic customers a high-return activity.
-
Raw-material and component risk is concentrated but manageable. Bearings made from advanced stainless steels such as Cronidur 30 extend service life and lower total cost of ownership, but rare-earth magnet supply risk for maglev rotors is prompting design responses — dual sourcing, magnet-reduced rotor concepts and increased tolerance for lower dysprosium content.
Technology trajectories and product strategy
-
Magnetic levitation versus mechanical bearings. Maglev platforms continue to advance performance, reliability and maintenance economics; however, they introduce different supply-chain exposures (rare-earth magnets, specialized power electronics). Mechanical (oil-lubricated and ball-bearing) architectures remain attractive for certain industrial coatings and retrofit niches because of lower upfront cost and established service networks.
-
Hybrid architectures as a pragmatic bridge. Hybrid designs that combine elements of maglev control with mechanical resilience are emerging as a strategic compromise for customers unwilling to accept full maglev life-cycle trade-offs immediately.
-
Software and systems matter as much as spinning hardware. Digital features — predictive maintenance, remote diagnostics, and intelligent standby — now materially affect procurement choices. OEMs that bundle proven software services alongside validated power-efficiency metrics capture higher aftermarket revenue and improve retention.
Supply chain and cost resilience — what to prioritize now
-
Dual-source critical magnets and bearings. Short-term supplier diversification for rare-earth magnets and advanced stainless alloys is a high-payoff defensive move. Firms should invest in audited second-source qualification and flexible bill-of-materials testing.
-
Vertical or contractual integration for power electronics. Control boards and motor drives are an underappreciated source of differentiation. Securing capacity or preferred pricing for advanced inverter components reduces time-to-market risk for new maglev platforms.
-
Aftermarket and service-first strategies. With replacement cycles longer but service margins higher, developing modular upgrade kits (efficiency retrofits, maglev upgrade paths) and standardized field-service training yields durable margin expansion.
Competitive landscape — who to watch and why
The field is characterized by a mix of established vacuum OEMs and technology-led entrants. The following firms are active players we tracked closely; each has distinct strategic strengths that make them potential partners, competitors or acquisition targets depending on your objectives:
-
Edwards Vacuum — Burgess Hill, United Kingdom — https://www.edwardsvacuum.com. Strengths: broad mechanical turbomolecular ranges (nEXT and STP series) and expanding maglev offerings; notable go-to-market across industrial and analytical segments. Recent visibility at Analytica 2026 underscores channel engagement and field validation efforts.
-
Pfeiffer Vacuum — Aßlar, Germany — https://www.pfeiffervacuum.com. Strengths: comprehensive TURBOPUMPS portfolio spanning mechanical, magnetic and hybrid bearings with strong positioning in high/ultra-high vacuum applications and systems integration capability.
-
Ebara Corporation — Tokyo, Japan — https://www.ebara.com. Strengths: high-throughput maglev turbopumps and strong manufacturing throughput; emphasis on performance and throughput metrics for industrial customers.
-
Leybold — Cologne, Germany — https://www.leybold.com. Strengths: robust TURBOVAC i/iX family tailored to industrial coating and research use-cases; recent product expansion signals continued focus on hardening designs for tough working environments.
-
ULVAC — Chigasaki, Japan — https://www.ulvac.com. Strengths: desktop and mid-range maglev and ball-bearing series with channel focus in Asia; modular product platforms that appeal to OEM integrators.
-
Agilent Technologies — Santa Clara, CA, USA — https://www.agilent.com. Strengths: analytical and research-grade high-vacuum turbo pumps backed by broad customer relationships in instruments and laboratories.
Recent market signals
-
Edwards Vacuum showcased nEXT and STP series alongside T-Station pumping solutions at Analytica 2026 — a signal of continued investment in channel demonstration and turnkey pumping solutions (March 2026).
-
Leybold expanded its TURBOVAC i/iX family with robust variants aimed at industrial coating and research applications — a reminder that ruggedized mechanical platforms retain clear niche relevance (March 2026).
Strategic playbook for 2026 — actions by role
-
OEMs: Prioritize a three-track product roadmap: immediate low-power drive retrofits, medium-term maglev proliferation with supply-chain hardening, and long-term platform redesigns that lower lifecycle emissions. Pair product launches with service bundles to capture recurring revenue.
-
Component suppliers: Move from spot-selling into co-development agreements for bearings and magnet systems. Offer qualification packages and extended warranties to shorten OEM certification cycles.
-
Systems integrators and large end-users: Lock multi-year service contracts and negotiate upgrade credits tied to energy-efficiency performance. Early engagement in OEM R&D roadmaps reduces qualification risk and shortens adoption timelines.
-
Private equity and corporate development teams: Look for tuck-in opportunities in aftermarket services, software-enabled maintenance platforms, and regional service centers to leverage the concentrated market structure and aftermarket margins. Use buy-and-build plays to capture retrofit demand.
What PW Consulting’s full report delivers (practical modules)
-
Detailed market sizing and 2026–2032 forecasts with scenario and sensitivity analyses, including upside and downside demand drivers.
-
Segment-level demand maps (by region, product architecture, and application) and prioritized TAM/SAM/SOM frameworks for commercial planning.
-
Vendor benchmarking with product matrices, technology scorecards, go-to-market positioning, and aftermarket revenue models.
-
Supply-chain risk register (critical components, second-source options, and cost-inflation scenarios) and an implementation playbook for mitigation actions.
-
Commercial playbooks: pricing levers, qualification pathways for semiconductor and life-science customers, RFQ templates, and retrofit upgrade pricing guide.
-
M&A and partnership screening toolkits with candidate lists, valuation guardrails, and integration risk checklists.
Concluding perspective
The turbomolecular pumps market in 2026 is neither nascent nor fully commoditized — it sits in a phase where technical differentiation (bearing architecture, electronics, and software) and regulatory-driven efficiency credentials meaningfully influence commercial outcomes. Firms that move early to secure critical materials, offer service-forward total-cost-of-ownership propositions, and align roadmaps with public-sector energy/CHIPS-driven demand will create asymmetric returns. PW Consulting’s full study provides the granular segment-level maps, vendor scorecards and executable playbooks executives need to prioritize investment and M&A through 2026 and beyond.
To access the complete dataset, supplier scorecards, and the operational playbook referenced above, contact PW Consulting or visit our report portal for licensing and tailored advisory options.
For detailed analysis of this topic, please visit the official page: Turbo Molecular Pumps (Turbomolecular Pumps) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com