

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Physiological Saline Market to Reach USD 8.8B by 2032 at 7.4% CAGR

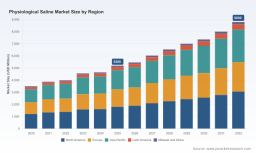
Physiological Saline Market — Strategic Preview for 2026 Decision-Making
As health systems stabilize after recent supply shocks and as clinicians and procurement teams recalibrate sourcing strategies, physiological saline remains one of the most strategically important commodities in acute care and ambulatory settings. PW Consulting’s forthcoming market research, based on a 2025 base year and a 2026–2032 forecast horizon, synthesizes five years of historical performance (2020–2025) and projects forward under multiple scenario assumptions. At the macro level, the market is projected to expand at a compound annual growth rate (CAGR) of 7.4% from 2026 through 2032, progressing from an estimated USD 5,200 Million in 2025 to roughly USD 8,800 Million by 2032. This briefing previews the strategic intelligence in the full report and highlights the direct actions executives should be prioritizing in 2026.
Physiological Saline Market
Why this market matters in 2026
-
Operational leverage: Physiological saline is both a high-volume clinical input and a gateway product that shapes hospital procurement relationships, IV therapy formularies, and supplier contracting cycles.
Physiological Saline Market -
Margin and mix dynamics: While saline itself is a low-margin, high-volume item, packaging formats, proprietary container technologies, and supply reliability create differentiated value capture opportunities.
Physiological Saline Market -
Systemic risk mitigation: The industry’s recovery from prior shortages and the regulatory actions that followed mean supply-chain resilience now influences capital allocation and partnership strategies across hospital systems and manufacturers.
Market snapshot: growth trajectory and structural drivers
From a historical base of approximately USD 3,500 Million in 2020, the global physiological saline market experienced steady recovery and acceleration through 2025, driven by expanded elective care, increased outpatient hydration and infusion therapy utilization, and stabilization of manufacturing capacity. The market scale reached an estimated USD 5,200 Million in 2025. Under PW Consulting’s central forecast—reflecting demand normalization, moderate price pressure, and investment in non-PVC packaging—the market is expected to grow to about USD 5,464 Million in 2026 and to roughly USD 8,800 Million by 2032, representing a 7.4% CAGR over the forecast period. These headline figures underscore a resilient, mid-single-digit-to-low-double-digit growth market that rewards both scale and operational excellence.
What the report contains (practical, action-ready intelligence)
-
Executive dashboards: Clear KPIs for procurement, manufacturing, and commercial leaders—capacity utilization thresholds, reorder point frameworks, and packaging ROI models tailored for 2026 procurement cycles.
-
Demand modeling: Scenario-based demand curves that incorporate clinical utilization trends, outpatient infusion expansion, and potential episodic demand shocks—presented with sensitivity analyses to inform buffer-stock policies.
-
Supply map and risk heatmap: Granular supplier mapping, contract tenure analysis, and geographic fragility indices to guide near-term dual-sourcing or stockpiling decisions.
-
Commercial playbooks: Tender-winning approaches by region and channel, value-based contracting constructs for hospital networks, and pricing levers informed by reimbursement code dynamics.
-
Manufacturing and packaging assessment: Capex prioritization matrix for converters and OEMs, cost trade-offs between PVC vs. non-PVC containers, and guidance on lifecycle management of sterile fill lines.
-
M&A and partnership screening: Criteria-driven targets for bolt-on manufacturing capacity, regional distribution partnerships, and technology licensing opportunities.
-
Regulatory and reimbursement tracker: Up-to-date mapping of critical codes, policy changes, and shortage declarations that materially affect unit economics and procurement negotiation posture.
Competitive landscape: what leading firms are doing
The physiological saline market remains strategically contested by a set of established injectable and IV-fluid specialists. Leading manufacturers emphasize reliability, container innovation, and integrated hospital solutions rather than volume-only competition. Key strategic positions observed in the market include:
-
Baxter International: A long-standing leader in IV fluids, Baxter’s Viaflex and Viaflo systems continue to anchor hospital procurement lists. Recent commercial expansion initiatives in early 2026 indicate a push to broaden market access and reinforce supply commitments—moves that increase competitive pressure in markets where buyers prioritize single-supplier simplicity and validated logistics.
-
B. Braun Melsungen: With a portfolio built around extracellular fluid replacement in established container formats, B. Braun pursues a steady combination of clinical education and channel depth to defend share in hospital formularies where clinical familiarity and product interchangeability matter.
-
Fresenius Kabi: The company’s Freeflex bag strategy and its March 2026 distribution partnership reinforce a distribution-led expansion play. Fresenius is optimizing route-to-market strength to capture growth in markets with fragmented distribution and tender-driven procurement.
-
ICU Medical / Otsuka collaborations: Non-PVC/non-DEHP container offerings and joint manufacturing arrangements reflect a differentiation strategy pitched at hospital systems and procurement teams seeking compliance with emerging patient-safety and sustainability standards.
-
Grifols & Laboratorios Grifols: Positioning around polypropylene bags and plasma-donation applications anchors their relevance in integrated hospital-plasma ecosystems, where cross-selling saline for donation and inpatient use can create channel synergies.
-
Otsuka Pharmaceutical and AdvaCare: These players focus on regional partnerships and branded irrigation/indication-specific products, exploiting agility to serve targeted clinical use-cases and specialized channels.
Across the landscape, the market exhibits a degree of concentration around several incumbent players who control a majority of supply—making scale, validated quality systems, and logistics reliability decisive competitive advantages. The full report provides a deeper assessment of partner fit and competitive risk by scenario; those sub-segment tables and exact share estimates are reserved for the complete study.
Regulatory and reimbursement context shaping 2026 choices
-
Shortage resolution: The FDA formally declared the nationwide shortage of 0.9% sodium chloride injections resolved in August 2025. That regulatory milestone has immediate implications for inventory policies—hospitals that kept elevated safety stocks are now reviewing target levels, and manufacturers are recalibrating production schedules toward optimal utilization rather than emergency surge capacity.
-
Billing and reimbursement: HCPCS code J7030 (infusion normal saline solution, 1000 cc) remains a key billing code; Medicare reimbursement for this code historically averages in a low-single-digit-dollar range per unit depending on setting. Reimbursement nuance continues to affect how providers price outpatient infusion services and how suppliers justify value-added service charges.
-
Infusion service coding: Changes to CPT codes relevant to pre-packaged normal saline fluids (including revisions effective September 2025) affect documentation and reimbursement workflows for hydration services—an operational detail procurement teams must monitor to avoid unfavorable margin shifts in third-party clinic contracts.
Strategic playbook for 2026 — prioritized actions
-
Secure tiered supply: Immediate steps should include establishing multi-year supply agreements with clear capacity guarantees, indexed price collars, and accelerated fulfillment clauses for surge events. Where possible, negotiate inventory consignment or vendor-managed inventory (VMI) to reduce working capital.
-
Invest selectively in packaging: Prioritize conversion to non-PVC containers where clinical or regulatory trends favor them, but adopt a staged approach—pilots in high-volume hospital systems before large-scale capital deployment.
-
Pursue distribution partnerships: For manufacturers seeking market expansion, target partners with tender-execution strength and hospital contracting relationships. Distribution agreements can accelerate adoption without the time-to-market cost of new local manufacturing.
-
Refine commercial models: Align tender bids and private-label propositions with hospital reimbursement realities. For integrated providers, consider bundled care agreements that include infusion services and supply to capture downstream value.
-
Screen M&A targets for resilience and scale: Look for regional production sites with experienced sterile-fill capabilities, plus logistic assets that reduce lead times in priority geographies.
How executives should use this brief and next steps
This preview outlines the strategic imperatives PW Consulting anticipates will most influence decisions in 2026. The full market study contains the granular modeling, supplier scorecards, tender-performance benchmarks, and detailed segment-level estimations necessary to operationalize these recommendations. To protect competitive sensitivity and ensure consultative value, we intentionally withhold sub-segment-level tables and certain regional share breakdowns from this summary; the complete report includes those analytics together with an interactive decision-support toolkit.
If your planning cycle for 2026 encompasses procurement commitments, M&A scoping, or manufacturing investments, we recommend the following immediate next steps: obtain the full PW Consulting Physiological Saline Market report for supplier- and channel-level insight; run a rapid internal sourcing review using our scenario templates; and convene a cross-functional task force (procurement, clinical leads, manufacturing, and finance) to operationalize the priority playbook above.
Closing thought
Physiological saline may read as a commodity on the surface, but its strategic implications in 2026 are far from trivial. The market’s steady growth—anchored by an estimated USD 5.2 Billion base in 2025 and an expected rise to approximately USD 8.8 Billion by 2032 at a 7.4% CAGR—creates opportunities for players who combine scale, supply resiliency, and commercial innovation. PW Consulting’s full report converts these macro trends into executable choices; this preview is designed to orient leadership discussions and highlight where rapid action can lock in advantage in the year ahead.
For detailed analysis of this topic, please visit the official page: Physiological Saline Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com