

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
Heavy Bag Stands Market — Strategic Preview for 2026 Decision Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a focused, practice-oriented preview of our new Heavy Bag Stands Market study — tailored to equip executives, product leaders, and corporate strategists for high-stakes decisions in 2026. This briefing highlights the report’s strategic value, the macro trajectory of the market, competitive fault lines, and the practical intelligence you can deploy immediately. To preserve the commercial value of proprietary segmentation and scenario outputs, select granular splits are intentionally withheld from this preview; the full dataset and model access are available on our report landing page.
Heavy Bag Stands Market
Why this study matters in 2026
The heavy bag stands market sits at the intersection of home fitness expansion, commercial gym refurbishment cycles, and a resurgent combat-sports culture. Our 2025 base-year market assessment values the global market at approximately 103.62 Million USD, with our forward-looking model projecting growth to roughly 139.0 Million USD by 2032 driven by a steady compound annual growth rate (CAGR) of 4.12% across 2026–2032.
Heavy Bag Stands Market
For 2026 corporate planning, this translates into three immediate imperatives:
Heavy Bag Stands Market
- Focus resource allocation on modular, serviceable product architectures that balance compact home-use designs with gym-grade durability.
- Prioritize channel strategies that harmonize direct-to-consumer e-commerce with selective trade-partner relationships in commercial fitness verticals.
- Adopt supply-chain playbooks that mitigate steel-price and logistics volatility while preserving warranty and safety credentials that buyers value.
What the report delivers — practical, transaction-ready intelligence
This market study is built for decision velocity. It is not a high-level brochure; it is a toolkit for commercial execution. Highlights include:
- Market sizing and validated demand trajectories (2020–2025 historical series; 2026–2032 forecast) with scenario-based sensitivities tied to macro inputs such as steel commodity pricing and gym-capEx cycles.
- Commercial segmentation frameworks (product type, distribution channel, and application) that map to buyer personas and procurement drivers — presented as action matrices for product managers and channel leads.
- Unit economics and cost build-ups for reference designs, including BOM sensitivity tables for key tubing and base components commonly used in heavy bag stands.
- Go-to-market playbooks: prioritized channel mixes by go-to-market maturity, sample pricing ladders, promotion calendars for seasonal peaks, and partnership templates for gym chains and fitness event sponsors.
- Supply-chain and manufacturing diagnostics: supplier archetypes, nearshoring vs. offshore break-even templates, and inventory buffers tuned to typical lead times in metal fabrication and powder-coating operations.
- Regulatory and warranty benchmarking: a compliance checklist for safety standards and warranty structures that align with premium positioning in North American and developed-market gyms.
- M&A and product-portfolio scorecards: target criteria and valuation heuristics for roll-up strategies in a fragmented supplier landscape.
Market structure and competitive dynamics — what to watch
The heavy bag stands market is structurally fragmented, with a modest combined share held by the largest manufacturers. Our concentration metrics indicate that the top three players account for a minority share of the market, and the top five still leave substantial share for mid-tier and regional suppliers. This fragmentation creates room for consolidation plays, but any M&A strategy must reckon with variant product architectures, warranty burdens, and localized distribution networks.
Key competitors profiled in the study — each illustrative of a strategic archetype — include:
- Titan Fitness (United States) — a value-to-durability player emphasizing adjustable steel-post designs and reinforced baseplates suited for both home users and light commercial settings.
- Ringside (United States) — a legacy combat-sports brand offering both wall-mounted hardware and free-standing frames with add-on modules such as speed-bag platforms, positioning them in professional training channels.
- Prolast / PROFIGHTSHOP (United States) — heavy-duty, professional-grade stands (including multi-bag frames) that underpin gym and academy purchasing decisions and place emphasis on warranty and lifecycle service.
- Everlast (United States) — a global sports brand that integrates adjustable heavy bag stands into broader equipment portfolios, leveraging brand recognition and distribution reach.
- Century (India) — a regionally strong manufacturer that showcases how localized production and cost-competitive tubular-steel construction can capture latent demand in emerging markets.
- Outslayer (United States) — premium, “made-in-USA” heavy-duty stands built for very high-capacity bags and long warranty tenures, an archetype for premium positioning.
- Balazs (United States) — nimble specialist serving niche demand with universal single-station stands and mounting hardware for bespoke installations.
Each of these firms illustrates different go-to-market vectors: premium domestic manufacturing with long guarantees; legacy brands bundling hardware into broader packages; modular multi-bag systems targeted at academies; and cost-focused regional manufacturers targeting price-sensitive home users. Our competitive heat maps and product-feature parity matrices — detailed in the full report — show where value-based differentiation or technical superiority deliver the highest margin capture.
Supply-side realities and product design signals
From an engineering and procurement perspective, the market’s baseline product architecture is consistent: powder-coated steel tubing with reinforced bases engineered to support a spectrum of bag weights. Adjustable freestanding stands that reach near 8'6" are now commonplace, addressing both adult training and varying bag profiles. Premium manufacturers extend structural warranties of 10–15 years and emphasize domestic fabrication quality as a differentiator for commercial buyers.
Three product design themes emerge as investment priorities in 2026:
- Modularity — frames and add-on modules (speed-bag platforms, extra pegs, anchoring systems) that allow one SKU to target multiple buyer personas with minimal production complexity.
- Serviceability — designs that trade marginal manufacturing cost for lower lifetime-support costs (e.g., replaceable wear plates, standardized fasteners), which is attractive to gym procurement teams focused on total cost of ownership.
- Compact-pack logistics — folding or disassemblable frames that reduce freight and last-mile costs for DTC channels without compromising perceived robustness.
Demand-side and channel playbook
Demand is being pulled by two parallel trends: the maturation of the home-fitness consumer (seeking durable, space-efficient solutions) and a steady rebound of professional training venues investing in equipment refreshes. This duality requires manufacturers to run bifurcated strategies: a premium, service-backed offer for commercial buyers and a value-engineered SKU set for e-commerce-first households.
Effective 2026 channel strategies we recommend:
- Channel tiering: dedicated commercial account managers and extended warranty and spare-parts services for gym chains versus optimized DTC packaging, online content, and cross-sell to home-fitness ecosystems.
- Trade and event activation: leverage industry exhibitions and combat-sports showcases to demonstrate durability claims and secure volume contracts — note that trade events in 2026 remain a productive channel for business development.
- Partnerships with equipment-as-a-service operators: explore rental or subscription models for boutique studios where capital light acquisition is a constraint.
Regulatory, cost, and risk considerations
Key risk vectors that materially affect 2026 outcomes include raw material price volatility (notably steel tubing), warranty claim rates, and logistics lead-time disruptions. Our report quantifies the sensitivity of gross margin to ±10% swings in steel input costs and offers hedging and supplier diversification playbooks to stabilize unit economics.
Safety and warranty benchmarking shows that premium US-made product offers are differentiated by 10–15 year warranty commitments and tighter safety testing — a defensible positioning for B2B procurement but costlier to sustain in a low-margin DTC play.
What you can do in the next 90 days
For senior leaders preparing 2026 budgets and growth plans, three executable moves are high-impact and low regret:
- Run a SKU rationalization using our product feature-value matrix to identify 1–2 high-margin configurable SKUs that can be rapidly brought to market or re-priced for improved profitability.
- Initiate supplier re-qualification for critical tubing and baseplate components, including a dual-sourcing pilot to limit single-supplier exposure to price and lead-time shocks.
- Test a hybrid channel pilot that bundles a service warranty extension for gym customers, and measures CAC and payback period against pure DTC campaigns.
Closing — what this preview leaves out (and why)
This preview provides strategic lenses, competitor archetypes, macro forecasts, and immediate playbooks intended to accelerate decision-making in 2026. To protect the commercial utility of our granular research — including detailed regional & application splits, SKU-level price curves, buyer personas, and downloadable financial models — we intentionally withhold certain granular tables from this public preview. Those datasets translate our 4.12% CAGR forecast and 2025 market base into executable financial scenarios and are available through the full report package.
For market-entry strategies, M&A screening, or a tailored workshop that applies these findings to your product roadmap or channel strategy, contact PW Consulting for priority access and a bespoke briefing.
For detailed analysis of this topic, please visit the official page: Heavy Bag Stands Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
R134A Market to Reach USD 246.2 Million by 2032; 4.3% CAGR (2026-2032) — PW Consulting
By pmarketresearch, 2026-07-30
R134A Refrigerant Market: Strategic Implications for 2026 Decision‑Makers
PW Consulting’s latest R134A Refrigerant Market study (base year 2025; historical 2020–2025; forecast 2026–2032) is designed as an operational intelligence product for executive teams making allocation, product, and regulatory-compliance decisions in 2026. At the headline level, the global market has expanded steadily from the early 2020s and—under our central projection—continues to grow through the 2026–2032 forecast window at a compound annual growth rate of approximately 4.3%. Using 2025 as the reporting baseline (currency: USD, revenue unit: Million), the study supplies both the macro sizing and the scenario-driven projections you need to stress-test strategy under competing regulatory and supply scenarios.
R134A Refrigerant Market
Why this study matters in 2026
- Regulatory inflection points are now operational. Several U.S. rules affecting HFC import, labeling, and permitted uses execute or expand in 2025–2026, materially changing compliance and commercial pathways.
- Legacy-service demand (aftermarket, refrigeration servicing, and retrofits) remains a durable revenue pool even as new‑equipment specification shifts to lower‑GWP alternatives. Firms that balance legacy supply with transition solutions capture asymmetric margin opportunities.
- Upstream feedstock volatility and reclamation rules change cost and availability assumptions for producers and distributors; procurement strategy and working-capital models must be updated accordingly.
- Competitive positioning is fragmented: the market is not a concentrated oligopoly. This creates space for fast followers, niche providers, and technical-service specialists to scale quickly if they execute a clear go‑to‑market plan.
Key market dynamics shaping decisions in 2026
- Regulatory acceleration: U.S. regulatory actions enacted in 2025–2026 increase the compliance burden for HFC suppliers and reclaimers. New labeling and allowance requirements, technology transition restrictions, and proposals to extend reclamation and emissions controls to larger systems mean that regulatory readiness is a commercial differentiator. These actions shift value toward compliant reclaimers, retrofit-technology providers, and suppliers who can demonstrate traceable, labeled product flows.
- Transition pathways and retrofit economics: A two-track technical reality exists: new equipment increasingly specifies low‑GWP refrigerants, while existing installed bases require safe, cost-effective retrofit or ongoing service with legacy R134A. Recent retrofit technology developments allow staged transitions that reduce replacement costs for fleet owners and large refrigeration operators—creating an addressable aftermarket that remains economically attractive for several more years.
- Supply and cost pressures: Upstream fluorochemical feedstocks and intermediary chemistry prices have shown periodic upward pressure, putting margin stress on spot sellers and unhedged producers. At the same time, reclaiming and recycling represent both a compliance necessity and a margin-preserving lever for market participants.
- Commercial segmentation—buyers and channels: Demand originates from mobile A/C servicing, commercial refrigeration, and a range of industrial uses. The service channel dynamics—distributors, reclaimers, OEM service networks, and aftermarket specialists—are evolving quickly as regulation, product specs, and retrofit options shift.
Competitive landscape: who matters and what they are doing
The competitive map is defined by legacy fluorochemical producers, integrated chemical majors, regional manufacturers, and specialists in reclaim and retrofit technologies. Leading names in the space include multinational chemical companies with legacy R134A brands and dedicated aftermarket propositions, several large Chinese and Indian producers, and a set of engineering-led players focused on retrofit and low‑GWP migration technologies.
R134A Refrigerant Market
- Incumbent majors continue to play a dual role—maintaining legacy supply for the service market while commercializing low‑GWP alternatives and retrofit pathways. Recent strategic moves include alliance agreements and product expansions that increase the commercial footprint of lower‑GWP portfolios.
- Regional manufacturers are leveraging production scale and local distribution to defend and extend market share in price‑sensitive channels. Their cost position makes them critical partners for distributors and OEM remanufacturing operations.
- Retrofit and reclamation specialists are becoming transactional gatekeepers: the firms that can certify reclaim volumes, apply compliant labeling, and offer retrofit kits will capture a rising share of aftermarket economics.
Notable recent developments—illustrative of the competitive dynamic—include industry announcements of retrofit technology that facilitate safe conversion of legacy mobile A/C systems and commercial arrangements between major refrigerant producers to expand lower‑GWP portfolios. These moves underscore a market where technology partnerships and channel alignments are as important as raw supply.
R134A Refrigerant Market
Market structure: concentration and opportunity
The R134A market is characterized by meaningful fragmentation among producers and sellers. The largest few players do not dominate to the extent seen in some chemical markets; top-three shares and top-five shares point to a landscape where mid‑tier and regional players retain significant collective power. For decision‑makers this means that targeted M&A, selective capacity investments, or well-timed commercial partnerships can materially shift competitive standing within a short strategic window.
Strategic imperatives for 2026
Based on our integrated market model and regulatory scenario analysis, we recommend the following prioritized actions for companies engaged in or adjacent to the R134A ecosystem:
- Adopt a dual‑track product strategy: Retain assured legacy supply and aftermarket servicing capabilities while accelerating commercialization of retrofit technologies and low‑GWP alternatives. Create commercially distinct offers for “service‑grade” R134A and transition‑grade solutions.
- Invest in compliant reclamation and labeling capabilities: The 2026 labeling and reclaim rules create a premium on traceability. Firms that can certify volumes and demonstrate compliant chain‑of‑custody will command better access to regulated channels and preferred supplier status with large end users.
- Hedge feedstock and diversify procurement: Upstream cost volatility is non‑trivial; strategic procurement, forward contracting, and selective vertical integration can protect margins in 2026 and beyond.
- Forge OEM and channel partnerships: Close alignment with OEMs, service networks, and large refrigeration fleet operators accelerates acceptance of retrofit kits and certified low‑GWP replacements—crucial for scaling transition revenues.
- Pursue targeted M&A and tech partnerships: Prioritize acquisitions that add reclaim capacity, retrofit IP, or regional logistical muscle. These assets provide tangible synergies and shorten the path to compliance‑ready commercial models.
- Scenario planning and stress testing: Run at least three commercial scenarios in 2026 planning cycles—baseline policy trajectory, accelerated phase‑down, and supply‑shock—to stress-test headroom on price, margin, and working capital.
What PW Consulting’s full report delivers (operational detail)
- Market sizing and forecasting model (historical 2020–2025; forecast 2026–2032) with downloadable data tables and interactive scenario toggles reflecting regulatory and feedstock shocks.
- Regulatory-impact matrix that quantifies near‑term compliance costs, operational changes for reclaimers, and the commercial effect of labeling and technology transition rules.
- Competitor playbooks and vendor profiles covering legacy producers, regional manufacturers, and retrofit/reclaim specialists—assessing capabilities, channel access, and strategic intent.
- Supply‑chain risk heatmap and procurement playbook that translates feedstock indicators into procurement triggers and inventory policies.
- Commercial go‑to‑market playbooks for OEM partnerships, retrofit commercialization, and aftermarket channel optimization.
- M&A shortlist and valuation priors for bolt‑on targets (reclaimers, retrofit IP holders, regional distribution platforms).
- Executive dashboard with key leading indicators to monitor through 2026—policy milestones, feedstock indices, reclaim volumes, and aftermarket demand signals.
Note: This preview intentionally omits the granular regional and application split tables and specific sub‑segment price curves that are included in the full study. Those core data layers are provided in the premium dataset and interactive model because they are the actionable elements procurement, commercial, and M&A teams rely on to execute in 2026.
How to use this intelligence in your 2026 planning cycle
- Use the report’s scenarios to set guardrails for capital allocation and inventory policy aligned with the most probable regulatory pathway.
- Prioritize short-cycle initiatives that protect aftermarket margins (licensed retrofit kits, certified reclaim programs) while sequencing longer-term investments (capacity upgrades, low‑GWP production) against policy clarity.
- Leverage the competitor playbooks to identify white‑space partnerships—e.g., co‑branding retrofit solutions with distributors or acquiring regional reclaimers to secure compliant feedstock.
PW Consulting’s R134A Refrigerant Market study is built to be operational: not just descriptive market intelligence, but a playbook for action in 2026. For procurement directors, commercial heads, and strategy teams, the combination of our market model, regulatory-impact quantification, competitive playbooks, and M&A priors forms the evidence base needed to make high‑confidence decisions in a fast‑moving regulatory and technical environment.
To access the full dataset, interactive models, and the withheld regional/application level intelligence that will inform precise sourcing, pricing, and M&A decisions, contact PW Consulting or visit our reports portal for licensing and bespoke advisory options.
For detailed analysis of this topic, please visit the official page: R134A Refrigerant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 3D Laser Scanners Market to Reach USD 346.04 Million by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-30
3D Laser Scanners Market — Strategic Outlook for 2026 Decision‑Makers
As organizations reassess capital allocation, digitalization roadmaps, and field operations for 2026, 3D laser scanning is no longer a niche enabler: it is a capabilities backbone across surveying, manufacturing, construction, forensics, and cultural‑heritage projects. PW Consulting’s new market study synthesizes macro trajectory, competitive dynamics, standards evolution, and procurement playbooks designed to inform high‑stakes decisions in the coming 12–36 months. This preview explains why the study is strategically material for 2026 planning while preserving the proprietary, segment‑level intelligence that we reserve for subscribers.
3D Laser Scanners Market
Macroeconomic Trajectory: an expanding but heterogeneous market
Anchored on a 2025 base year, the 3D laser scanners global market is projected to grow at a compound annual growth rate (CAGR) of 6.98% over the 2026–2032 forecast window. On a headline basis this trajectory accelerates the market from mid‑hundreds of millions in 2025 toward the high‑hundreds by 2032 (all values expressed in Million USD). That rate reflects steady expansion driven by broader adoption of as‑built capture in construction, rising demand for metrology‑grade portable scanners in manufacturing, and the scaling of mobile and airborne LiDAR for infrastructure and environmental mapping.
3D Laser Scanners Market
Two structural features matter for decision‑makers. First, the market remains fragmented: the three‑firm and five‑firm concentration ratios are relatively low, indicating many regional and niche specialists still compete meaningfully alongside global OEMs. Second, growth is uneven across use cases and form factors — some pockets are maturing quickly, others are early‑adopter territory — which creates both upside opportunities and procurement complexity when defining specifications and TCO expectations.
3D Laser Scanners Market
Why this study matters for 2026 strategic decisions
-
CapEx and procurement timing: Our analysis aligns vendor roadmaps, firmware and certification cycles, and the likely price curve so procurement teams can decide whether to accelerate purchases before major product refreshes or defer to secure improved value.
-
Vendor selection and risk mitigation: With a fragmented supplier base, vendor choice critically affects long‑term serviceability and data traceability. The study maps qualifications, metrology certifications, and calibration ecosystems to reduce operational risk.
-
Operational design: For field managers, we translate scanning productivity and post‑processing throughput into project‑level labor and software cost drivers, enabling realistic budgeting for large scan programs.
-
Regulation and admissibility: For forensic, infrastructure, and regulated sectors, the report aligns scanner capabilities to emerging standards and evidence‑admissibility frameworks, helping legal and compliance teams preempt challenges.
What the full report contains (practical, executable content)
-
Market sizing and forecast model (2020–2032 base), including scenario analysis that isolates high‑adoption and constrained‑growth outcomes relevant to procurement cycles in 2026.
-
Vendor scorecards that compare product classes across metrology performance, calibration traceability, ecosystem services, global support footprint, and upgrade latency.
-
Procurement playbook: decision trees for CAPEX vs. OPEX choices, tradeoffs between handheld, terrestrial, mobile and airborne platforms for common program archetypes, and contractual clauses to secure firmware/driver update commitments.
-
Project costing templates that translate scan density, point cloud volume, and post‑processing time into labor and storage budgets — calibrated to our primary research across 2020–2025 projects.
-
Regulatory alignment annex: practical checklists tied to OSAC, ISO 10360‑13, ISO 17123‑9, VDI/VDE standards, and laboratory accreditation expectations for traceability and forensic acceptance.
-
Investment briefings for corporate development teams focusing on consolidation targets, technology integration acquirers, and ecosystem plays around software and analytics for scanned data.
Competitive landscape — who matters and why
The vendor ecosystem combines global platform leaders, metrology‑grade specialists, and agile challengers. The full study profiles each major OEM and a curated set of regional challengers to help readers map fit‑for‑purpose partners.
-
Creaform: A recognized leader in portable metrology scanners, Creaform’s recent refresh of its handheld lineup underscores a strategy focused on ISO‑aligned certifications and vertical integration for inspection workflows. Their emphasis on handheld metrology aims at manufacturing and quality control applications where traceable accuracy and service assurance command premium pricing.
-
Artec 3D: With iterative optics and metrology certifications for its portable offerings, Artec is signaling a push to bridge high‑accuracy object capture and site documentation. Their 2026 Spider II update reflects a product strategy built around certified accuracy and measurement stability — important for forensic and reverse‑engineering use cases.
-
FARO Technologies: FARO continues to invest in firmware and processing workflows for its Focus line, lowering operational friction in field‑to‑deliverable pipelines. Firmware updates and cloud integration reduce lifecycle costs for repeat installers and large project contractors.
-
Hexagon, Leica, Trimble, RIEGL, Topcon: These legacy players are differentiated by broad systems portfolios (GNSS, total stations, software), channel depth, and service networks. Their competitive moat lies in integrated workflows for surveying and infrastructure projects where end‑to‑end solutions simplify procurement and support long engagement cycles.
-
China‑based OEMs (SHINING 3D, SCANOLOGY, 3DMakerpro, Revopoint, others): These vendors are expanding rapidly on price‑performance and targeted certifications. Select models now come with accredited calibration labs and ISO/IEC 17025 traceability, narrowing the historical gap with established metrology incumbents and offering high value for mid‑market customers.
Recent vendor activity in late 2024–early 2026 — including product refreshes, firmware improvements, and new LiDAR introductions — materially affects procurement timing and upgrade planning. The full report links each product move to risk and opportunity matrices for enterprise buyers.
Regulatory and operational dynamics that will shape adoption
Standards and accreditation are a central theme for 2026. OSAC guidance for forensic scene capture, ISO 10360‑13 for handheld measurement verification, and persistent reliance on ISO 17123‑9 for terrestrial performance evaluation collectively raise the bar for traceability. VDI/VDE frameworks and ISO/IEC 17025 laboratory accreditation are increasingly required by customers who must demonstrate defensible measurement chains. Our analysis explains how to operationalize these requirements — from vendor SLAs to in‑house reverification schedules — without ballooning program costs.
On cost drivers, our primary research shows that project size and complexity dominate total program spend: labor for data capture and processing, not hardware list price alone, becomes the marginal cost for scaled scanning programs. This is important because many procurement exercises focus excessively on device CAPEX while underweighting lifecycle labor and cloud storage costs.
Practical recommendations for 2026 procurement and investment
-
Adopt a capability‑based specification: define accuracy, throughput, and certification requirements by use case rather than by platform type. This reduces the risk of over‑specifying and paying for unused precision.
-
Time purchases around vendor refresh cycles: minor firmware updates can meaningfully improve uptime and processing speed; major optical or sensor revisions justify delaying large CAPEX if operational needs permit.
-
Procure calibration and reverification services as an explicit line item: ensure traceability commitments and SLAs are contractually enforceable to preserve evidentiary value and resale considerations.
-
Model total cost of ownership over a 5‑year horizon that includes labor scaling, cloud/compute, and the risk of obsolescence for niche tools in favor of modular ecosystems.
-
Consider software‑centric plays: vendors that lock in data workflows via analytics or SaaS post‑processing can shift value from hardware to recurring revenues — a factor for both strategic sourcing and M&A strategy.
How to use the full PW Consulting study
This article presents the strategic contours you need to prioritize decisions in 2026: growth rate, market structure, standards pressures, and vendor dynamics. For executable procurement templates, vendor scorecards, and the proprietary segment‑level intelligence that maps device classes to specific industry use cases and regional demand patterns, please consult the full report. We intentionally keep granular splits and certain segment‑level metrics exclusive to the subscription product to preserve the actionable insight you need to operationalize these recommendations.
PW Consulting’s 3D Laser Scanners Market study is designed for chief procurement officers, operations leads, legal/compliance counsels in regulated industries, and M&A/strategy teams targeting the sensor and geospatial value chain. Armed with the full dataset and playbooks, organizations can convert the market’s steady CAGR and product‑cycle signals into concrete sourcing, deployment, and investment actions for 2026.
For detailed analysis of this topic, please visit the official page: 3D Laser Scanners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Thymidine Market to Reach USD 110.3 Million by 2032 at 3.1% CAGR
By pmarketresearch, 2026-07-30
Thymidine Market 2026 Strategic Preview — What Leaders Must Know
Executive summary
As PW Consulting’s senior industry analyst, I present a concise, decision-focused preview of our full Thymidine Market research. The global market for thymidine — a foundational nucleoside used across antiviral drugs, nucleotide intermediates, DNA synthesis reagents and diagnostic kits — registered steady expansion through the 2020–2025 historical window and reached USD 89.2 Million (base year 2025). Our modelling points to a moderate but reliable compound annual growth rate (CAGR) of 3.1% across the 2026–2032 forecast horizon, taking the market to roughly USD 110.3 Million by 2032.
Thymidine Market
This briefing demonstrates the types of strategic intelligence embedded in the full report: an actionable view of demand drivers, supply-side structure and competitive positioning that matter for 2026 planning cycles. Per the “trailer” principle, we intentionally highlight implications and decision levers while withholding the granular segment-by-segment tables and proprietary supplier scorecards reserved for subscribers.
Thymidine Market
Why 2026 matters: a convergence of clinical, regulatory and supply shocks
Several forces converge as companies set strategy for 2026:
Thymidine Market
- Regulatory catalysts: Late-2025 and early-2026 regulatory events have raised the profile of thymidine-linked value chains. Recent approvals and authorisations for a therapy targeting thymidine kinase 2 deficiency create a credible pathway for elevated demand for GMP-grade nucleoside intermediates. Early commercial availability in core markets is expected to materialize in the first half of 2026, changing order patterns for specialized intermediates.
- Supply concentration and lead times: The upstream supply base is concentrated — the top producers control a material share of global volume — which has already manifested in extended lead times and spot-price volatility in 2024–2025. This structural feature amplifies the supply risk premium for buyers and creates arbitrage opportunities for new entrants or capacity expanders.
- Demand composition shifts: While historically driven by established antiviral APIs and research reagents, demand is becoming more bifurcated: high-purity, regulatory-compliant product for biopharma and cell therapy on one side; and cost-sensitive, fermentation-derived thymidine for diagnostics and bulk intermediates on the other. These are distinct commercial plays with different margin profiles and qualification timelines.
Market dynamics — what the numbers mean for strategy
Three implications from the macro trajectory (steady growth, moderate CAGR):
- Predictability with pockets of volatility. A 3.1% CAGR implies a reliable baseline market expansion but does not eliminate episodic supply shocks or one-off demand spikes tied to drug launches or regulatory pathways. Procurement strategies should therefore combine long-term contracts with tactical buffers.
- Segmentation drives margin dispersion. The aggregate market figure masks meaningful variation in customer willingness to pay and supplier margin expectations across GMP-grade vs. research-grade products, and between chemically synthesized and fermentation-derived materials. Strategic positioning should prioritize clarity on which segment a company will serve.
- Scale matters, but so does quality certification. Economies of scale will favor larger producers for commodity volumes, while regulatory-compliant, small-batch capabilities will be the gatekeeper for capturing upstream biopharma demand tied to novel therapeutics.
Competitive landscape — company-level takeaways
Below is a strategic snapshot of the leading and notable suppliers whose capabilities shape the market today. These notes synthesize firm profiles, public positioning and observable strategic moves; the full report contains calibrated strength/weakness matrices and supplier scorecards.
- Lonza Group (Switzerland) — A global reference for high-purity, GMP-grade thymidine and nucleotide intermediates. Lonza’s strength is trust in regulated supply chains and bespoke manufacturing for cell-therapy and biopharma customers. For buyers who require validated, audited sources and long-term supply reliability, incumbents with Lonza-like profiles reduce qualification risk but command a premium.
- Carbopharm GmbH (Austria) — Positioned largely as a laboratory and industrial supplier providing standard-grade thymidine. Their client base is research institutions and industrial synthesis users. Carbopharm is a strategic partner for organizations prioritizing breadth of catalog and steady availability over bespoke GMP services.
- ST Pharm Co., Ltd. (South Korea) — Serves antiviral and biopharma intermediate markets; their regional advantages and technical know-how make them attractive partners for Asia-Pacific vaccine and antiviral developers. Expect them to pursue tightened regional partnerships and potential capability upgrades to capture higher-value GMP work.
- Zhejiang NHU Co., Ltd. (China) — Notable for dual-route manufacturing (fermentation and chemical synthesis). This operational flexibility gives NHU a cost and capacity advantage for DNA synthesis reagents and large-volume intermediates, as well as resilience to raw-material feedstock swings.
- Zhejiang Xianfeng Science Technology; Anhui Golden Sun Biopharmaceuticals; Hebei Anminuo; Ducheng; Chengzhi (China) — Together, these firms form a robust supply cluster that competes on cost, volume and responsiveness. Several have invested in fermentation platforms to reduce unit costs. For global buyers, these suppliers are attractive for non-GMP or bulk needs but often require additional qualification steps, audits and governance protocols when serving regulated biopharma customers.
Strategic playbook for 2026 decision-makers
Based on our scenario modelling and supplier intelligence, here are prioritized actions for different stakeholders heading into 2026 planning cycles.
- For CPOs and procurement leads: Implement a three-tier sourcing approach — secure at least one audited GMP supplier for critical pathways, maintain a cost-effective secondary supplier for non-regulated volumes, and contract a contingency partner in a different geography to mitigate geography-specific disruptions. Re-negotiate lead times and consider inventory as insurance for key launch windows.
- For manufacturing and technical teams: Accelerate supplier qualification timelines for fermentation-derived intermediates if sustainability and cost are strategic priorities. Invest in analytical method harmonisation to shorten qualification cycles across suppliers.
- For corporate development and investors: Seek bolt-on assets that add either GMP-compliant capacity or unique fermentation IP. M&A targets should be evaluated against a matrix that combines compliance readiness, customer concentration and technical pathway differentiation.
- For biotech and pharma portfolio managers: Map your drug development milestones against supplier qualification lead times. For therapies dependent on thymidine-related intermediates — especially therapies tied to regulatory tailwinds — early supplier engagement and co-investment in capacity can be deal-accelerating.
What the full PW Consulting Thymidine Market report delivers
The full study is engineered to convert market intelligence into executable actions. Highlights include:
- Detailed market sizing (2020–2032) with scenario-based forecasts and sensitivity analysis to price and launch timing.
- Supply-chain maps showing manufacturing routes, input dependencies and logistical choke points.
- Supplier scorecards and audit-readiness assessments for the leading producers (technical, quality, capacity, commercial terms).
- Pricing model templates that allow buyers and sellers to stress-test margins under different raw-material and regulation scenarios.
- Go-to-market playbooks for entering premium GMP and low-cost bulk segments, including recommended qualification timelines and contract language.
- M&A and partnership heatmaps identifying attractive acquisition criteria and integration risks.
Note: This preview intentionally omits the granular breakdowns and proprietary segmentation tables (including regional and application-level share tables and raw numerical splits) that underpin our supplier rankings. Those analytics are part of the subscriber report and support tactical execution.
Risk matrix and watchlist for 2026
- Regulatory acceleration: New approvals for therapies related to thymidine metabolism can create abrupt demand spikes; monitor therapy rollouts and payer decisions closely.
- Supply bottlenecks: Concentration at the top of the supply chain creates outsized lead-time risk — buyers should expect intermittent spot-price surges.
- Quality and compliance: Rapidly on-shoring or pivoting of suppliers to meet demand for GMP-grade products can mask quality gaps; rigorous audit and analytics are non-negotiable.
- Geopolitical and trade risk: Cross-border flows of intermediates and precursor chemicals remain sensitive to export controls and tariffs; diversify geography where feasible.
How PW Consulting can support your 2026 planning
If your 2026 decisions depend on reliable thymidine supply, regulatory timing, or supplier selection, the full PW Consulting report provides the executable intelligence and templates to act. The preview above outlines our core conclusions: a modestly growing market, structural supply concentration, and a bifurcated commercial landscape that rewards clarity of strategy.
To access the full data tables, supplier scorecards, and a downloadable procurement playbook, visit our full report page. PW Consulting’s advisory teams are available to run a tailored workshop to convert the report’s insights into a 90-day operational plan aligned to your launch and procurement calendars.
For detailed analysis of this topic, please visit the official page: Thymidine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Wear Plate Market to Expand at 6.7% CAGR Through 2032 — PW Consulting
By pmarketresearch, 2026-07-30
Wear Plate Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present an executive-level primer on our new Wear Plate Market study. This briefing summarizes the strategic imperatives and tactical levers managers must understand heading into 2026, grounded in our proprietary analysis (base year 2025, historical window 2020–2025, forecast horizon 2026–2032). The full report contains the granular datasets, segmented scenarios, and supplier scorecards that procurement, product, and corporate development teams will need to operationalize these insights.
Wear Plate Market
Why this study matters for 2026
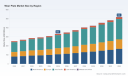
The wear plate sector sits at the nexus of heavy industry durability economics and emerging regulatory pressure. Our modelling shows the global market expanding steadily from the low‑hundreds of millions in 2020 to an expected USD 333 million in 2025, and continuing on a compound annual growth pathway of 6.7% through our forecast window. By 2032 the market approaches roughly USD 519 million. That trajectory signals more than healthy demand — it points to persistent opportunity for innovation in materials, extended-life solutions, and supply-chain reconfiguration.
Wear Plate Market
For leadership teams planning 2026 CapEx, product roadmaps, or M&A activities, the core strategic question is not whether the market is growing, but where value will accrue: to vertically integrated producers who can lower total cost of ownership (TCO), to specialty suppliers who differentiate on service and engineering, or to new entrants exploiting modular hardfacing and hybrid material systems. This study is engineered to help you prioritize those bets with quantitative rigor and pragmatic pathways to capture share.
Wear Plate Market
Macro trajectory and what it signals
-
Momentum and resilience: Historical analysis (2020–2025) shows consistent expansion despite cyclical pressures in mining and construction equipment markets. That resilience reflects both replacement demand and the economics of lifecycle optimization — customers increasingly pay up front for wear solutions that reduce downtime and maintenance cost.
-
Mid‑term opportunity set (2026–2032): Our base forecast translates the market’s 6.7% CAGR into practical timelines for new product introductions, capacity investments, and aftermarket partnerships. Suppliers with a near‑term capability to demonstrate measurable service‑life improvements will disproportionately capture aftermarket spend.
-
Market concentration: The sector remains moderately fragmented; top producers do not dominate to the extent seen in other heavy‑industrial inputs. Measured concentration metrics (CR3 and CR5) indicate space for consolidation, regional champions, and focused differentiators rather than winner‑take‑all dynamics.
What the report delivers — an operational playbook
This study is intentionally practical. Beyond forecasting, it contains the templates, analyses, and decision tools that procurement, engineering, and strategy teams can deploy immediately. Key deliverables include:
-
Scenario‑based forecasts (base case, upside, and downside) calibrated to commodity cycles and capital investment trends — enabling stress‑testing of budgets and production plans.
-
Supplier benchmarking and scorecards that combine technical capability, hardfacing expertise, service footprint, supply‑chain resilience, and commercial terms — designed for rapid RFP shortlisting.
-
Total cost of ownership (TCO) models with sensitivity levers for wear life, downtime cost, and retrofit cycle time — usable as negotiation tools with OEMs and third‑party fabricators.
-
Go‑to‑market playbooks for material substitution (e.g., steel overlays, ceramic inserts, polymer composites) and hybrid assemblies, including validation protocols and field test KPIs.
-
Regulatory impact matrix and compliance pathways — mapping how emerging mechanisms will affect imported overlay components, material sourcing, and carbon accounting across supplier tiers.
-
Deal architecture templates for joint development, licensing of hardfacing recipes, and carve‑out acquisition structures focused on capability capture rather than headline revenue.
-
Technical appendix with abrasion testing standards, weld overlay specifications, and retrofit engineering checklists to reduce adoption friction.
Competitive landscape — capability clusters and strategic moves
The report profiles established and specialist players, highlighting where competitive advantages are built and where disruption is most likely. A few illustrative company profiles and strategic takeaways:
-
Wear Plate USA (North Carolina, United States): A custom‑engineering leader in abrasion‑resistant parts, particularly for crushers and conveyors. Their strength lies in field‑proven design integration and aftermarket responsiveness — a playbook for firms that want to monetize application engineering rather than compete purely on price.
-
ASGCO Manufacturing (Allentown, Pennsylvania, United States): Notable for Chromium Carbide Overlay (CCO) and ceramic plate systems tailored to conveyor chutes and heavy wear points. Companies that bundle materials expertise with installation services are improving retention and margin capture.
-
JADCO Manufacturing (Harmony, Pennsylvania, United States): A recent product push in early 2025 introduced thinner CCO plates with tighter hardfacing bead control — a tactical innovation aimed at balancing weight, cost, and wear life for high‑throughput equipment. That launch illustrates how incremental product refinement can unlock price‑insensitive value in OEM replacement cycles.
-
Halden and Tianjin Leigong (China): These suppliers emphasize abrasion‑resistant steel and hardfacing consumables at scale. Their advantage is manufacturing breadth and cost competitiveness; strategic buyers will evaluate them against lead‑time, quality sustainability, and carbon footprint commitments.
-
Metco Joining & Cladding (Westbury, New York, United States): Specializes in welding overlays and hardfacing alloys – a reminder that specialized metallurgical know‑how remains a scarce capability with outsized commercial leverage for tailored applications.
Across these players, common themes emerge: engineering depth, service footprint, and the ability to prove life‑cycle economics are becoming as important as unit pricing. The study includes a supplier‑type matrix to help you match procurement needs to supplier archetypes.
Regulatory and supply‑chain inflection points
Two non‑market forces deserve explicit attention for 2026 planning:
-
Carbon pricing and trade measures: The EU’s Carbon Border Adjustment Mechanism (CBAM) is set to take effect in 2026 and will impose implicit carbon costs on imported goods. For wear plate buyers and manufacturers, this raises questions about the landed cost of imported overlay materials, near‑sourcing strategies, and supplier carbon disclosure. The report provides a compliance playbook that quantifies potential pass‑throughs and identifies low‑cost mitigation steps over a three‑year horizon.
-
Supply resilience and material inputs: Hardfacing wires, alloying elements, and ceramic feedstock availability influence lead times and margins. Our supplier risk heatmap helps companies prioritize inventory policy, dual‑sourcing, and technical substitution plans that preserve operational continuity without compromising performance.
How to use this intelligence in 2026 decisions
The study is structured to be actionable across three decision horizons:
-
Immediate (0–12 months): Use the TCO models and supplier scorecards to renegotiate master supply agreements, pilot high‑life wear systems on critical assets, and establish carbon reporting baselines for major imported inputs.
-
Near term (12–24 months): Validate material substitution pilots at scale, embed wear‑life KPIs into service contracts, and consider bolt‑on acquisitions that fill capability gaps (e.g., cladding expertise or regional fabrication centers).
-
Strategic (24–48 months): Pursue integrated service models combining supply, fitment, and predictive maintenance; evaluate regional capacity shifts driven by regulatory regimes; and consider platform plays that aggregate aftermarket demand across end‑use verticals.
What we intentionally withhold (and why)
To preserve the tactical edge for our clients and to follow the “preview” principle, this briefing demonstrates the analytical depth of the study but does not disclose the granular segmentation datasets (detailed regional splits, application shares, or material breakdowns). Those core micro‑datasets—essential for targeted procurement decisions, localized investment cases, and specific M&A screening—are included in the full report along with downloadable models. If your 2026 plan requires more than directional guidance, the full dataset is designed to plug directly into corporate planning tools.
Closing guidance — where to act first
-
Procurement leaders: Prioritize TCO renegotiations and establish two‑tier sourcing for critical inputs to hedge regulatory pass‑throughs.
-
Product and engineering teams: Accelerate field trials for hybrid overlay systems and quantify service‑life gains against retrofit costs.
-
Corporate development: Screen for small, capability‑rich targets in cladding and material science that can be integrated into service bundles.
-
Compliance and sustainability teams: Start scenario planning for CBAM implications and build supplier carbon visibility into contracts.
Our Wear Plate Market study is expressly built to convert market insight into 2026 action: validated forecasts, supplier playbooks, and technical validation protocols that reduce uncertainty and accelerate value capture. For decision‑makers preparing budgets, sourcing strategies, or M&A agendas for 2026, this research is the operational intelligence layer you can deploy immediately.
PW Consulting stands ready to workshop these findings with your cross‑functional team and to customize the datasets and models to your asset base, procurement profile, and regulatory footprint.
For detailed analysis of this topic, please visit the official page: Wear Plate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Diamond Saw Blades Market to reach USD 10,620 Million by 2032 at 2.41% CAGR
By pmarketresearch, 2026-07-30
Diamond Saw Blades Market — Strategic Briefing for 2026 Decisions
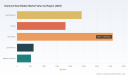
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a concise, high-impact preview of our comprehensive Diamond Saw Blades Market study. This briefing synthesizes the highest-value, decision-facing insights executives and investors need to act in 2026 — while reserving the detailed segment-level datasets and models for the full report. The market reached approximately USD 9,000 Million in our base year (2025) after a steady recovery from 2020, and our scenario-aligned baseline projects a compound annual growth rate (CAGR) of 2.41% through the 2026–2032 forecast window, reaching just over USD 10.6 billion by 2032. Use this briefing to frame investment priorities, procurement strategies, and go-to-market choices in the coming 12–18 months.
Diamond Saw Blades Market
Why this report matters in 2026
-
Actionable clarity amid modest growth: The market’s low-to-mid single-digit CAGR signals a mature category where incremental gains—product premiumization, channel optimization, and supply-chain resilience—drive disproportionate margin improvements.
Diamond Saw Blades Market -
Capital allocation and M&A timing: With limited top-tier concentration (CR3 ≈ 24.6% and CR5 ≈ 32.0%), there is room for consolidation playbooks that combine scale with niche technology acquisitions. Private equity and corporate strategists must balance scale economics against specialty margins.
Diamond Saw Blades Market -
Operational risk and supplier strategy: Raw material sourcing and regional manufacturing footprints are decisive: disruptions or regulatory shifts in synthetic diamond sourcing or facility closures can rapidly reshape cost curves and lead times.
-
Procurement & product decisions tied to regulation and automation trends: Buyers will increasingly prefer precision blades that reduce rework and energy use in automated cutting lines—presenting a premiumization pathway for leading vendors.
Macro and demand dynamics shaping 2026 tactics
-
Recovery then normalization: The market expanded from the lower levels recorded in 2020 to USD 9,000 Million in 2025, reflecting cyclical construction recovery, higher renovation activity, and selective industrial capex. From 2026 onward, expect steady but uneven growth driven by infrastructure programs and specialty industrial demand.
-
Precision and automation adoption: Labor shortages and energy-efficiency mandates are accelerating uptake of higher-grade, precision-engineered blades in masonry and concrete applications. Buyers reward longer life, lower dust generation, and compatibility with automated equipment.
-
Raw material concentration and trade sensitivity: Synthetic diamonds — the primary abrasive segment material — are commercially sourced from a limited set of countries. U.S. customs and regulatory developments (recent rulings identify key sourcing origins) heighten geopolitical and compliance risk for buyers and manufacturers alike.
-
Regulatory and safety factors: Practical standards and mounting protocols (e.g., mandatory secure mounting and torqueing guidelines) influence product design and aftermarket support needs. Compliance-driven product improvements create differentiation windows.
Competitive landscape — what the market structure implies for competitors
The competitive field is a mix of established industrial tool businesses, regional specialists, and digitally native direct-to-contractor suppliers. No single player dominates; rather, a top-five cohort captures roughly a third of market revenue, leaving meaningful market share for strong regional brands and OEM-suppliers. Below I summarize strategic positioning and implications for the named players we track.
-
Diamond Products Limited (Elyria, OH) — Known for premium wet/dry segmented, continuous rim, and turbo blades. Strength: deep application engineering for concrete and pavement. Strategic levers: expand service programs and retrofit offerings for rental fleets.
-
MK Diamond Products (Santa Fe Springs, CA) — Professional-grade blades and core bits with strong contractor channels. Strength: brand trust among masonry professionals. Strategic levers: scale consumables subscription for equipment rental and construction firms.
-
Husqvarna Construction Division (Stockholm) — Premium product breadth for concrete, asphalt, brick, and stone. Notably, Husqvarna has announced intent to exit non-core stone diamond tools by end-2026, implying potential asset carve-outs or contract manufacturing opportunities for competitors.
-
Bosch Power Tools (Gerlingen) — Strong distribution and aftermarket reach, supplying blades for circular saws and grinders. Strength: channel and cross-selling with power tools. Strategic levers: bundle blades with tool warranties and digital measuring systems.
-
Norton Abrasives / Saint-Gobain (Worcester, MA) — Industrial-grade blades and abrasives with emphasis on performance testing and safety guidelines. Strength: industrial OEM credibility. Strategic levers: certified performance programs for large construction and shipbuilding contractors.
-
Regional and specialty players — Companies such as Diamond Blade Warehouse, Patriot Diamond Blades, Random Products Inc., Vortex Diamond, Devour Tools, and Viraj Abrasives provide differentiated value via localized manufacturing, cost-competitive supply, or high-precision/laboratory-tested offerings. Strategic levers for these firms include vertical integration into core bits, laser-welded segment technologies, and targeted export strategies.
Recent market signals & implications
-
Trade show activity (late 2025–early 2026): Several manufacturers are highlighting new product ranges and market-facing demos at European and global expos—indicating renewed focus on product differentiation and direct customer engagement.
-
Product launches and educational content: Vendors are releasing tiler-focused catalogs and step-by-step cutting tutorials, signaling a push to educate end-users and reduce price elasticity through perceived value.
-
Firm-level strategic shifts: Husqvarna’s announced withdrawals create near-term supply and aftermarket service discontinuities in specific geographies, opening acquisition targets and contract manufacturing bids for competitors seeking scale.
Strategic playbook — five priority actions for 2026
-
Supply chain resilience and dual-sourcing: Map synthetic diamond supply and secure secondary sources across jurisdictions. Consider inventory-indexed procurement contracts to hedge against regional disruptions and customs rulings.
-
Premiumization tied to automation: Invest in R&D for low-dust, long-life bonds and laser-welded segment technology; align go-to-market with OEMs of automated cutting lines to create bundled value propositions.
-
Aftermarket and service-driven margins: Build certified reconditioning programs, parts-as-a-service, and training bundles that lock customers into longer lifecycle relationships and recurring revenue.
-
M&A and asset-light plays: Evaluate tuck-ins—especially in geographies impacted by manufacturing shutdowns—and opportunistic acquisitions of Husqvarna’s non-core assets where permissible. Also consider contract manufacturing partnerships to capture displaced demand quickly.
-
Digital enablement and channel optimization: Accelerate e-commerce channels for small contractors, introduce predictive replacement algorithms in mobile apps, and create SKU rationalization to reduce inventory cost while improving fill rates.
What the full PW Consulting report contains (select highlights)
-
Comprehensive market sizing and forecast model (2020–2032) with scenario sensitivity and price-volume breakdowns for strategic planning.
-
Segment and application demand analysis (type, application, and region) with demand-driver overlays and elasticities—note: core segment-level datasets and percentage splits are available in the full report only.
-
Supplier and value-chain map that identifies single-source exposures, manufacturing footprints, and transportation chokepoints.
-
Company profiles and capability heatmaps for leading and emerging suppliers, including strategic SWOTs and inorganic opportunity matrices.
-
Commercial playbooks: procurement negotiation scripts, go-to-market bundles, aftermarket pricing strategies, and a prioritized two-year implementation roadmap.
-
Regulation & compliance tracker tying customs rulings, safety standards, and country-level manufacturing changes to operational impacts and cost modeling.
-
Interactive dashboards and downloadable models to run “what-if” scenarios on commodity price shocks, equipment automation penetration, and regional demand swings.
Final practical guidance for 2026
For executives allocating capital in 2026, the priority is clear: focus on selectively captured premium pockets, shore up raw-material sourcing, and position for consolidation opportunities arising from strategic exits and facility closures. The overall market’s modest growth profile rewards disciplined, operationally led expansion rather than broad-basin investment. Procurement teams should convert supplier relationships into risk-sharing agreements, while product teams must accelerate innovations that link blade performance to automated and energy-constrained production lines.
PW Consulting’s full report delivers the granular segment analyses, regional datasets, supplier-level figures, and executable templates that underpin these strategic conclusions. If you are planning capital projects, sourcing transformation, product launches, or M&A activity in 2026, the full dataset and scenario tools will materially sharpen your risk-adjusted choices.
Contact PW Consulting to access the full Diamond Saw Blades Market report and the accompanying interactive models. Our analysts are available to run tailored briefings and scenario workshops for your executive team.
For detailed analysis of this topic, please visit the official page: Diamond Saw Blades Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Latex Powder Market — Strategic Preview for 2026 Decision-Makers
As companies prepare their 2026 investment and commercial plans, a clear, actionable understanding of the Latex Powder market is no longer optional — it is strategic. PW Consulting’s forthcoming Latex Powder Market study synthesizes five years of market history with a seven-year forecast to deliver the kind of decision-grade intelligence that procurement, R&D, corporate development, and commercial teams need to move from hypothesis to high-confidence action.
Latex Powder Market
Market snapshot: scale, trajectory, and concentration
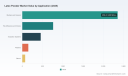
Our analysis places the global Latex Powder market at approximately USD 3.8 billion in the base year (2025), having expanded steadily from the early-2020s. Under the central scenario, the market is projected to grow at a compound annual growth rate (CAGR) of 5.9% over the forecast window (2026–2032), reaching just over USD 5.6 billion by 2032. This is a mid-single-digit growth posture that reflects a combination of sustained industrial demand, product migration across adhesive and building-material formulations, and pockets of higher growth driven by specialty natural-latex applications.
Latex Powder Market
Market concentration is meaningful but not monopolistic: the top three players account for just over half of industry revenue, while the top five capture slightly under six in ten dollars of market sales (CR3 ≈ 52%, CR5 ≈ 58%). This structure creates room for both scale players to defend margin via integration and for fast-follow innovators to capture niche opportunities through product differentiation and channel focus.
Latex Powder Market
Why this report matters for 2026 planning
- Timing: With 2026 budgets and contracts being finalized now, the study provides timely scenario-tested inputs for capex allocation, commercial targets, and supply-security investments.
- Actionability: We map macro forecasts to concrete levers — supplier sourcing strategies, formulation migration roadmaps, and channel-level go-to-market plays — so teams can translate forecasts into quantified project plans.
- Risk-adjusted planning: By combining regulatory, environmental, and raw-material risk overlays with price and volume scenarios, the report enables risk-weighted decisions for procurement, M&A, and product launches.
Key market dynamics you’ll find unpacked
- End-market pull vs. synthetic-substitute pressure: Building-materials and tile-adhesive demand continues to underpin volume growth, even as formulators explore lower-cost synthetics and hybrid polymer systems. How and where latex retains technical or sustainability advantages is critical for portfolio prioritization.
- Supply-chain concentration and raw-material risk: Certain botanical and specialty natural latex streams command premium positioning but carry provenance and conservation exposure. Strategic sourcing and traceability programs are now non-negotiable for companies trading in these inputs.
- Regulatory overlays shaping commercialization: Recent authoritative inclusions and monographs for some botanical latex inputs have improved market legitimacy for dietary and personal-care applications — but they also bring new compliance burdens, labeling obligations, and import/export controls that affect route-to-market and cost-to-serve.
- Margin polarisation: Producers with integrated upstream access or differentiated specialty grades are widening margin gaps versus commodity suppliers. The implications for pricing strategy and M&A targeting are spelled out in our competitive playbook.
Regulatory and raw-material alerts that will matter in 2026
Two regulatory developments deserve immediate attention from both commercial and compliance teams. First, certain botanical latex sources have been incorporated into official pharmacopeial monographs and national botanical compendia, which accelerates their acceptance in regulated applications but also locks in documentation, testing, and quality specifications. Second, selected bitter-aloe species used for latex extraction are subject to international trade controls under conservation agreements. These controls impose additional traceability, permitting, and shipment constraints that can lengthen lead times and increase transaction costs.
From a supplier perspective, manufacturers of botanical latex derivatives (including specialized producers of Cape Aloe-derived products) have operational profiles that blend agricultural sourcing, processing, and regulatory documentation. For buyers and formulators, this translates into procurement practices that must integrate agricultural-season risk, compliance audits, and chain-of-custody verification as standard operating procedures.
Competitive landscape — what to watch
The sector is a mixed competitive field: established chemical and polymer companies dominate industrial commodity grades, while specialty ingredient firms hold positions in botanical and niche natural-latex applications. Market leaders benefit from scale in production, broad distribution networks, and the ability to absorb raw-material price variation. Mid-sized and specialist firms are winning on formulation agility, customer intimacy, and targeted technical service.
MartinBauer provides a clear example of the specialist profile: headquartered in Germany, the company manufactures botanical latex powders from Cape Aloe (Aloe ferox) for use across food, beverage, and dietary supplement applications. Their business model underscores several strategic themes we examine in the report — the premium pricing of certified natural-latex ingredients, the integration of raw-material sourcing with regulatory documentation, and the channel-specific go-to-market approach required to commercialize botanically derived latex powders into regulated categories.
Segmentation and product architecture (what we reveal — and what we don’t)
The full study breaks the market down by polymer families, end-use applications, and regions, and provides a granular view of historical sales volumes, 2026 inflection points, and seven-year forecasts. In this preview we deliberately hold back the segment-level revenue tables and regional share maps to encourage direct engagement with the full dataset; the downloadable report contains the complete segment-by-segment revenue, CAGR by subsegment, and SKU-level pricing histories.
What you should know now: product differentiation is increasingly multi-dimensional — combining polymer chemistry (synthetic vs. hybrid vs. botanical), performance attributes (adhesion, open time, flexibility), and sustainability credentials (bio-content, certification). Application categories such as construction adhesives, tile adhesives and grouts, insulation systems, mortars, and specialty plasters show divergent growth patterns and margin characteristics that require distinct commercial plays.
Report contents — a practical, execution-focused breakdown
- Executive summary with scenario-tested financials and priority actions for 2026
- Full historical dataset (2020–2025) and seven-year forecast (2026–2032) with sensitivity analyses
- Segment-level revenue and CAGR tables (polymer types, applications, regions) — interactive workbook included
- Pricing intelligence and raw-material cost pass-through models
- Supply-chain heat maps, lead-time risk scoring, and traceability checklists
- Regulatory tracker focused on pharmacopoeial listings, national monographs, and conservation-related trade controls
- Detailed company profiles and competitive matrices, including strategic options and likely M&A targets
- Playbooks: procurement (supplier segmentation), commercial (value-based pricing and channel design), R&D (formulation roadmaps), and corporate development (target screening criteria)
2026 strategic playbook — five actions with high ROI
- Prioritise supply-chain resilience for botanical and specialty inputs: implement multi-sourcing, conditional forward-buying, and minimal viable traceability standards to reduce shipment and regulatory disruption risk.
- Segment the portfolio for differential investment: defend high-margin, performance-critical grades with capex and technical service, while automating and cost-optimising commodity lines.
- Invest in compliance-as-a-competitive-advantage: proactively align specifications with recognized pharmacopeial and national monographs and establish document-ready supply chains to win regulated customers faster.
- Design go-to-market plays by channel and application: industrial construction channels will reward reliability and scale; specialty botanical channels demand provenance, certification, and targeted marketing.
- Pursue targeted M&A and partnership plays: look for bolt-ons that deliver traceability, unique botanical feedstocks, or formulation IP that accelerates entry into regulated natural-latex use cases.
How to use the full report in your 2026 planning cycle
Procurement: fold our risk-scored supplier matrices and cost-pass-through models into your 2026 sourcing agreements and hedging strategy.
Commercial: align pricing and rebate structures with segment-level elasticity and margin maps to protect profitability as volumes expand.
R&D and product management: use our formulation roadmaps to prioritise projects that maximize margin uplift and shorten time-to-market, especially for regulated botanical use cases.
Corporate development: apply our screening criteria and target fits to identify transactions that deliver both top-line acceleration and strategic capability (e.g., traceability systems, botanical feedstocks, or application-specific formulations).
Next steps — get the complete intelligence
This briefing is designed to accelerate your 2026 decisions by highlighting the strategic implications of macro growth, competitive structure, and regulatory risk. For the full, interactive dataset — including the withheld segment-level revenues, regional breakdowns, SKU-level pricing histories, and the complete competitive intelligence matrices — access the full PW Consulting Latex Powder Market report and downloadable workbooks on our site.
In markets where a few percentage points of forecast accuracy or a single validated supplier relationship can change the outcome of a year’s P&L, the difference between informed action and reactive strategy is the difference between leading and lagging. Our report provides the former; use it to set the pace for 2026.
For detailed analysis of this topic, please visit the official page: Latex Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Nafion Market Reaches USD 1,020M in 2025; 5.4% CAGR (2026–2032)
By pmarketresearch, 2026-07-30
Nafion Market 2026: Strategic Preview for Executive Decision-Making
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present an oriented preview of our latest Nafion Market study — designed to equip executives, portfolio managers, and technology leads to make high-conviction decisions in 2026. This brief surfaces the strategic implications from our proprietary market model, competitive mapping, and risk framework while preserving the detailed segmentation and granular scenario outputs for subscribers of the full report.
Nafion Market
Market at a Glance — Macro Trajectory
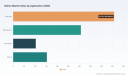
Using 2025 as the base year, our model traces Nafion’s recovery and acceleration across the 2020–2025 historical window and projects performance through a 2026–2032 forecast horizon. The market expanded from roughly USD 784 million in 2020 to about USD 1,020 million in 2025, reflecting a multi-year inflection around clean-energy demand drivers. Under our central forecast, the market advances at a compound annual growth rate (CAGR) of 5.4% through 2032, reaching an estimated USD 1,474 million by 2032.
Nafion Market
For strategy teams, these headline numbers matter for three reasons: (1) they quantify the opportunity size for core Nafion product lines in membrane-based electrochemistry; (2) they delimit planning horizons for capacity and R&D investments; and (3) they provide the basis for capital allocation and M&A screening across related polymer and electrochemical value chains.
Nafion Market
Why This Study Matters for 2026 Decisions
- Capital Allocation and Timing: With predictable mid-single-digit CAGR growth, boards must reconcile steady demand expansion with meaningful lead times for membrane manufacturing and supply-chain reconfiguration. Our report models multiple capex timing scenarios and the sensitivity of IRR to product mix and input-cost shocks.
- Commercial Positioning: Nafion’s role in fuel cells, electrolyzers, and specialty industrial chemistry creates divergent commercialization pathways. We map go-to-market choices (direct, distributor partnerships, licensing) to customer archetypes and procurement cycles.
- Supply-Chain Resilience: Raw material and energy cost volatility is a recurring theme. The study provides procurement playbooks, hedging alternatives, and supplier-risk heatmaps that translate market-level volatility into actionable mitigation steps.
- Regulatory and Project Pipeline Alignment: Policies such as the EU Hydrogen Strategy materially affect demand scheduling for Nafion-based membranes. Our workbench links announced hydrogen infrastructure projects and policy levers to short- and medium-term demand pulses.
Report Contents — Practical Modules Included
The full research pack is structured for both strategists and operators. Highlights include:
- Executive summary with investment-grade market sizing and high-confidence scenarios for 2026–2032.
- Demand model by application group and product form factor (membrane, dispersion, resin) with elasticity assumptions and scenario toggles.
- Supply-side map: incumbent capacities, brownfield expansion projects, and a proprietary capacity utilization tracker that flags near-term bottlenecks.
- Price-supply sensitivity analysis and an interactive cost-of-goods model incorporating raw-material feeds and energy.
- Competitive landscape, market concentration metrics, and a curated list of strategic M&A targets and partnership candidates.
- Commercial playbooks tailored for OEMs, material suppliers, and system integrators — including channel strategy and contract-design templates.
- Regulatory and policy tracker linking major initiatives (e.g., hydrogen hubs) to regional procurement and standards timelines.
- Risk matrix and contingency playbook addressing supply shocks, regulatory shifts, and disruptive substitutes.
Note: To preserve the utility of this preview, detailed regional and application-level splits are reserved for the full report. That granular intelligence is essential for transactional due diligence, bid preparation, and localized capacity planning.
Competitive Landscape — Who Moves Markets
The Nafion ecosystem is concentrated: our market concentration metrics indicate that the top three suppliers control a material majority of market volumes, with the top five pushing that concentration higher. This structure creates both stability and strategic friction — stability in baseline supply, friction in capacity flexibility and price setting.
- The Chemours Company (Wilmington, Delaware) — Originator and principal producer of Nafion™ perfluorosulfonic acid polymer materials, including membranes, dispersions, and resins. Chemours’ recent financial disclosure for full-year 2025 highlights continued revenue contribution from its advanced polymer segment. The company remains the bellwether for pricing and technical roadmaps in the Nafion universe. ( https://www.nafion.com)
- Ion Power, Inc. (New Castle, Delaware) — Authorized distributor and value-added manufacturer focused on electrochemical applications. Ion Power acts as a critical bridge between primary polymer producers and fuel cell/electrolyzer OEMs, offering conversion capabilities and application-specific services. ( https://ion-power.com)
- Perma Pure LLC (Florida) — Specialist in Nafion® tubing and gas-conditioning components. Perma Pure’s product set highlights the importance of downstream component integration and niche system-level value capture. ( https://www.permapure.com)
- Beantown Chemical (Hudson, New Hampshire) — Supplier of research chemicals, materials, and membranes, serving labs and early-stage developers. Their role underscores the innovation corridor where small-volume, high-value applications incubate. ( https://www.beantownchem.com)
Recent corporate developments are also shaping strategy in 2026. Chemours led a technical working group publishing an industry study on refrigerant emissions in Europe, an initiative that signals the firm’s willingness to lead cross-industry technical convenings. More importantly, Chemours’ 2023 investment to expand Nafion production capacity in France — a multi-hundred-million-dollar program — remains a structural supply-side event that firms must account for when modeling medium-term availability and pricing.
Market Dynamics: Forces to Watch
- Raw material and energy volatility: Feedstock price swings and energy-cost dynamics create direct pressure on membrane economics. We model scenarios where input-cost shocks compress margins or, alternately, catalyze supplier consolidation.
- Policy acceleration for hydrogen: Policy pushes (notably in Europe) are translating into project pipelines that require Nafion-based membranes for both electrolyzers and fuel cells. Our project-tracker translates policy timelines into likely demand windows.
- Production scale vs. product mix: The market requires both large-area membranes and specialty dispersions/resins. Firms must decide whether to prioritize scale or product breadth. Our operational scenarios quantify the breakevens and lead times for each choice.
- Pricing sensitivity: Published benchmarks indicate commercial Nafion membrane prices in the order of magnitude of approximately USD 1,400 per square meter in certain contexts — a figure that highlights cost sensitivity for system integrators and explains ongoing attention to alternative membrane chemistries and commoditization risk.
Strategic Playbook for 2026
Executives should treat the Nafion opportunity as a program requiring concurrent actions across five vectors:
- Secure upstream feedstock and hedging arrangements: Negotiate multi-year supply or tolling contracts and identify secondary suppliers to mitigate single-source risk.
- Optimize product portfolio: Use value-attribution models to prioritize membrane formats and dispersion/resin formulations that deliver the highest margin-accretive exposure to hydrogen and fuel-cell demand.
- Invest selectively in capacity and conversion: Balance greenfield expansion with tolling, contract manufacturing, and strategic joint ventures. Our economic cases show that timing and location of capacity matter as much as nominal capacity size.
- Pursue strategic partnerships and licensing: For OEMs and component makers, licensing agreements or distribution partnerships with incumbents can accelerate market entry while avoiding heavy capex.
- Prepare for regulatory-driven procurement pulses: Align sales and delivery capabilities to expected public-hub and OEM procurement timelines; bid-readiness confers outsized advantage for project awards.
How PW Consulting Translates Insight into Action
Subscribers to the full Nafion Market study receive not only the proprietary datasets and forecast model but also a tailored decision-support toolkit: scenario-based investment memos, a supplier due-diligence checklist, and a short-list of inorganic targets calibrated on technical fit and market reach. For corporate development teams, we overlay financial stress-testing to quantify downside exposure; for product teams, we provide roadmap recommendations linked to anticipated system-level requirements through 2032.
Conclusion — Why Access the Full Report
This preview synthesizes the strategic contours of the Nafion market through 2032: steady mid-single-digit growth, concentrated supply, policy-driven demand catalysts, and material sensitivity to input-cost dynamics. The full report supplies the granular segmentation, regional demand matrices, price curves, and project-level pipelines that operational leaders need to convert strategy into executable plans. In a market where timing, partner selection, and supply resilience determine winners, the right intelligence shortens the path from strategy to profitable execution.
For teams preparing capital plans or commercial strategies in 2026, our research functions as both a market map and an execution playbook. Contact PW Consulting to access the complete dataset, interactive model, and tailored advisory engagement opportunities.
For detailed analysis of this topic, please visit the official page: Nafion Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Steel Piston Market to hit USD 1,114M by 2032 at 4.2% CAGR
By pmarketresearch, 2026-07-30
Automotive Steel Piston Market — Strategic Outlook for 2026 Decision-Makers
Executive summary
As global powertrain strategies diversify through 2026 and beyond, steel pistons retain a critical strategic role across commercial and high-performance internal combustion platforms. Our PW Consulting Automotive Steel Piston Market study (base year 2025; forecast period 2026–2032) synthesizes five years of historical performance with a robust forward view driven by material- and system-level dynamics. The market has shown steady expansion in the early 2020s and, under present assumptions, will continue to grow at an aggregate CAGR of 4.2% through the forecast window. This trajectory underpins near-term investment decisions for OEMs, tier‑1 suppliers, and private equity players positioning for durability- and performance-led segments of the mobility ecosystem.
Automotive Steel Piston Market
Why this study matters for 2026 strategic planning
-
Material decisions now determine multi-year product roadmaps. Steel piston technologies — from friction‑welded monoblocs to laser-welded, multilayer designs — are increasingly chosen to meet peak cylinder pressures, extended service lives, and targeted CO2 reductions in heavy-duty and specialist passenger applications.
Automotive Steel Piston Market -
Capital allocation needs clarity on market scale and momentum. Our base-year 2025 sizing and the 2026–2032 forecast provide executives with the macro envelope necessary to size R&D spends, capacity builds, and M&A targets without relying on piecemeal supplier anecdotes.
Automotive Steel Piston Market -
Regulatory and lifecycle pressures make material-level optimization a P&L lever. Proven steel-piston architectures today contribute to emission and efficiency gains that have measurable implications for compliance timelines and residual value assumptions.
Market dynamics: what is driving demand
The steel piston market is being shaped by several converging forces that are highly relevant for 2026 decisions:
-
Performance thresholds in heavy-duty diesel platforms. Engineering requirements for peak ignition pressures — in certain applications approaching 300 bar — and the need for longevity under extreme duty cycles keep steel in active consideration where lightweight aluminum cannot deliver the required robustness.
-
Technical differentiation through joining and surface technologies. Friction‑welded, laser‑welded and other advanced manufacturing approaches enable lower compression heights, improved thermal management and reduced friction losses — all factors that translate into fuel efficiency and CO2 advantages at the system level.
-
Operational life and total cost of ownership. Field data and manufacturer claims indicate steel piston systems can deliver exceptionally long service lives — in some commercial platforms exceeding one million kilometers — reducing downtime, rebuild costs and lifecycle emissions when compared to frequent replacement cycles.
-
Material-technology synergy for emissions compliance. Optimized steel piston solutions contribute to CO2 reduction potential through improved friction and thermal behaviours and can be an integral component of broader combustion optimization packages.
Competitive landscape — strategic implications
The competitive field blends long-established automotive suppliers with regionally focused specialists. Market share concentration is low‑to‑moderate (CR3 approximately 35%; CR5 approximately 38%), highlighting a market that is neither fully commoditized nor tightly consolidated — a pattern that favors both organic differentiation and targeted consolidation plays.
Key players and strategic postures observed in the market include:
-
Mahle GmbH (Stuttgart, Germany) — Offers multiple steel piston concepts spanning passenger and commercial vehicles, with solutions tailored for extreme peak pressures and advanced cooling strategies. Mahle’s emphasis on laser‑welded architectures highlights the importance of minimizing compression height while optimizing thermal paths for reduced frictional losses.
-
KS Kolbenschmidt Pistons (KSPG AG / Rheinmetall Automotive) — Positions steel piston systems as enablers of CO2 reduction at the system level, with engineered add-ons that claim up to a 4% reduction in CO2 under specific conditions. Their approach underscores the need for suppliers to couple material expertise with subsystem calibration and emissions engineering.
-
Tenneco Inc. — Focuses on friction‑welded Monosteel® one‑piece pistons for large‑bore engines, demonstrating that manufacturing method and scale compatibility remain central to commercial viability in the heavy‑duty segment.
-
Aisin Seiki Co., Ltd. and Hitachi Astemo, Ltd. — Both maintain OEM-facing portfolios that integrate steel piston solutions into broader engine systems, signalling the persistence of integrated supply chains and the strategic value of platform-level partnerships.
-
Shriram Pistons & Rings Ltd. — Represents regionally specialized suppliers with forged steel capabilities focused on heavy-truck platforms, pointing to localization strategies for cost, service and market access.
Practical implications for different player types
Our analysis delivers differentiated recommendations depending on the stakeholder’s role:
-
OEMs — Treat steel piston selection as a systems engineering decision, not merely a bill‑of‑materials choice. Assess supplier roadmaps for joining technologies and cooling strategies alongside combustion calibration plans to realize measurable CO2 and TCO benefits.
-
Tier‑1 suppliers — Invest selectively in manufacturing capabilities (friction‑welding, laser welding, precision forging) where they create defensible margins and speed-to‑market. Consider modular product platforms that allow material substitution between steel and other alloys without disrupting downstream integration.
-
Private capital — Look for consolidation targets in the lower‑tier supply base where scale can be achieved through bolt‑on capacity and through the transfer of advanced joining technologies to higher‑margin applications.
-
Policy and procurement teams — Insist on validated field performance metrics (e.g., service life, friction loss, CO2 equivalence) rather than supplier assertions alone, and build contractual incentives that capture realized durability and efficiency benefits.
Report contents — what you will find in the full study
The PW Consulting Automotive Steel Piston Market report is designed as an operational playbook for 2026 decision cycles. Highlights include:
-
Comprehensive market sizing and trend analysis with historical performance (2020–2025) and a detailed forecast through 2032, presented with scenario sensitivity to fuel‑price, regulation and adoption assumptions.
-
Technology deep dives into manufacturing processes (friction‑welding, laser‑welding, forging), material selection rationale, and subsystem impacts on friction, cooling and combustion efficiency.
-
Competitive profiles and benchmarked capabilities of the major established suppliers, focused on product architecture, manufacturing footprint, and partnerships — enabling shortlisting for supplier dialogues or M&A screening.
-
Strategic playbooks for OEMs and suppliers covering go‑to‑market, capacity strategies, and R&D prioritization, with implementation checklists and investment decision matrices.
-
Risk and sensitivity matrices that quantify the upside and downside to market size across regulatory scenarios and powertrain transition paths.
2026 action guide — three near-term moves
-
Prioritize platform‑level testing — Validate steel‑piston options within representative engine architectures under real duty cycles to quantify frictional and thermal benefits and to convert supplier claims into contractual KPIs.
-
Lock in manufacturing optionality — Where lead times and capital intensity permit, create dual-sourcing corridors and invest in flexible joining technologies to move quickly between aluminum and steel options as regulation or duty requirements evolve.
-
Seek targeted consolidation — For investors and strategic buyers, focus on acquiring specialists with proprietary joining tech or onshore capabilities that shorten supply chains for critical commercial‑vehicle platforms.
Preview vs. full intelligence
This article is intentionally crafted as a strategic preview: it surfaces the market’s macro trajectory, competitive themes, and tactical priorities to help inform 2026 planning. To preserve the value of detailed, transaction‑ready intelligence, we have withheld granular segment breakdowns and the full set of regional and application‑level financial details that underpin our recommendations. Those granular tables, supplier‑level cost curves, and scenario worksheets are available in the complete PW Consulting report.
Closing — how PW Consulting can support your 2026 roadmap
Decisions made in 2026 about material choices, manufacturing footprints, and supplier relationships will determine competitiveness for years. Our Automotive Steel Piston Market study provides the quantitative baseline and the operational playbooks required to translate material science and manufacturing advances into measurable business outcomes. For executives preparing investment memoranda, RFPs, or integration plans, PW Consulting offers tailored briefings, model walkthroughs, and supplier diligence services to accelerate decision velocity while reducing execution risk.
Request the full report and proprietary appendices for access to the detailed segmentation, regional economics, supplier cost models and scenario analyses that underpin the findings summarized here.
For detailed analysis of this topic, please visit the official page: Automotive Steel Piston Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Metalworking Fluids Market set to hit USD 164.51 Million by 2032; 4.8% CAGR
By pmarketresearch, 2026-07-30
Metalworking Fluids Market: Strategic Preview for 2026 Decision-Makers
As manufacturers, chemical suppliers, and private-equity investors prepare their 2026 playbooks, the metalworking fluids (MWF) market demands attention. Our latest PW Consulting research frames this market as a steady-growth industrial staple undergoing rapid technical, regulatory, and supply-chain disruption. Between 2020 and 2025 the market expanded from a modest base to reach an aggregate value in the low triple-digits (USD Million scale), and our forward view projects a compound annual growth rate (CAGR) of 4.8% across the 2026–2032 forecast window—taking total market value materially higher by 2032. This is not a market for passive observation; it is an operational battleground where formulation science, regulatory agility, and supply-chain resilience will determine winners.
Metal Working Fluids (Metalworking Fluids) Market
Why this research matters for 2026 decisions
-
Timing matters: 2026 is the inflection point when regulatory, raw-material, and product-innovation pressures converge. Firms that act early to de-risk supply and re-orient portfolios toward the regulatory and sustainability vectors will secure durable margins.
Metal Working Fluids (Metalworking Fluids) Market -
Operational roadmaps outperform marketing promises: in a market growing at near-single-digit CAGR with persistent cost shocks, tangible improvements in tool life, sump life, and total cost of ownership (TCO) tip procurement decisions faster than branding alone.
Metal Working Fluids (Metalworking Fluids) Market -
Consolidation levers are available—but selective. Market concentration is moderate (the top three and top five players capture a meaningful share without monopolizing the value chain), creating opportunity for scale-seeking M&A as well as specialty plays around bio-based and high-performance synthetic niches.
Macro dynamics shaping 2026 strategies
Three structural forces will dominate market dynamics in 2026:
-
Regulatory acceleration: Local and supranational rulemaking is tightening controls on VOCs, formaldehyde, chlorinated paraffins, and PFAS-related risks. Examples include strengthened VOC limits in jurisdictions with aggressive air-quality programs and ongoing EU scrutiny on legacy additives. These changes increase reformulation costs and create technical barriers to entry for incumbents and newcomers alike.
-
Raw-material volatility: Industry intelligence points to a worsening base-oil supply environment in 2026. That shock amplifies input-cost risk for mineral-based formulations and shifts commercial incentive toward synthetics, bio-based blends, or higher-margin additive packages that enable price recovery.
-
Performance and service convergence: Customers increasingly demand integrated solutions—fluids plus lifecycle services such as testing, recycling, and fluid management—because operational uptime and environmental compliance are equally critical to their procurement decisions.
Competitive landscape — who’s doing what
The sector blends global integrated oil majors, specialty lubricants firms, and regional formulators. Our report spotlights strategic positioning across the value chain:
-
Major oil & chemical incumbents (e.g., Castrol, ExxonMobil, TotalEnergies): leveraging scale, R&D labs, and global distribution to push “eco-friendly” reformulations and broaden industrial channels. Recent product introductions emphasize compliance-forward chemistries and improved lifecycle performance—clear signals that portfolio transition is corporate strategy, not mere marketing.
-
Specialists and formulators (e.g., FUCHS, Houghton, Quaker, Blaser Swisslube): competing on technical differentiation—precision machining, extended sump life, and bespoke additive systems. These players are the primary beneficiaries of OEM co-development relationships for aerospace and high-performance automotive machining.
-
Additive and base oil suppliers (e.g., Chevron Phillips Chemical, Lubrizol, Clariant): tightening control over upstream inputs gives these firms leverage to influence formulation costs and speed-to-market for new chemistries.
-
Regional and niche producers (e.g., APAR, Tower, Master Fluid Solutions, Halocarbon): running rapid product-cycle programs to capture specialty pockets—especially where localized regulatory or performance requirements reward agility.
Recent product activity underscores the strategic shifts: major launches in 2025 and late 2025–2026 ranged from eco-focused fluid lines to neo-synthetic and bio-compatible formulations tailored for aerospace, defense, medical devices, and high-performance machining. These releases indicate an industry pivot toward high-performance, low-risk chemistries and application-specific portfolios.
Core strategic implications for 2026
-
Reformulation is inevitable—plan for capex and validation spend. Regulatory-driven substitution timelines require parallel investments in lab validation, field trials, and customer co-validation protocols. Treat reformulation programs like product-platform launches, not R&D experiments.
-
Secure feedstock diversity. Contracts for base oils and key additives, dual-sourcing strategies, and, where viable, backward integration into base-oil access will buffer margin exposure from supply shocks.
-
Service-led differentiation is a commercial multiplier. Bundling analytical services, fluid-management contracts, recycling or reclaim programs, and digital monitoring materially increases switching costs and improves lifetime margins.
-
Segmented go-to-market beats one-size-fits-all. OEM partnerships, high-value verticals (e.g., aerospace, medical device machining), and aftermarket service agreements reward specialized formulations and compliance documentation—areas where smaller specialist providers can outcompete scale players when they are agile.
-
M&A will be selective and tactical. Look for tuck-ins that add formulation IP, regional market access, or service capabilities rather than headline-grabbing consolidations. The mid-market remains most fertile for value-accretive deals.
What our report delivers — practical outputs for immediate use
PW Consulting’s full report is structured to move clients from insight to implementation. Highlights include:
-
Robust market-sizing and scenario forecasts through 2032, including upside/downside scenarios tied to regulatory and supply disruptions (macro numbers and scenarios are included in this preview; segmented figures and tables are available in the full report).
-
Competitive benchmark dossiers on leading suppliers, with capability maps, R&D positioning, and go-to-market vectors—focused on where each firm derives advantage and its likely strategic moves in the next 24 months.
-
Regulatory risk matrix and a compliance roadmap that maps jurisdictional changes to product action plans and costing models—designed for procurement, regulatory affairs, and product teams.
-
Supplier-supply-chain heatmaps: risk scoring by feedstock, single-source exposures, and recommended contracting approaches to mitigate 2026 base-oil scarcity risks.
-
Commercial playbooks: pricing levers, TCO calculators for customers, service-bundling models, and pilot program templates to accelerate adoption of new chemistries.
-
Innovation and investment toolkit: screening criteria for bio-based and neo-synthetic technologies, ROI models for fluid-management services, and an M&A checklist designed for rapid due diligence.
-
Field-trial protocols and data-capture templates to shorten validation cycles and translate lab gains into documented customer outcomes.
Actionable recommendations — 90/180/360 day agenda
-
90 days: Map critical suppliers; secure emergency supply agreements for base oils and priority additives; launch regulatory gap analysis for your core formulations.
-
180 days: Accelerate co-development pilots with 2–3 strategic customers in high-value verticals; pilot an integrated fluid-management service in at least one major account; implement TCO-based commercial messaging.
-
360 days: Consolidate portfolio by sunsetting non-compliant formulations, scale validated eco- and performance chemistries, deploy regional manufacturing or blending flexibility, and evaluate targeted M&A opportunities that close capability gaps.
A final note on positioning
This market rewards firms that combine formulation science with commercial rigor and regulatory foresight. Whether you are a global integrated supplier, a specialty formulator, or an investor assessing platform opportunities, the choices you make in 2026—around feedstock security, product reengineering, service packaging, and selective consolidation—will determine your market position as the industry moves toward a more sustainable, high-performance future.
PW Consulting’s full Metalworking Fluids Market report contains the segment-level tables, regional and application breakdowns, and granular competitive intelligence needed to execute confidently. This preview lays out the strategic landscape and our recommended response steps; the full dataset and playbooks are available through our report portal for teams ready to operationalize a 2026 strategy.
For detailed analysis of this topic, please visit the official page: Metal Working Fluids (Metalworking Fluids) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com