

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Metalworking Fluids Market set to hit USD 164.51 Million by 2032; 4.8% CAGR

Metalworking Fluids Market: Strategic Preview for 2026 Decision-Makers
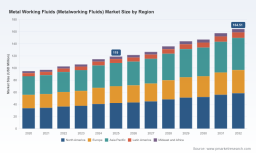
As manufacturers, chemical suppliers, and private-equity investors prepare their 2026 playbooks, the metalworking fluids (MWF) market demands attention. Our latest PW Consulting research frames this market as a steady-growth industrial staple undergoing rapid technical, regulatory, and supply-chain disruption. Between 2020 and 2025 the market expanded from a modest base to reach an aggregate value in the low triple-digits (USD Million scale), and our forward view projects a compound annual growth rate (CAGR) of 4.8% across the 2026–2032 forecast window—taking total market value materially higher by 2032. This is not a market for passive observation; it is an operational battleground where formulation science, regulatory agility, and supply-chain resilience will determine winners.
Metal Working Fluids (Metalworking Fluids) Market
Why this research matters for 2026 decisions
-
Timing matters: 2026 is the inflection point when regulatory, raw-material, and product-innovation pressures converge. Firms that act early to de-risk supply and re-orient portfolios toward the regulatory and sustainability vectors will secure durable margins.
Metal Working Fluids (Metalworking Fluids) Market -
Operational roadmaps outperform marketing promises: in a market growing at near-single-digit CAGR with persistent cost shocks, tangible improvements in tool life, sump life, and total cost of ownership (TCO) tip procurement decisions faster than branding alone.
Metal Working Fluids (Metalworking Fluids) Market -
Consolidation levers are available—but selective. Market concentration is moderate (the top three and top five players capture a meaningful share without monopolizing the value chain), creating opportunity for scale-seeking M&A as well as specialty plays around bio-based and high-performance synthetic niches.
Macro dynamics shaping 2026 strategies
Three structural forces will dominate market dynamics in 2026:
-
Regulatory acceleration: Local and supranational rulemaking is tightening controls on VOCs, formaldehyde, chlorinated paraffins, and PFAS-related risks. Examples include strengthened VOC limits in jurisdictions with aggressive air-quality programs and ongoing EU scrutiny on legacy additives. These changes increase reformulation costs and create technical barriers to entry for incumbents and newcomers alike.
-
Raw-material volatility: Industry intelligence points to a worsening base-oil supply environment in 2026. That shock amplifies input-cost risk for mineral-based formulations and shifts commercial incentive toward synthetics, bio-based blends, or higher-margin additive packages that enable price recovery.
-
Performance and service convergence: Customers increasingly demand integrated solutions—fluids plus lifecycle services such as testing, recycling, and fluid management—because operational uptime and environmental compliance are equally critical to their procurement decisions.
Competitive landscape — who’s doing what
The sector blends global integrated oil majors, specialty lubricants firms, and regional formulators. Our report spotlights strategic positioning across the value chain:
-
Major oil & chemical incumbents (e.g., Castrol, ExxonMobil, TotalEnergies): leveraging scale, R&D labs, and global distribution to push “eco-friendly” reformulations and broaden industrial channels. Recent product introductions emphasize compliance-forward chemistries and improved lifecycle performance—clear signals that portfolio transition is corporate strategy, not mere marketing.
-
Specialists and formulators (e.g., FUCHS, Houghton, Quaker, Blaser Swisslube): competing on technical differentiation—precision machining, extended sump life, and bespoke additive systems. These players are the primary beneficiaries of OEM co-development relationships for aerospace and high-performance automotive machining.
-
Additive and base oil suppliers (e.g., Chevron Phillips Chemical, Lubrizol, Clariant): tightening control over upstream inputs gives these firms leverage to influence formulation costs and speed-to-market for new chemistries.
-
Regional and niche producers (e.g., APAR, Tower, Master Fluid Solutions, Halocarbon): running rapid product-cycle programs to capture specialty pockets—especially where localized regulatory or performance requirements reward agility.
Recent product activity underscores the strategic shifts: major launches in 2025 and late 2025–2026 ranged from eco-focused fluid lines to neo-synthetic and bio-compatible formulations tailored for aerospace, defense, medical devices, and high-performance machining. These releases indicate an industry pivot toward high-performance, low-risk chemistries and application-specific portfolios.
Core strategic implications for 2026
-
Reformulation is inevitable—plan for capex and validation spend. Regulatory-driven substitution timelines require parallel investments in lab validation, field trials, and customer co-validation protocols. Treat reformulation programs like product-platform launches, not R&D experiments.
-
Secure feedstock diversity. Contracts for base oils and key additives, dual-sourcing strategies, and, where viable, backward integration into base-oil access will buffer margin exposure from supply shocks.
-
Service-led differentiation is a commercial multiplier. Bundling analytical services, fluid-management contracts, recycling or reclaim programs, and digital monitoring materially increases switching costs and improves lifetime margins.
-
Segmented go-to-market beats one-size-fits-all. OEM partnerships, high-value verticals (e.g., aerospace, medical device machining), and aftermarket service agreements reward specialized formulations and compliance documentation—areas where smaller specialist providers can outcompete scale players when they are agile.
-
M&A will be selective and tactical. Look for tuck-ins that add formulation IP, regional market access, or service capabilities rather than headline-grabbing consolidations. The mid-market remains most fertile for value-accretive deals.
What our report delivers — practical outputs for immediate use
PW Consulting’s full report is structured to move clients from insight to implementation. Highlights include:
-
Robust market-sizing and scenario forecasts through 2032, including upside/downside scenarios tied to regulatory and supply disruptions (macro numbers and scenarios are included in this preview; segmented figures and tables are available in the full report).
-
Competitive benchmark dossiers on leading suppliers, with capability maps, R&D positioning, and go-to-market vectors—focused on where each firm derives advantage and its likely strategic moves in the next 24 months.
-
Regulatory risk matrix and a compliance roadmap that maps jurisdictional changes to product action plans and costing models—designed for procurement, regulatory affairs, and product teams.
-
Supplier-supply-chain heatmaps: risk scoring by feedstock, single-source exposures, and recommended contracting approaches to mitigate 2026 base-oil scarcity risks.
-
Commercial playbooks: pricing levers, TCO calculators for customers, service-bundling models, and pilot program templates to accelerate adoption of new chemistries.
-
Innovation and investment toolkit: screening criteria for bio-based and neo-synthetic technologies, ROI models for fluid-management services, and an M&A checklist designed for rapid due diligence.
-
Field-trial protocols and data-capture templates to shorten validation cycles and translate lab gains into documented customer outcomes.
Actionable recommendations — 90/180/360 day agenda
-
90 days: Map critical suppliers; secure emergency supply agreements for base oils and priority additives; launch regulatory gap analysis for your core formulations.
-
180 days: Accelerate co-development pilots with 2–3 strategic customers in high-value verticals; pilot an integrated fluid-management service in at least one major account; implement TCO-based commercial messaging.
-
360 days: Consolidate portfolio by sunsetting non-compliant formulations, scale validated eco- and performance chemistries, deploy regional manufacturing or blending flexibility, and evaluate targeted M&A opportunities that close capability gaps.
A final note on positioning
This market rewards firms that combine formulation science with commercial rigor and regulatory foresight. Whether you are a global integrated supplier, a specialty formulator, or an investor assessing platform opportunities, the choices you make in 2026—around feedstock security, product reengineering, service packaging, and selective consolidation—will determine your market position as the industry moves toward a more sustainable, high-performance future.
PW Consulting’s full Metalworking Fluids Market report contains the segment-level tables, regional and application breakdowns, and granular competitive intelligence needed to execute confidently. This preview lays out the strategic landscape and our recommended response steps; the full dataset and playbooks are available through our report portal for teams ready to operationalize a 2026 strategy.
For detailed analysis of this topic, please visit the official page: Metal Working Fluids (Metalworking Fluids) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com