

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
R134A Market to Reach USD 246.2 Million by 2032; 4.3% CAGR (2026-2032) — PW Consulting

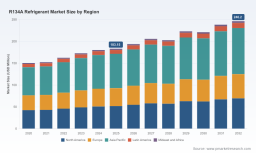
R134A Refrigerant Market: Strategic Implications for 2026 Decision‑Makers
PW Consulting’s latest R134A Refrigerant Market study (base year 2025; historical 2020–2025; forecast 2026–2032) is designed as an operational intelligence product for executive teams making allocation, product, and regulatory-compliance decisions in 2026. At the headline level, the global market has expanded steadily from the early 2020s and—under our central projection—continues to grow through the 2026–2032 forecast window at a compound annual growth rate of approximately 4.3%. Using 2025 as the reporting baseline (currency: USD, revenue unit: Million), the study supplies both the macro sizing and the scenario-driven projections you need to stress-test strategy under competing regulatory and supply scenarios.
R134A Refrigerant Market
Why this study matters in 2026
- Regulatory inflection points are now operational. Several U.S. rules affecting HFC import, labeling, and permitted uses execute or expand in 2025–2026, materially changing compliance and commercial pathways.
- Legacy-service demand (aftermarket, refrigeration servicing, and retrofits) remains a durable revenue pool even as new‑equipment specification shifts to lower‑GWP alternatives. Firms that balance legacy supply with transition solutions capture asymmetric margin opportunities.
- Upstream feedstock volatility and reclamation rules change cost and availability assumptions for producers and distributors; procurement strategy and working-capital models must be updated accordingly.
- Competitive positioning is fragmented: the market is not a concentrated oligopoly. This creates space for fast followers, niche providers, and technical-service specialists to scale quickly if they execute a clear go‑to‑market plan.
Key market dynamics shaping decisions in 2026
- Regulatory acceleration: U.S. regulatory actions enacted in 2025–2026 increase the compliance burden for HFC suppliers and reclaimers. New labeling and allowance requirements, technology transition restrictions, and proposals to extend reclamation and emissions controls to larger systems mean that regulatory readiness is a commercial differentiator. These actions shift value toward compliant reclaimers, retrofit-technology providers, and suppliers who can demonstrate traceable, labeled product flows.
- Transition pathways and retrofit economics: A two-track technical reality exists: new equipment increasingly specifies low‑GWP refrigerants, while existing installed bases require safe, cost-effective retrofit or ongoing service with legacy R134A. Recent retrofit technology developments allow staged transitions that reduce replacement costs for fleet owners and large refrigeration operators—creating an addressable aftermarket that remains economically attractive for several more years.
- Supply and cost pressures: Upstream fluorochemical feedstocks and intermediary chemistry prices have shown periodic upward pressure, putting margin stress on spot sellers and unhedged producers. At the same time, reclaiming and recycling represent both a compliance necessity and a margin-preserving lever for market participants.
- Commercial segmentation—buyers and channels: Demand originates from mobile A/C servicing, commercial refrigeration, and a range of industrial uses. The service channel dynamics—distributors, reclaimers, OEM service networks, and aftermarket specialists—are evolving quickly as regulation, product specs, and retrofit options shift.
Competitive landscape: who matters and what they are doing
The competitive map is defined by legacy fluorochemical producers, integrated chemical majors, regional manufacturers, and specialists in reclaim and retrofit technologies. Leading names in the space include multinational chemical companies with legacy R134A brands and dedicated aftermarket propositions, several large Chinese and Indian producers, and a set of engineering-led players focused on retrofit and low‑GWP migration technologies.
R134A Refrigerant Market
- Incumbent majors continue to play a dual role—maintaining legacy supply for the service market while commercializing low‑GWP alternatives and retrofit pathways. Recent strategic moves include alliance agreements and product expansions that increase the commercial footprint of lower‑GWP portfolios.
- Regional manufacturers are leveraging production scale and local distribution to defend and extend market share in price‑sensitive channels. Their cost position makes them critical partners for distributors and OEM remanufacturing operations.
- Retrofit and reclamation specialists are becoming transactional gatekeepers: the firms that can certify reclaim volumes, apply compliant labeling, and offer retrofit kits will capture a rising share of aftermarket economics.
Notable recent developments—illustrative of the competitive dynamic—include industry announcements of retrofit technology that facilitate safe conversion of legacy mobile A/C systems and commercial arrangements between major refrigerant producers to expand lower‑GWP portfolios. These moves underscore a market where technology partnerships and channel alignments are as important as raw supply.
R134A Refrigerant Market
Market structure: concentration and opportunity
The R134A market is characterized by meaningful fragmentation among producers and sellers. The largest few players do not dominate to the extent seen in some chemical markets; top-three shares and top-five shares point to a landscape where mid‑tier and regional players retain significant collective power. For decision‑makers this means that targeted M&A, selective capacity investments, or well-timed commercial partnerships can materially shift competitive standing within a short strategic window.
Strategic imperatives for 2026
Based on our integrated market model and regulatory scenario analysis, we recommend the following prioritized actions for companies engaged in or adjacent to the R134A ecosystem:
- Adopt a dual‑track product strategy: Retain assured legacy supply and aftermarket servicing capabilities while accelerating commercialization of retrofit technologies and low‑GWP alternatives. Create commercially distinct offers for “service‑grade” R134A and transition‑grade solutions.
- Invest in compliant reclamation and labeling capabilities: The 2026 labeling and reclaim rules create a premium on traceability. Firms that can certify volumes and demonstrate compliant chain‑of‑custody will command better access to regulated channels and preferred supplier status with large end users.
- Hedge feedstock and diversify procurement: Upstream cost volatility is non‑trivial; strategic procurement, forward contracting, and selective vertical integration can protect margins in 2026 and beyond.
- Forge OEM and channel partnerships: Close alignment with OEMs, service networks, and large refrigeration fleet operators accelerates acceptance of retrofit kits and certified low‑GWP replacements—crucial for scaling transition revenues.
- Pursue targeted M&A and tech partnerships: Prioritize acquisitions that add reclaim capacity, retrofit IP, or regional logistical muscle. These assets provide tangible synergies and shorten the path to compliance‑ready commercial models.
- Scenario planning and stress testing: Run at least three commercial scenarios in 2026 planning cycles—baseline policy trajectory, accelerated phase‑down, and supply‑shock—to stress-test headroom on price, margin, and working capital.
What PW Consulting’s full report delivers (operational detail)
- Market sizing and forecasting model (historical 2020–2025; forecast 2026–2032) with downloadable data tables and interactive scenario toggles reflecting regulatory and feedstock shocks.
- Regulatory-impact matrix that quantifies near‑term compliance costs, operational changes for reclaimers, and the commercial effect of labeling and technology transition rules.
- Competitor playbooks and vendor profiles covering legacy producers, regional manufacturers, and retrofit/reclaim specialists—assessing capabilities, channel access, and strategic intent.
- Supply‑chain risk heatmap and procurement playbook that translates feedstock indicators into procurement triggers and inventory policies.
- Commercial go‑to‑market playbooks for OEM partnerships, retrofit commercialization, and aftermarket channel optimization.
- M&A shortlist and valuation priors for bolt‑on targets (reclaimers, retrofit IP holders, regional distribution platforms).
- Executive dashboard with key leading indicators to monitor through 2026—policy milestones, feedstock indices, reclaim volumes, and aftermarket demand signals.
Note: This preview intentionally omits the granular regional and application split tables and specific sub‑segment price curves that are included in the full study. Those core data layers are provided in the premium dataset and interactive model because they are the actionable elements procurement, commercial, and M&A teams rely on to execute in 2026.
How to use this intelligence in your 2026 planning cycle
- Use the report’s scenarios to set guardrails for capital allocation and inventory policy aligned with the most probable regulatory pathway.
- Prioritize short-cycle initiatives that protect aftermarket margins (licensed retrofit kits, certified reclaim programs) while sequencing longer-term investments (capacity upgrades, low‑GWP production) against policy clarity.
- Leverage the competitor playbooks to identify white‑space partnerships—e.g., co‑branding retrofit solutions with distributors or acquiring regional reclaimers to secure compliant feedstock.
PW Consulting’s R134A Refrigerant Market study is built to be operational: not just descriptive market intelligence, but a playbook for action in 2026. For procurement directors, commercial heads, and strategy teams, the combination of our market model, regulatory-impact quantification, competitive playbooks, and M&A priors forms the evidence base needed to make high‑confidence decisions in a fast‑moving regulatory and technical environment.
To access the full dataset, interactive models, and the withheld regional/application level intelligence that will inform precise sourcing, pricing, and M&A decisions, contact PW Consulting or visit our reports portal for licensing and bespoke advisory options.
For detailed analysis of this topic, please visit the official page: R134A Refrigerant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com