

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 3D Laser Scanners Market to Reach USD 346.04 Million by 2032 at 6.98% CAGR

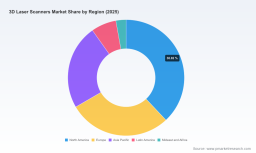
3D Laser Scanners Market — Strategic Outlook for 2026 Decision‑Makers
As organizations reassess capital allocation, digitalization roadmaps, and field operations for 2026, 3D laser scanning is no longer a niche enabler: it is a capabilities backbone across surveying, manufacturing, construction, forensics, and cultural‑heritage projects. PW Consulting’s new market study synthesizes macro trajectory, competitive dynamics, standards evolution, and procurement playbooks designed to inform high‑stakes decisions in the coming 12–36 months. This preview explains why the study is strategically material for 2026 planning while preserving the proprietary, segment‑level intelligence that we reserve for subscribers.
3D Laser Scanners Market
Macroeconomic Trajectory: an expanding but heterogeneous market
Anchored on a 2025 base year, the 3D laser scanners global market is projected to grow at a compound annual growth rate (CAGR) of 6.98% over the 2026–2032 forecast window. On a headline basis this trajectory accelerates the market from mid‑hundreds of millions in 2025 toward the high‑hundreds by 2032 (all values expressed in Million USD). That rate reflects steady expansion driven by broader adoption of as‑built capture in construction, rising demand for metrology‑grade portable scanners in manufacturing, and the scaling of mobile and airborne LiDAR for infrastructure and environmental mapping.
3D Laser Scanners Market
Two structural features matter for decision‑makers. First, the market remains fragmented: the three‑firm and five‑firm concentration ratios are relatively low, indicating many regional and niche specialists still compete meaningfully alongside global OEMs. Second, growth is uneven across use cases and form factors — some pockets are maturing quickly, others are early‑adopter territory — which creates both upside opportunities and procurement complexity when defining specifications and TCO expectations.
3D Laser Scanners Market
Why this study matters for 2026 strategic decisions
-
CapEx and procurement timing: Our analysis aligns vendor roadmaps, firmware and certification cycles, and the likely price curve so procurement teams can decide whether to accelerate purchases before major product refreshes or defer to secure improved value.
-
Vendor selection and risk mitigation: With a fragmented supplier base, vendor choice critically affects long‑term serviceability and data traceability. The study maps qualifications, metrology certifications, and calibration ecosystems to reduce operational risk.
-
Operational design: For field managers, we translate scanning productivity and post‑processing throughput into project‑level labor and software cost drivers, enabling realistic budgeting for large scan programs.
-
Regulation and admissibility: For forensic, infrastructure, and regulated sectors, the report aligns scanner capabilities to emerging standards and evidence‑admissibility frameworks, helping legal and compliance teams preempt challenges.
What the full report contains (practical, executable content)
-
Market sizing and forecast model (2020–2032 base), including scenario analysis that isolates high‑adoption and constrained‑growth outcomes relevant to procurement cycles in 2026.
-
Vendor scorecards that compare product classes across metrology performance, calibration traceability, ecosystem services, global support footprint, and upgrade latency.
-
Procurement playbook: decision trees for CAPEX vs. OPEX choices, tradeoffs between handheld, terrestrial, mobile and airborne platforms for common program archetypes, and contractual clauses to secure firmware/driver update commitments.
-
Project costing templates that translate scan density, point cloud volume, and post‑processing time into labor and storage budgets — calibrated to our primary research across 2020–2025 projects.
-
Regulatory alignment annex: practical checklists tied to OSAC, ISO 10360‑13, ISO 17123‑9, VDI/VDE standards, and laboratory accreditation expectations for traceability and forensic acceptance.
-
Investment briefings for corporate development teams focusing on consolidation targets, technology integration acquirers, and ecosystem plays around software and analytics for scanned data.
Competitive landscape — who matters and why
The vendor ecosystem combines global platform leaders, metrology‑grade specialists, and agile challengers. The full study profiles each major OEM and a curated set of regional challengers to help readers map fit‑for‑purpose partners.
-
Creaform: A recognized leader in portable metrology scanners, Creaform’s recent refresh of its handheld lineup underscores a strategy focused on ISO‑aligned certifications and vertical integration for inspection workflows. Their emphasis on handheld metrology aims at manufacturing and quality control applications where traceable accuracy and service assurance command premium pricing.
-
Artec 3D: With iterative optics and metrology certifications for its portable offerings, Artec is signaling a push to bridge high‑accuracy object capture and site documentation. Their 2026 Spider II update reflects a product strategy built around certified accuracy and measurement stability — important for forensic and reverse‑engineering use cases.
-
FARO Technologies: FARO continues to invest in firmware and processing workflows for its Focus line, lowering operational friction in field‑to‑deliverable pipelines. Firmware updates and cloud integration reduce lifecycle costs for repeat installers and large project contractors.
-
Hexagon, Leica, Trimble, RIEGL, Topcon: These legacy players are differentiated by broad systems portfolios (GNSS, total stations, software), channel depth, and service networks. Their competitive moat lies in integrated workflows for surveying and infrastructure projects where end‑to‑end solutions simplify procurement and support long engagement cycles.
-
China‑based OEMs (SHINING 3D, SCANOLOGY, 3DMakerpro, Revopoint, others): These vendors are expanding rapidly on price‑performance and targeted certifications. Select models now come with accredited calibration labs and ISO/IEC 17025 traceability, narrowing the historical gap with established metrology incumbents and offering high value for mid‑market customers.
Recent vendor activity in late 2024–early 2026 — including product refreshes, firmware improvements, and new LiDAR introductions — materially affects procurement timing and upgrade planning. The full report links each product move to risk and opportunity matrices for enterprise buyers.
Regulatory and operational dynamics that will shape adoption
Standards and accreditation are a central theme for 2026. OSAC guidance for forensic scene capture, ISO 10360‑13 for handheld measurement verification, and persistent reliance on ISO 17123‑9 for terrestrial performance evaluation collectively raise the bar for traceability. VDI/VDE frameworks and ISO/IEC 17025 laboratory accreditation are increasingly required by customers who must demonstrate defensible measurement chains. Our analysis explains how to operationalize these requirements — from vendor SLAs to in‑house reverification schedules — without ballooning program costs.
On cost drivers, our primary research shows that project size and complexity dominate total program spend: labor for data capture and processing, not hardware list price alone, becomes the marginal cost for scaled scanning programs. This is important because many procurement exercises focus excessively on device CAPEX while underweighting lifecycle labor and cloud storage costs.
Practical recommendations for 2026 procurement and investment
-
Adopt a capability‑based specification: define accuracy, throughput, and certification requirements by use case rather than by platform type. This reduces the risk of over‑specifying and paying for unused precision.
-
Time purchases around vendor refresh cycles: minor firmware updates can meaningfully improve uptime and processing speed; major optical or sensor revisions justify delaying large CAPEX if operational needs permit.
-
Procure calibration and reverification services as an explicit line item: ensure traceability commitments and SLAs are contractually enforceable to preserve evidentiary value and resale considerations.
-
Model total cost of ownership over a 5‑year horizon that includes labor scaling, cloud/compute, and the risk of obsolescence for niche tools in favor of modular ecosystems.
-
Consider software‑centric plays: vendors that lock in data workflows via analytics or SaaS post‑processing can shift value from hardware to recurring revenues — a factor for both strategic sourcing and M&A strategy.
How to use the full PW Consulting study
This article presents the strategic contours you need to prioritize decisions in 2026: growth rate, market structure, standards pressures, and vendor dynamics. For executable procurement templates, vendor scorecards, and the proprietary segment‑level intelligence that maps device classes to specific industry use cases and regional demand patterns, please consult the full report. We intentionally keep granular splits and certain segment‑level metrics exclusive to the subscription product to preserve the actionable insight you need to operationalize these recommendations.
PW Consulting’s 3D Laser Scanners Market study is designed for chief procurement officers, operations leads, legal/compliance counsels in regulated industries, and M&A/strategy teams targeting the sensor and geospatial value chain. Armed with the full dataset and playbooks, organizations can convert the market’s steady CAGR and product‑cycle signals into concrete sourcing, deployment, and investment actions for 2026.
For detailed analysis of this topic, please visit the official page: 3D Laser Scanners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com