

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Thymidine Market to Reach USD 110.3 Million by 2032 at 3.1% CAGR

Thymidine Market 2026 Strategic Preview — What Leaders Must Know
Executive summary
As PW Consulting’s senior industry analyst, I present a concise, decision-focused preview of our full Thymidine Market research. The global market for thymidine — a foundational nucleoside used across antiviral drugs, nucleotide intermediates, DNA synthesis reagents and diagnostic kits — registered steady expansion through the 2020–2025 historical window and reached USD 89.2 Million (base year 2025). Our modelling points to a moderate but reliable compound annual growth rate (CAGR) of 3.1% across the 2026–2032 forecast horizon, taking the market to roughly USD 110.3 Million by 2032.
Thymidine Market
This briefing demonstrates the types of strategic intelligence embedded in the full report: an actionable view of demand drivers, supply-side structure and competitive positioning that matter for 2026 planning cycles. Per the “trailer” principle, we intentionally highlight implications and decision levers while withholding the granular segment-by-segment tables and proprietary supplier scorecards reserved for subscribers.
Thymidine Market
Why 2026 matters: a convergence of clinical, regulatory and supply shocks
Several forces converge as companies set strategy for 2026:
Thymidine Market
- Regulatory catalysts: Late-2025 and early-2026 regulatory events have raised the profile of thymidine-linked value chains. Recent approvals and authorisations for a therapy targeting thymidine kinase 2 deficiency create a credible pathway for elevated demand for GMP-grade nucleoside intermediates. Early commercial availability in core markets is expected to materialize in the first half of 2026, changing order patterns for specialized intermediates.
- Supply concentration and lead times: The upstream supply base is concentrated — the top producers control a material share of global volume — which has already manifested in extended lead times and spot-price volatility in 2024–2025. This structural feature amplifies the supply risk premium for buyers and creates arbitrage opportunities for new entrants or capacity expanders.
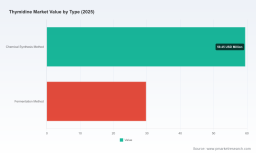
- Demand composition shifts: While historically driven by established antiviral APIs and research reagents, demand is becoming more bifurcated: high-purity, regulatory-compliant product for biopharma and cell therapy on one side; and cost-sensitive, fermentation-derived thymidine for diagnostics and bulk intermediates on the other. These are distinct commercial plays with different margin profiles and qualification timelines.
Market dynamics — what the numbers mean for strategy
Three implications from the macro trajectory (steady growth, moderate CAGR):
- Predictability with pockets of volatility. A 3.1% CAGR implies a reliable baseline market expansion but does not eliminate episodic supply shocks or one-off demand spikes tied to drug launches or regulatory pathways. Procurement strategies should therefore combine long-term contracts with tactical buffers.
- Segmentation drives margin dispersion. The aggregate market figure masks meaningful variation in customer willingness to pay and supplier margin expectations across GMP-grade vs. research-grade products, and between chemically synthesized and fermentation-derived materials. Strategic positioning should prioritize clarity on which segment a company will serve.
- Scale matters, but so does quality certification. Economies of scale will favor larger producers for commodity volumes, while regulatory-compliant, small-batch capabilities will be the gatekeeper for capturing upstream biopharma demand tied to novel therapeutics.
Competitive landscape — company-level takeaways
Below is a strategic snapshot of the leading and notable suppliers whose capabilities shape the market today. These notes synthesize firm profiles, public positioning and observable strategic moves; the full report contains calibrated strength/weakness matrices and supplier scorecards.
- Lonza Group (Switzerland) — A global reference for high-purity, GMP-grade thymidine and nucleotide intermediates. Lonza’s strength is trust in regulated supply chains and bespoke manufacturing for cell-therapy and biopharma customers. For buyers who require validated, audited sources and long-term supply reliability, incumbents with Lonza-like profiles reduce qualification risk but command a premium.
- Carbopharm GmbH (Austria) — Positioned largely as a laboratory and industrial supplier providing standard-grade thymidine. Their client base is research institutions and industrial synthesis users. Carbopharm is a strategic partner for organizations prioritizing breadth of catalog and steady availability over bespoke GMP services.
- ST Pharm Co., Ltd. (South Korea) — Serves antiviral and biopharma intermediate markets; their regional advantages and technical know-how make them attractive partners for Asia-Pacific vaccine and antiviral developers. Expect them to pursue tightened regional partnerships and potential capability upgrades to capture higher-value GMP work.
- Zhejiang NHU Co., Ltd. (China) — Notable for dual-route manufacturing (fermentation and chemical synthesis). This operational flexibility gives NHU a cost and capacity advantage for DNA synthesis reagents and large-volume intermediates, as well as resilience to raw-material feedstock swings.
- Zhejiang Xianfeng Science Technology; Anhui Golden Sun Biopharmaceuticals; Hebei Anminuo; Ducheng; Chengzhi (China) — Together, these firms form a robust supply cluster that competes on cost, volume and responsiveness. Several have invested in fermentation platforms to reduce unit costs. For global buyers, these suppliers are attractive for non-GMP or bulk needs but often require additional qualification steps, audits and governance protocols when serving regulated biopharma customers.
Strategic playbook for 2026 decision-makers
Based on our scenario modelling and supplier intelligence, here are prioritized actions for different stakeholders heading into 2026 planning cycles.
- For CPOs and procurement leads: Implement a three-tier sourcing approach — secure at least one audited GMP supplier for critical pathways, maintain a cost-effective secondary supplier for non-regulated volumes, and contract a contingency partner in a different geography to mitigate geography-specific disruptions. Re-negotiate lead times and consider inventory as insurance for key launch windows.
- For manufacturing and technical teams: Accelerate supplier qualification timelines for fermentation-derived intermediates if sustainability and cost are strategic priorities. Invest in analytical method harmonisation to shorten qualification cycles across suppliers.
- For corporate development and investors: Seek bolt-on assets that add either GMP-compliant capacity or unique fermentation IP. M&A targets should be evaluated against a matrix that combines compliance readiness, customer concentration and technical pathway differentiation.
- For biotech and pharma portfolio managers: Map your drug development milestones against supplier qualification lead times. For therapies dependent on thymidine-related intermediates — especially therapies tied to regulatory tailwinds — early supplier engagement and co-investment in capacity can be deal-accelerating.
What the full PW Consulting Thymidine Market report delivers
The full study is engineered to convert market intelligence into executable actions. Highlights include:
- Detailed market sizing (2020–2032) with scenario-based forecasts and sensitivity analysis to price and launch timing.
- Supply-chain maps showing manufacturing routes, input dependencies and logistical choke points.
- Supplier scorecards and audit-readiness assessments for the leading producers (technical, quality, capacity, commercial terms).
- Pricing model templates that allow buyers and sellers to stress-test margins under different raw-material and regulation scenarios.
- Go-to-market playbooks for entering premium GMP and low-cost bulk segments, including recommended qualification timelines and contract language.
- M&A and partnership heatmaps identifying attractive acquisition criteria and integration risks.
Note: This preview intentionally omits the granular breakdowns and proprietary segmentation tables (including regional and application-level share tables and raw numerical splits) that underpin our supplier rankings. Those analytics are part of the subscriber report and support tactical execution.
Risk matrix and watchlist for 2026
- Regulatory acceleration: New approvals for therapies related to thymidine metabolism can create abrupt demand spikes; monitor therapy rollouts and payer decisions closely.
- Supply bottlenecks: Concentration at the top of the supply chain creates outsized lead-time risk — buyers should expect intermittent spot-price surges.
- Quality and compliance: Rapidly on-shoring or pivoting of suppliers to meet demand for GMP-grade products can mask quality gaps; rigorous audit and analytics are non-negotiable.
- Geopolitical and trade risk: Cross-border flows of intermediates and precursor chemicals remain sensitive to export controls and tariffs; diversify geography where feasible.
How PW Consulting can support your 2026 planning
If your 2026 decisions depend on reliable thymidine supply, regulatory timing, or supplier selection, the full PW Consulting report provides the executable intelligence and templates to act. The preview above outlines our core conclusions: a modestly growing market, structural supply concentration, and a bifurcated commercial landscape that rewards clarity of strategy.
To access the full data tables, supplier scorecards, and a downloadable procurement playbook, visit our full report page. PW Consulting’s advisory teams are available to run a tailored workshop to convert the report’s insights into a 90-day operational plan aligned to your launch and procurement calendars.
For detailed analysis of this topic, please visit the official page: Thymidine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com