

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Diamond Saw Blades Market to reach USD 10,620 Million by 2032 at 2.41% CAGR

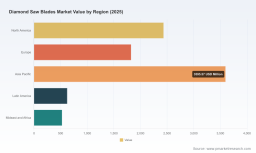
Diamond Saw Blades Market — Strategic Briefing for 2026 Decisions
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a concise, high-impact preview of our comprehensive Diamond Saw Blades Market study. This briefing synthesizes the highest-value, decision-facing insights executives and investors need to act in 2026 — while reserving the detailed segment-level datasets and models for the full report. The market reached approximately USD 9,000 Million in our base year (2025) after a steady recovery from 2020, and our scenario-aligned baseline projects a compound annual growth rate (CAGR) of 2.41% through the 2026–2032 forecast window, reaching just over USD 10.6 billion by 2032. Use this briefing to frame investment priorities, procurement strategies, and go-to-market choices in the coming 12–18 months.
Diamond Saw Blades Market
Why this report matters in 2026
-
Actionable clarity amid modest growth: The market’s low-to-mid single-digit CAGR signals a mature category where incremental gains—product premiumization, channel optimization, and supply-chain resilience—drive disproportionate margin improvements.
Diamond Saw Blades Market -
Capital allocation and M&A timing: With limited top-tier concentration (CR3 ≈ 24.6% and CR5 ≈ 32.0%), there is room for consolidation playbooks that combine scale with niche technology acquisitions. Private equity and corporate strategists must balance scale economics against specialty margins.
Diamond Saw Blades Market -
Operational risk and supplier strategy: Raw material sourcing and regional manufacturing footprints are decisive: disruptions or regulatory shifts in synthetic diamond sourcing or facility closures can rapidly reshape cost curves and lead times.
-
Procurement & product decisions tied to regulation and automation trends: Buyers will increasingly prefer precision blades that reduce rework and energy use in automated cutting lines—presenting a premiumization pathway for leading vendors.
Macro and demand dynamics shaping 2026 tactics
-
Recovery then normalization: The market expanded from the lower levels recorded in 2020 to USD 9,000 Million in 2025, reflecting cyclical construction recovery, higher renovation activity, and selective industrial capex. From 2026 onward, expect steady but uneven growth driven by infrastructure programs and specialty industrial demand.
-
Precision and automation adoption: Labor shortages and energy-efficiency mandates are accelerating uptake of higher-grade, precision-engineered blades in masonry and concrete applications. Buyers reward longer life, lower dust generation, and compatibility with automated equipment.
-
Raw material concentration and trade sensitivity: Synthetic diamonds — the primary abrasive segment material — are commercially sourced from a limited set of countries. U.S. customs and regulatory developments (recent rulings identify key sourcing origins) heighten geopolitical and compliance risk for buyers and manufacturers alike.
-
Regulatory and safety factors: Practical standards and mounting protocols (e.g., mandatory secure mounting and torqueing guidelines) influence product design and aftermarket support needs. Compliance-driven product improvements create differentiation windows.
Competitive landscape — what the market structure implies for competitors
The competitive field is a mix of established industrial tool businesses, regional specialists, and digitally native direct-to-contractor suppliers. No single player dominates; rather, a top-five cohort captures roughly a third of market revenue, leaving meaningful market share for strong regional brands and OEM-suppliers. Below I summarize strategic positioning and implications for the named players we track.
-
Diamond Products Limited (Elyria, OH) — Known for premium wet/dry segmented, continuous rim, and turbo blades. Strength: deep application engineering for concrete and pavement. Strategic levers: expand service programs and retrofit offerings for rental fleets.
-
MK Diamond Products (Santa Fe Springs, CA) — Professional-grade blades and core bits with strong contractor channels. Strength: brand trust among masonry professionals. Strategic levers: scale consumables subscription for equipment rental and construction firms.
-
Husqvarna Construction Division (Stockholm) — Premium product breadth for concrete, asphalt, brick, and stone. Notably, Husqvarna has announced intent to exit non-core stone diamond tools by end-2026, implying potential asset carve-outs or contract manufacturing opportunities for competitors.
-
Bosch Power Tools (Gerlingen) — Strong distribution and aftermarket reach, supplying blades for circular saws and grinders. Strength: channel and cross-selling with power tools. Strategic levers: bundle blades with tool warranties and digital measuring systems.
-
Norton Abrasives / Saint-Gobain (Worcester, MA) — Industrial-grade blades and abrasives with emphasis on performance testing and safety guidelines. Strength: industrial OEM credibility. Strategic levers: certified performance programs for large construction and shipbuilding contractors.
-
Regional and specialty players — Companies such as Diamond Blade Warehouse, Patriot Diamond Blades, Random Products Inc., Vortex Diamond, Devour Tools, and Viraj Abrasives provide differentiated value via localized manufacturing, cost-competitive supply, or high-precision/laboratory-tested offerings. Strategic levers for these firms include vertical integration into core bits, laser-welded segment technologies, and targeted export strategies.
Recent market signals & implications
-
Trade show activity (late 2025–early 2026): Several manufacturers are highlighting new product ranges and market-facing demos at European and global expos—indicating renewed focus on product differentiation and direct customer engagement.
-
Product launches and educational content: Vendors are releasing tiler-focused catalogs and step-by-step cutting tutorials, signaling a push to educate end-users and reduce price elasticity through perceived value.
-
Firm-level strategic shifts: Husqvarna’s announced withdrawals create near-term supply and aftermarket service discontinuities in specific geographies, opening acquisition targets and contract manufacturing bids for competitors seeking scale.
Strategic playbook — five priority actions for 2026
-
Supply chain resilience and dual-sourcing: Map synthetic diamond supply and secure secondary sources across jurisdictions. Consider inventory-indexed procurement contracts to hedge against regional disruptions and customs rulings.
-
Premiumization tied to automation: Invest in R&D for low-dust, long-life bonds and laser-welded segment technology; align go-to-market with OEMs of automated cutting lines to create bundled value propositions.
-
Aftermarket and service-driven margins: Build certified reconditioning programs, parts-as-a-service, and training bundles that lock customers into longer lifecycle relationships and recurring revenue.
-
M&A and asset-light plays: Evaluate tuck-ins—especially in geographies impacted by manufacturing shutdowns—and opportunistic acquisitions of Husqvarna’s non-core assets where permissible. Also consider contract manufacturing partnerships to capture displaced demand quickly.
-
Digital enablement and channel optimization: Accelerate e-commerce channels for small contractors, introduce predictive replacement algorithms in mobile apps, and create SKU rationalization to reduce inventory cost while improving fill rates.
What the full PW Consulting report contains (select highlights)
-
Comprehensive market sizing and forecast model (2020–2032) with scenario sensitivity and price-volume breakdowns for strategic planning.
-
Segment and application demand analysis (type, application, and region) with demand-driver overlays and elasticities—note: core segment-level datasets and percentage splits are available in the full report only.
-
Supplier and value-chain map that identifies single-source exposures, manufacturing footprints, and transportation chokepoints.
-
Company profiles and capability heatmaps for leading and emerging suppliers, including strategic SWOTs and inorganic opportunity matrices.
-
Commercial playbooks: procurement negotiation scripts, go-to-market bundles, aftermarket pricing strategies, and a prioritized two-year implementation roadmap.
-
Regulation & compliance tracker tying customs rulings, safety standards, and country-level manufacturing changes to operational impacts and cost modeling.
-
Interactive dashboards and downloadable models to run “what-if” scenarios on commodity price shocks, equipment automation penetration, and regional demand swings.
Final practical guidance for 2026
For executives allocating capital in 2026, the priority is clear: focus on selectively captured premium pockets, shore up raw-material sourcing, and position for consolidation opportunities arising from strategic exits and facility closures. The overall market’s modest growth profile rewards disciplined, operationally led expansion rather than broad-basin investment. Procurement teams should convert supplier relationships into risk-sharing agreements, while product teams must accelerate innovations that link blade performance to automated and energy-constrained production lines.
PW Consulting’s full report delivers the granular segment analyses, regional datasets, supplier-level figures, and executable templates that underpin these strategic conclusions. If you are planning capital projects, sourcing transformation, product launches, or M&A activity in 2026, the full dataset and scenario tools will materially sharpen your risk-adjusted choices.
Contact PW Consulting to access the full Diamond Saw Blades Market report and the accompanying interactive models. Our analysts are available to run tailored briefings and scenario workshops for your executive team.
For detailed analysis of this topic, please visit the official page: Diamond Saw Blades Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com