

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Steel Piston Market to hit USD 1,114M by 2032 at 4.2% CAGR

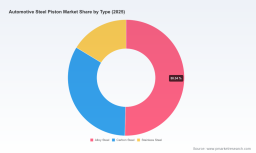
Automotive Steel Piston Market — Strategic Outlook for 2026 Decision-Makers
Executive summary
As global powertrain strategies diversify through 2026 and beyond, steel pistons retain a critical strategic role across commercial and high-performance internal combustion platforms. Our PW Consulting Automotive Steel Piston Market study (base year 2025; forecast period 2026–2032) synthesizes five years of historical performance with a robust forward view driven by material- and system-level dynamics. The market has shown steady expansion in the early 2020s and, under present assumptions, will continue to grow at an aggregate CAGR of 4.2% through the forecast window. This trajectory underpins near-term investment decisions for OEMs, tier‑1 suppliers, and private equity players positioning for durability- and performance-led segments of the mobility ecosystem.
Automotive Steel Piston Market
Why this study matters for 2026 strategic planning
-
Material decisions now determine multi-year product roadmaps. Steel piston technologies — from friction‑welded monoblocs to laser-welded, multilayer designs — are increasingly chosen to meet peak cylinder pressures, extended service lives, and targeted CO2 reductions in heavy-duty and specialist passenger applications.
Automotive Steel Piston Market -
Capital allocation needs clarity on market scale and momentum. Our base-year 2025 sizing and the 2026–2032 forecast provide executives with the macro envelope necessary to size R&D spends, capacity builds, and M&A targets without relying on piecemeal supplier anecdotes.
Automotive Steel Piston Market -
Regulatory and lifecycle pressures make material-level optimization a P&L lever. Proven steel-piston architectures today contribute to emission and efficiency gains that have measurable implications for compliance timelines and residual value assumptions.
Market dynamics: what is driving demand
The steel piston market is being shaped by several converging forces that are highly relevant for 2026 decisions:
-
Performance thresholds in heavy-duty diesel platforms. Engineering requirements for peak ignition pressures — in certain applications approaching 300 bar — and the need for longevity under extreme duty cycles keep steel in active consideration where lightweight aluminum cannot deliver the required robustness.
-
Technical differentiation through joining and surface technologies. Friction‑welded, laser‑welded and other advanced manufacturing approaches enable lower compression heights, improved thermal management and reduced friction losses — all factors that translate into fuel efficiency and CO2 advantages at the system level.
-
Operational life and total cost of ownership. Field data and manufacturer claims indicate steel piston systems can deliver exceptionally long service lives — in some commercial platforms exceeding one million kilometers — reducing downtime, rebuild costs and lifecycle emissions when compared to frequent replacement cycles.
-
Material-technology synergy for emissions compliance. Optimized steel piston solutions contribute to CO2 reduction potential through improved friction and thermal behaviours and can be an integral component of broader combustion optimization packages.
Competitive landscape — strategic implications
The competitive field blends long-established automotive suppliers with regionally focused specialists. Market share concentration is low‑to‑moderate (CR3 approximately 35%; CR5 approximately 38%), highlighting a market that is neither fully commoditized nor tightly consolidated — a pattern that favors both organic differentiation and targeted consolidation plays.
Key players and strategic postures observed in the market include:
-
Mahle GmbH (Stuttgart, Germany) — Offers multiple steel piston concepts spanning passenger and commercial vehicles, with solutions tailored for extreme peak pressures and advanced cooling strategies. Mahle’s emphasis on laser‑welded architectures highlights the importance of minimizing compression height while optimizing thermal paths for reduced frictional losses.
-
KS Kolbenschmidt Pistons (KSPG AG / Rheinmetall Automotive) — Positions steel piston systems as enablers of CO2 reduction at the system level, with engineered add-ons that claim up to a 4% reduction in CO2 under specific conditions. Their approach underscores the need for suppliers to couple material expertise with subsystem calibration and emissions engineering.
-
Tenneco Inc. — Focuses on friction‑welded Monosteel® one‑piece pistons for large‑bore engines, demonstrating that manufacturing method and scale compatibility remain central to commercial viability in the heavy‑duty segment.
-
Aisin Seiki Co., Ltd. and Hitachi Astemo, Ltd. — Both maintain OEM-facing portfolios that integrate steel piston solutions into broader engine systems, signalling the persistence of integrated supply chains and the strategic value of platform-level partnerships.
-
Shriram Pistons & Rings Ltd. — Represents regionally specialized suppliers with forged steel capabilities focused on heavy-truck platforms, pointing to localization strategies for cost, service and market access.
Practical implications for different player types
Our analysis delivers differentiated recommendations depending on the stakeholder’s role:
-
OEMs — Treat steel piston selection as a systems engineering decision, not merely a bill‑of‑materials choice. Assess supplier roadmaps for joining technologies and cooling strategies alongside combustion calibration plans to realize measurable CO2 and TCO benefits.
-
Tier‑1 suppliers — Invest selectively in manufacturing capabilities (friction‑welding, laser welding, precision forging) where they create defensible margins and speed-to‑market. Consider modular product platforms that allow material substitution between steel and other alloys without disrupting downstream integration.
-
Private capital — Look for consolidation targets in the lower‑tier supply base where scale can be achieved through bolt‑on capacity and through the transfer of advanced joining technologies to higher‑margin applications.
-
Policy and procurement teams — Insist on validated field performance metrics (e.g., service life, friction loss, CO2 equivalence) rather than supplier assertions alone, and build contractual incentives that capture realized durability and efficiency benefits.
Report contents — what you will find in the full study
The PW Consulting Automotive Steel Piston Market report is designed as an operational playbook for 2026 decision cycles. Highlights include:
-
Comprehensive market sizing and trend analysis with historical performance (2020–2025) and a detailed forecast through 2032, presented with scenario sensitivity to fuel‑price, regulation and adoption assumptions.
-
Technology deep dives into manufacturing processes (friction‑welding, laser‑welding, forging), material selection rationale, and subsystem impacts on friction, cooling and combustion efficiency.
-
Competitive profiles and benchmarked capabilities of the major established suppliers, focused on product architecture, manufacturing footprint, and partnerships — enabling shortlisting for supplier dialogues or M&A screening.
-
Strategic playbooks for OEMs and suppliers covering go‑to‑market, capacity strategies, and R&D prioritization, with implementation checklists and investment decision matrices.
-
Risk and sensitivity matrices that quantify the upside and downside to market size across regulatory scenarios and powertrain transition paths.
2026 action guide — three near-term moves
-
Prioritize platform‑level testing — Validate steel‑piston options within representative engine architectures under real duty cycles to quantify frictional and thermal benefits and to convert supplier claims into contractual KPIs.
-
Lock in manufacturing optionality — Where lead times and capital intensity permit, create dual-sourcing corridors and invest in flexible joining technologies to move quickly between aluminum and steel options as regulation or duty requirements evolve.
-
Seek targeted consolidation — For investors and strategic buyers, focus on acquiring specialists with proprietary joining tech or onshore capabilities that shorten supply chains for critical commercial‑vehicle platforms.
Preview vs. full intelligence
This article is intentionally crafted as a strategic preview: it surfaces the market’s macro trajectory, competitive themes, and tactical priorities to help inform 2026 planning. To preserve the value of detailed, transaction‑ready intelligence, we have withheld granular segment breakdowns and the full set of regional and application‑level financial details that underpin our recommendations. Those granular tables, supplier‑level cost curves, and scenario worksheets are available in the complete PW Consulting report.
Closing — how PW Consulting can support your 2026 roadmap
Decisions made in 2026 about material choices, manufacturing footprints, and supplier relationships will determine competitiveness for years. Our Automotive Steel Piston Market study provides the quantitative baseline and the operational playbooks required to translate material science and manufacturing advances into measurable business outcomes. For executives preparing investment memoranda, RFPs, or integration plans, PW Consulting offers tailored briefings, model walkthroughs, and supplier diligence services to accelerate decision velocity while reducing execution risk.
Request the full report and proprietary appendices for access to the detailed segmentation, regional economics, supplier cost models and scenario analyses that underpin the findings summarized here.
For detailed analysis of this topic, please visit the official page: Automotive Steel Piston Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com