

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Wear Plate Market to Expand at 6.7% CAGR Through 2032 — PW Consulting

Wear Plate Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present an executive-level primer on our new Wear Plate Market study. This briefing summarizes the strategic imperatives and tactical levers managers must understand heading into 2026, grounded in our proprietary analysis (base year 2025, historical window 2020–2025, forecast horizon 2026–2032). The full report contains the granular datasets, segmented scenarios, and supplier scorecards that procurement, product, and corporate development teams will need to operationalize these insights.
Wear Plate Market
Why this study matters for 2026
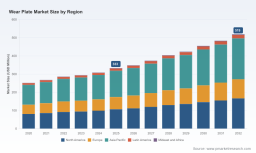
The wear plate sector sits at the nexus of heavy industry durability economics and emerging regulatory pressure. Our modelling shows the global market expanding steadily from the low‑hundreds of millions in 2020 to an expected USD 333 million in 2025, and continuing on a compound annual growth pathway of 6.7% through our forecast window. By 2032 the market approaches roughly USD 519 million. That trajectory signals more than healthy demand — it points to persistent opportunity for innovation in materials, extended-life solutions, and supply-chain reconfiguration.
Wear Plate Market
For leadership teams planning 2026 CapEx, product roadmaps, or M&A activities, the core strategic question is not whether the market is growing, but where value will accrue: to vertically integrated producers who can lower total cost of ownership (TCO), to specialty suppliers who differentiate on service and engineering, or to new entrants exploiting modular hardfacing and hybrid material systems. This study is engineered to help you prioritize those bets with quantitative rigor and pragmatic pathways to capture share.
Wear Plate Market
Macro trajectory and what it signals
-
Momentum and resilience: Historical analysis (2020–2025) shows consistent expansion despite cyclical pressures in mining and construction equipment markets. That resilience reflects both replacement demand and the economics of lifecycle optimization — customers increasingly pay up front for wear solutions that reduce downtime and maintenance cost.
-
Mid‑term opportunity set (2026–2032): Our base forecast translates the market’s 6.7% CAGR into practical timelines for new product introductions, capacity investments, and aftermarket partnerships. Suppliers with a near‑term capability to demonstrate measurable service‑life improvements will disproportionately capture aftermarket spend.
-
Market concentration: The sector remains moderately fragmented; top producers do not dominate to the extent seen in other heavy‑industrial inputs. Measured concentration metrics (CR3 and CR5) indicate space for consolidation, regional champions, and focused differentiators rather than winner‑take‑all dynamics.
What the report delivers — an operational playbook
This study is intentionally practical. Beyond forecasting, it contains the templates, analyses, and decision tools that procurement, engineering, and strategy teams can deploy immediately. Key deliverables include:
-
Scenario‑based forecasts (base case, upside, and downside) calibrated to commodity cycles and capital investment trends — enabling stress‑testing of budgets and production plans.
-
Supplier benchmarking and scorecards that combine technical capability, hardfacing expertise, service footprint, supply‑chain resilience, and commercial terms — designed for rapid RFP shortlisting.
-
Total cost of ownership (TCO) models with sensitivity levers for wear life, downtime cost, and retrofit cycle time — usable as negotiation tools with OEMs and third‑party fabricators.
-
Go‑to‑market playbooks for material substitution (e.g., steel overlays, ceramic inserts, polymer composites) and hybrid assemblies, including validation protocols and field test KPIs.
-
Regulatory impact matrix and compliance pathways — mapping how emerging mechanisms will affect imported overlay components, material sourcing, and carbon accounting across supplier tiers.
-
Deal architecture templates for joint development, licensing of hardfacing recipes, and carve‑out acquisition structures focused on capability capture rather than headline revenue.
-
Technical appendix with abrasion testing standards, weld overlay specifications, and retrofit engineering checklists to reduce adoption friction.
Competitive landscape — capability clusters and strategic moves
The report profiles established and specialist players, highlighting where competitive advantages are built and where disruption is most likely. A few illustrative company profiles and strategic takeaways:
-
Wear Plate USA (North Carolina, United States): A custom‑engineering leader in abrasion‑resistant parts, particularly for crushers and conveyors. Their strength lies in field‑proven design integration and aftermarket responsiveness — a playbook for firms that want to monetize application engineering rather than compete purely on price.
-
ASGCO Manufacturing (Allentown, Pennsylvania, United States): Notable for Chromium Carbide Overlay (CCO) and ceramic plate systems tailored to conveyor chutes and heavy wear points. Companies that bundle materials expertise with installation services are improving retention and margin capture.
-
JADCO Manufacturing (Harmony, Pennsylvania, United States): A recent product push in early 2025 introduced thinner CCO plates with tighter hardfacing bead control — a tactical innovation aimed at balancing weight, cost, and wear life for high‑throughput equipment. That launch illustrates how incremental product refinement can unlock price‑insensitive value in OEM replacement cycles.
-
Halden and Tianjin Leigong (China): These suppliers emphasize abrasion‑resistant steel and hardfacing consumables at scale. Their advantage is manufacturing breadth and cost competitiveness; strategic buyers will evaluate them against lead‑time, quality sustainability, and carbon footprint commitments.
-
Metco Joining & Cladding (Westbury, New York, United States): Specializes in welding overlays and hardfacing alloys – a reminder that specialized metallurgical know‑how remains a scarce capability with outsized commercial leverage for tailored applications.
Across these players, common themes emerge: engineering depth, service footprint, and the ability to prove life‑cycle economics are becoming as important as unit pricing. The study includes a supplier‑type matrix to help you match procurement needs to supplier archetypes.
Regulatory and supply‑chain inflection points
Two non‑market forces deserve explicit attention for 2026 planning:
-
Carbon pricing and trade measures: The EU’s Carbon Border Adjustment Mechanism (CBAM) is set to take effect in 2026 and will impose implicit carbon costs on imported goods. For wear plate buyers and manufacturers, this raises questions about the landed cost of imported overlay materials, near‑sourcing strategies, and supplier carbon disclosure. The report provides a compliance playbook that quantifies potential pass‑throughs and identifies low‑cost mitigation steps over a three‑year horizon.
-
Supply resilience and material inputs: Hardfacing wires, alloying elements, and ceramic feedstock availability influence lead times and margins. Our supplier risk heatmap helps companies prioritize inventory policy, dual‑sourcing, and technical substitution plans that preserve operational continuity without compromising performance.
How to use this intelligence in 2026 decisions
The study is structured to be actionable across three decision horizons:
-
Immediate (0–12 months): Use the TCO models and supplier scorecards to renegotiate master supply agreements, pilot high‑life wear systems on critical assets, and establish carbon reporting baselines for major imported inputs.
-
Near term (12–24 months): Validate material substitution pilots at scale, embed wear‑life KPIs into service contracts, and consider bolt‑on acquisitions that fill capability gaps (e.g., cladding expertise or regional fabrication centers).
-
Strategic (24–48 months): Pursue integrated service models combining supply, fitment, and predictive maintenance; evaluate regional capacity shifts driven by regulatory regimes; and consider platform plays that aggregate aftermarket demand across end‑use verticals.
What we intentionally withhold (and why)
To preserve the tactical edge for our clients and to follow the “preview” principle, this briefing demonstrates the analytical depth of the study but does not disclose the granular segmentation datasets (detailed regional splits, application shares, or material breakdowns). Those core micro‑datasets—essential for targeted procurement decisions, localized investment cases, and specific M&A screening—are included in the full report along with downloadable models. If your 2026 plan requires more than directional guidance, the full dataset is designed to plug directly into corporate planning tools.
Closing guidance — where to act first
-
Procurement leaders: Prioritize TCO renegotiations and establish two‑tier sourcing for critical inputs to hedge regulatory pass‑throughs.
-
Product and engineering teams: Accelerate field trials for hybrid overlay systems and quantify service‑life gains against retrofit costs.
-
Corporate development: Screen for small, capability‑rich targets in cladding and material science that can be integrated into service bundles.
-
Compliance and sustainability teams: Start scenario planning for CBAM implications and build supplier carbon visibility into contracts.
Our Wear Plate Market study is expressly built to convert market insight into 2026 action: validated forecasts, supplier playbooks, and technical validation protocols that reduce uncertainty and accelerate value capture. For decision‑makers preparing budgets, sourcing strategies, or M&A agendas for 2026, this research is the operational intelligence layer you can deploy immediately.
PW Consulting stands ready to workshop these findings with your cross‑functional team and to customize the datasets and models to your asset base, procurement profile, and regulatory footprint.
For detailed analysis of this topic, please visit the official page: Wear Plate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com