

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Thermoplastic Polyamide Market Set for 5.85% CAGR (2026–2032)

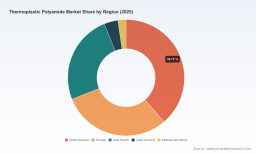
Thermoplastic Polyamide Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest Thermoplastic Polyamide Market study (base year 2025, forecast 2026–2032) provides a pragmatic, decision-focused roadmap for executives and strategy teams navigating the next phase of value creation in polyamide-based engineering polymers. The market, measured in USD Million, has expanded from a post‑pandemic base and reached roughly 2,215 USD Million in 2025. Under our central scenario—reflecting material substitution trends, regulatory shifts, and feedstock price dynamics—the market is expected to grow at a compound annual growth rate (CAGR) of 5.85% through 2032, reaching an estimated 3,290 USD Million by the end of the forecast horizon. Early 2026 figures point to a near-term market value of about 2,386 USD Million, underlining momentum entering the new planning cycle.
Thermoplastic Polyamide Market
Why this research matters for 2026 corporate decision-making
- Priority setting under uncertainty: 2026 is a year when many OEMs, compounders, and chemical majors will rebase their capital allocation and procurement plans. Our study translates market growth and volatility drivers into a prioritized set of investment and sourcing options.
- Supply‑chain resilience: Volatility in caprolactam and PA feedstocks has resumed. Executives need clear stress-tests and hedging strategies; the report maps supplier concentration, logistics chokepoints, and tariff exposures that materially affect margins.
- Regulatory and standards readiness: New tariff listings and emerging product standards are changing cost and compliance equations—this study decodes regulatory impacts and indicates where compliance spend becomes strategic rather than merely defensive.
- Commercial differentiation: As demand expands, winners will be those who convert technical capabilities (e.g., specialty PA12, bio‑circular PA11) into sustainable value propositions. The study identifies premium pockets and the commercial plays to capture them.
What the report delivers — practical components for action
- Robust historic and forecast market sizing (2020–2032) with scenario variants that reflect feedstock shocks, regulatory shifts, and accelerated electrification of mobility.
- Demand-driver analytics: material substitution matrices, use‑case adoption curves, and end‑market sensitivity to cost and regulatory changes.
- Supply‑side mapping and competitive benchmarking: production capacities, regional footprint analysis, technology differentiation, and an up‑to‑date roll of key producers and compounders.
- Raw‑material and price‑pass‑through modelling, including caprolactam and upstream petrochemical sensitivities, plus stress‑test outputs for procurement teams.
- Regulatory and standards impact assessment that quantifies the near‑term commercial implications of tariff reclassification and ISO updates.
- Commercial playbooks and go‑to‑market frameworks: win‑loss archetypes, pricing tactics, and partner ecosystem strategies for rapid market entry or share defense.
- Opportunity heatmaps and M&A scorecards: where to deploy capital for capacity rollouts, technology bolt‑ons, or tuck‑in acquisitions to capture premium margins.
- Primary research appendices: supplier interviews, plant‑level intelligence, and proprietary transaction comparables to support diligence.
Market dynamics shaping 2026 strategy
The outlook for thermoplastic polyamides this year is being rewritten by a confluence of demand-side transformation and supply-side constraints. Mobility electrification, continued emphasis on component lightweighting, growth in medical device applications, and the packaging sector’s selective move toward higher‑performance polymers are all expanding the addressable market. At the same time, raw material volatility is back on the agenda: caprolactam bid tones climbed meaningfully in late January 2026 amid continued volatility in feedstock prices, underscoring the sensitivity of PA6 value chains to crude‑oil swings and concentrated APAC supply dynamics.
Thermoplastic Polyamide Market
Regulatory changes are also material. In 2026 the U.S. Customs and Border Protection updated the Harmonized Tariff Schedule to clarify the classification of several polyamide grades, creating new tariff and documentation implications for cross‑border flows. Concurrently, ISO 21036:2025 now governs plastics piping systems for PA12 line pipe, raising compliance thresholds for producers and installers in infrastructure markets. These two changes alter cost structures and route‑to‑market decisions for manufacturers and downstream integrators alike.
Thermoplastic Polyamide Market
Competitive landscape — players, moves, and strategic implications
The market exhibits moderate concentration: leading multi‑national producers capture a meaningful share of high‑performance grades, while a broad base of regional compounders serves application‑specific needs. Strategic implications for incumbents and challengers include the need to balance scale benefits with technical differentiation and sustainability credentials.
- BASF SE (Ludwigshafen, Germany): A technology leader with a broad range of thermoplastic polyamide grades, including PA66, PA6, and copolymers for engineering applications. Recent product activity—such as a 2025 launch of a thermoplastic polyamide with high water permeability and collaborations on specialty consumer products—signals an R&D push into application‑led differentiation.
- Evonik Industries AG (Essen, Germany): Focused strength in PA12 and related resins, with established positions in automotive, sports, and oil & gas components. Evonik’s portfolio is aligned with safety‑critical and performance‑sensitive applications where premium pricing persists.
- Arkema S.A. (Colombes, France): Supplier of Nylon 12 resins and bio‑circular PA11, positioning itself at the intersection of performance and sustainability—an increasingly salient commercial axis for OEM procurement teams.
- Ascend Performance Materials LLC (Charlotte, USA): One of the largest vertically integrated PA66 producers, with capabilities in flame‑retardant chemistries for electrical and automotive markets; scale and integration remain its chief competitive levers.
- UBE Industries, Ltd. (Tokyo, Japan): Offers a suite of nylon polymers for fibers, industrial yarns, and engineering plastics; valuable for regional supply security and specialty grades.
These manufacturers’ 2024–2026 product and partnership moves indicate dual strategies: (a) defend core volume streams through integration and cost control; and (b) capture margin upside through differentiated, high‑performance and sustainability‑oriented grades. For potential entrants or investors, mid‑sized compounders that can combine nimble application development with selective upstream integration look especially attractive.
Implications for sourcing, product, and M&A strategy
For procurement leaders, the near term requires a two‑track approach: tactical hedges to manage immediate caprolactam price oscillations and strategic diversification of feedstock sourcing to mitigate regional concentration risk. Manufacturers should prioritize contractual flexibility (indexation, formula pricing) and re‑examine inventory policies against the cost of disruption.
Product teams should accelerate the commercialisation of bio‑circular and specialty PA grades that address OEM sustainability mandates while commanding premium pricing. Standards such as ISO 21036:2025 will create entry barriers for non‑compliant suppliers; early certification and targeted partnerships with downstream integrators can convert compliance into a competitive advantage.
For corporate development, the market’s growth profile and moderate concentration support both bolt‑on acquisitions (to acquire niche grades, customer access, or regional plants) and greenfield investments where long‑lead capacity can secure advantaged positions in growing end‑markets. The report’s M&A scorecard outlines target characteristics and valuation sensitivities under different scenarios.
Actionable frameworks included
- 3‑Step Investment Filter: Economic defensibility (margin under stress), strategic fit (channel & tech), and execution risk (capex & permitting timelines).
- Supplier Resilience Matrix: A diagnostic for ranking suppliers on feedstock exposure, logistic risk, and contractual flexibility.
- Go‑to‑Market Playbook: Tactical moves for launching specialty grades—pricing, channel selection, and co‑development models with OEMs.
How to use this study in 2026 planning cycles
Strategy teams should integrate the study’s scenarios into their 2026 planning cycle in four places: (1) capital allocation reviews—budget potential capacity and upgrades against forecasted price and demand scenarios; (2) procurement negotiations—use the raw‑material modelling to renegotiate terms and secure contingency capacity; (3) product roadmaps—prioritise development of PA grades that align with regulatory and sustainability signals; and (4) M&A pipeline prioritisation—rank targets using the report’s value creation templates.
Importantly, while this overview synthesizes the market’s trajectory and strategic levers, the full intelligence—including granular regional flows, application heatmaps, supplier scorecards, and downloadable modelling tools—is available in the complete PW Consulting report for teams preparing high‑stakes decisions in 2026.
Conclusion
The thermoplastic polyamide market is entering a phase where aggregate growth (CAGR ~5.85% to 2032) coexists with renewed feedstock volatility and tightening regulatory demands. That combination favors players who can marry technical differentiation and sustainability credentials with rigorous supply‑chain resilience. PW Consulting’s Thermoplastic Polyamide Market study equips leadership teams with the scenarios, financial sensitivities, and commercial playbooks required to convert the 2026 inflection into sustainable advantage.
For organisations that must translate these strategic insights into executable plans—procurement hedges, product investments, or acquisition screening—the full report contains the empirical detail and modelling tools necessary to underwrite decisions. Contact the PW Consulting research desk to access the complete dataset, forecast models, and custom advisory offerings that support rapid implementation.
For detailed analysis of this topic, please visit the official page: Thermoplastic Polyamide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com