

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Bolt Market to Reach $115.3M by 2032 at 3.48% CAGR — PW Consulting Insight

Bolt (Fastener) Market: A 2026 Strategic Primer for Executive Decision‑Making
As PW Consulting’s lead industry analyst, I present an executive introduction to our latest Bolt (Fastener) Market study — designed explicitly to equip corporate leaders with the actionable perspective they need in 2026. The global market, measured on a USD Million basis, has expanded from roughly USD 71.0 Million in 2020 to a 2025 base of about USD 91.04 Million, and our forward view projects continued expansion to the low‑hundreds by the end of the 2026–2032 forecast window (reaching roughly USD 115.3 Million by 2032). That represents a steady compound annual growth rate of approximately 3.48% across the forecast period. These headline numbers frame the opportunity set; the strategic aim of this primer is to translate them into practical choices for procurement, manufacturing, portfolio, and M&A leaders.
Bolt (Fastener) Market
Why this research matters for 2026 decisions
- Timing capital investments: Moderate but persistent growth and the uneven year‑to‑year cadence we observe in the 2026–2032 forecast imply that plant expansion and automation investments should be staged and tied to demand triggers rather than broad, front‑loaded capacity builds.
- Supply‑chain risk management: Raw material volatility and labor constraints are recurrent pressures — procurement teams must adopt hedging, multi‑sourcing, and inventory optimization strategies to avoid margin erosion.
- Commercial segmentation and pricing: End‑market cyclicality (notably automotive, construction, and industrial machinery) requires differentiated go‑to‑market and pricing playbooks rather than a one‑size‑fits‑all approach.
- M&A and partnership prioritization: Mid‑market consolidation dynamics create windows for bolt‑and‑nut players to scale through targeted acquisitions or logistics/technology partnerships — but value realization depends on playbook execution.
- ESG and standards compliance: Emerging standards activity and sustainability expectations are reshaping supplier qualification and product claims, with implications for certification costs and market access.
Key market dynamics shaping 2026 strategy
- Raw materials and price pressure: Steel remains the dominant cost driver. As of early June 2026, benchmark steel pricing stood at approximately 3,152 CNY per tonne — up around 6.9% year‑on‑year — transmitting cost pressure across the value chain and compressing margins for players unable to pass through increases.
- Standards and technical governance: Industry institutions have intensified standards stewardship. Notably, the Industrial Fasteners Institute ran its inaugural Standards Camp in mid‑2026 and continues to steer technical committee work — an operational reality for product engineers and compliance teams.
- Workforce and capacity constraints: The fastener sector remains labor‑intensive; global employment metrics indicate a workforce base in the millions with ongoing localized shortages that complicate ramp schedules and increase unit labor costs.
- Trade shows and knowledge flows: 2026 saw key convenings — Fastener Fair USA in May and the International Fastener Expo in October — which catalyzed a wave of product and logistics innovations visible across suppliers and OEM procurement teams.
- Macro oversupply/industry cycles: Broader metal industry signals — including international dialogues on steel excess capacity — inject episodic price and trade‑policy risk into fastener sourcing strategies.
Competitive landscape — who matters and why
The market structure is neither fully fragmented nor dominated by a tiny oligopoly. Top players exert meaningful influence through distribution networks, specialty product portfolios, and value‑added services, but there remains room for nimble competitors to capture niche or regional positions.
Bolt (Fastener) Market
- Würth Group (Künzelsau, Germany): A distribution and branch network powerhouse, Würth’s global footprint and extensive product range create a strong platform for integrated logistics and small‑lot servicing to construction and industrial buyers.
- LISI Group (Grandvillars, France): A specialist in high‑spec fasteners for aerospace, automotive, and medical applications — their engineering depth and certification credentials position them for higher‑margin segments.
- Bossard Group (Zug, Switzerland): Notable for fastening technology and logistics systems; Bossard’s focus on assembly efficiency and inventory services makes it a preferred partner for lean manufacturers.
- SFS Group (Heerbrugg, Switzerland): Precision fastening and assemblies for industrial customers; strengths include close engineering collaboration and custom component supply.
- Bulten AB (Gothenburg, Sweden): An automotive‑focused fastener supplier with deep OE and tier‑1 relationships, tuned to the vehicle manufacturers’ quality and scale requirements.
- Hilti Corporation (Schaan, Liechtenstein): Although broader than just fasteners, Hilti’s construction‑grade fasteners and tools combine product differentiation with strong brand recognition in building markets.
- Precision Castparts Corp (Lake Oswego, USA): Supplier of investment castings and high‑strength forged components — positioned for high‑value aerospace and power‑generation fastener requirements.
Strategically, these companies represent four archetypes: distribution and branch scale, engineered‑component specialists, logistics/assembly service innovators, and multi‑segment OEM partners. The competitive implications for 2026 are straightforward: scale matters for price and reach, engineering depth wins certified and high‑margin work, and logistics/automation capability is becoming a defensible competitive moat.
Bolt (Fastener) Market
What the PW Consulting report delivers (practical contents)
Our full report goes well beyond headline growth figures to deliver deployable intelligence across decision horizons. Key elements include:
- Methodology and transparent assumptions underpinning our historical reconstruction (2020–2025) and the 2026–2032 forecast.
- Market sizing and scenario tables (interactive dashboards) that let executives model demand on alternative macro and end‑market trajectories.
- Supply‑chain mapping and cost build‑ups — from raw‑steel price sensitivity to labor and logistics components — to support margin and sourcing stress tests.
- Regulatory and standards matrix with compliance impact scoring tailored by product families and end uses.
- Comprehensive company profiles, capability maps, and partnership/opportunity heatmaps for M&A and supplier selection.
- Commercial playbooks for procurement, pricing, aftermarket, and product standardization to improve working capital and reduce SKU complexity.
- Risk registers and a prioritized mitigation roadmap (covering raw materials, labor, trade policy, and climate‑related supply disruptions).
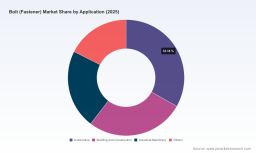
Note: this introduction intentionally emphasizes the strategic contours. Detailed tables that break down type, application, and regional splits (and the company‑level KPIs that drive M&A screens) are available in the full report and via the source page.
Actionable strategic recommendations for 2026
- Hedge steel exposure and adopt trigger‑based procurement: Combine multi‑tier supplier contracts with indexed pricing clauses and a calibrated buffer inventory to smooth volatility without tying excessive capital.
- Prioritize automation in assembly and logistics: Target investments that reduce dependence on scarce labor and shorten lead times — robotics in sorting and automated replenishment systems offer the fastest payback in many plants.
- Shift to modular standardization: Rationalize SKUs and push commonality across platforms to reduce inventory carrying costs and simplify supplier management.
- Develop service and aftermarket revenue streams: For distribution players, create bundled installation, inspection, and certified repair services to extend customer lifetime value.
- Selective M&A and strategic partnerships: Acquire engineering‑led niche manufacturers to access certified product lines, or partner with logistics tech providers to accelerate distribution efficiency.
- Invest in standards and certification capability: Be proactive in standards committees (technical participation) to shape specifications and reduce compliance surprises.
- Address workforce gaps with training and automation: Combine targeted recruitment with reskilling programs linked to automation projects to maintain throughput and quality.
How senior teams should use this report in 2026
- Board level: Use the forecast scenarios to stress‑test capital allocation and M&A authorization thresholds.
- CFO/Procurement: Incorporate price‑sensitivity models and supply‑chain risk heatmaps into budgeting and supplier scorecards.
- COO/Manufacturing: Apply the operational playbooks and benchmarking to prioritize automation, floor‑plan changes, and SKU rationalization pilots.
- Corporate development: Filter acquisition targets through our capability maps and integration templates to accelerate due diligence.
Closing: where to find the full intelligence
This primer is intentionally selective — a “trailer” that demonstrates the analytical depth and practical orientation of PW Consulting’s Bolt (Fastener) Market study while preserving the granular subsegment and company metrics that give competitors their commercial edge. For access to the full dataset, interactive dashboards, and the detailed segmentation tables (by type, application, and region), please consult the full report and our data portal. PW Consulting’s team stands ready to tailor the findings into a decision package that fits your 2026 strategic planning cycle.
For detailed analysis of this topic, please visit the official page: Bolt (Fastener) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com