

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Metallocene Polyethylene Market to Reach USD 13,520M by 2032

Metallocene Polyethylene Market — Strategic Imperatives for 2026
Executive summary
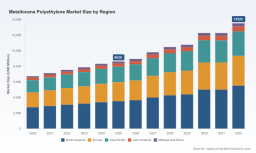
As metallocene polyethylene (mPE) transitions from a specialty polymer to a mainstream performance resin, 2026 represents a pivotal decision point for producers, converters, and investors. Our PW Consulting Metallocene Polyethylene Market study uses a 2025 base year and a 2026–2032 forecast horizon to quantify the opportunity and design actionable pathways. At a 6.8% compound annual growth rate (CAGR) through the forecast window, the market expands from approximately USD 6.74 billion in 2020 to an expected USD 13.52 billion by 2032, with the 2025 base market measured at USD 8.62 billion and the 2026 opening-year projection at roughly USD 8.95 billion (USD Million, historical series 2020–2025 included).
Metallocene Polyethylene Market
This report is intentionally structured as a strategic "preview": it surfaces the high-conviction trends, supplier strategic playbooks, and risk scenarios that will shape capital allocation and commercial tactics in 2026 — while withholding granular line-item segment tables in this public preview to ensure prospective clients consult the full intelligence package for the detailed breakouts that underpin investment models.
Metallocene Polyethylene Market
Why this matters for 2026 decision-makers
-
Demand profile and growth momentum: mPE’s differentiated performance—improved film optics, toughness at thinner gauges, and controlled molecular architecture—continues to expand use cases across packaging, construction, and mobility. The steady 6.8% CAGR signals both adoption depth and room for premiumization strategies in adjacent markets.
Metallocene Polyethylene Market -
Supply-side reconfiguration: Major incumbents are actively expanding capacity and layering product portfolios with metallocene-enabled grades. These investments will reshape regional competitive dynamics and cost curves through the mid-decade.
-
Feedstock and regulatory convergence: Large-scale ethylene additions globally are creating downward pressure on feedstock volatility and improving security of supply — a structural tailwind for mPE margins. Simultaneously, evolving sustainability and packaging regulations are accelerating demand for high-performance, lightweight solutions compatible with recycling streams.
Strategic actions we recommend
-
Prioritize product differentiation over low-cost commoditization. Invest in grade families that exploit metallocene’s unique molecular control (e.g., thinner, stronger films; tailor-made impact modifiers for pipes; breathable/laminating grades for hygiene and medical applications).
-
Optimize capacity timing and location. With new metallocene-capable units coming online, adopting a staged capacity-add approach reduces exposure to near-term price softness while preserving optionality to meet accelerating demand.
-
Securing feedstock visas. Locking competitive ethylene arrangements and integrating closer with steam cracker projects or merchant ethylene hubs will be decisive in 2026 investment returns.
-
Commercialize upstream R&D into converter enablement. Provide formulation support, co-development, and trial programs to accelerate converter migration to mPE and capture value beyond resin sales.
-
Embed sustainability as a margin lever. Align product messaging and technical documentation with recycling and packaging regulations to capture procurement wins in regulated markets.
What the full report delivers — operational and decision-grade content
-
Market sizing and forecasting with scenario runs (baseline, upside, downside) across 2026–2032, including sensitivity to ethylene feedstock price swings and capacity phasing assumptions.
-
Detailed segment economics and pricing models for grades, applications, and regions (note: granular split tables are available in the full subscription report).
-
Supply chain heatmaps with supplier-by-supplier capacity, asset vintage, and upgrade windows to support plant-level capex timing decisions.
-
Go-to-market playbooks for resin producers and converters — commercial KPIs, sample commercialization timelines, and margin capture strategies.
-
Risk matrices with mitigation options (feedstock, trade policy, technological substitution, circularity disruptions), and a quantified impact score to prioritize action.
-
M&A and partnering framework, including valuation anchors for bolt-on plants, tolling arrangements, and JV structures specific to metallocene-enabled assets.
Competitive landscape — what incumbents are doing
The mPE competitive set is concentrated, and three- to five-firm concentration metrics reflect a market with high structural barriers and scale advantages. Leading players are pursuing a mix of capacity investments, differentiated product portfolios, and regional footprint expansion to capture premium segments.
-
SABIC — Known for SUPEER™ mLLDPE and COHERE™/FORTIFY™ mPE grades, SABIC is positioning to serve flexible film packaging, agricultural films, and polymer modification markets. Its recent Southeast Asia facility expansion (announced September 2025) explicitly aims to increase regional metallocene output in alignment with evolving packaging regulations.
-
ExxonMobil — With Exceed™ metallocene resins in its portfolio, ExxonMobil has pursued both capacity and portfolio-led growth. Its Huizhou project (initiated operations mid-2025), which added a very-large LLDPE unit incorporating metallocene production, plus a late-2025 product launch targeting high-performance automotive applications, exemplify a dual-capability approach: scale plus specialized grades.
-
LyondellBasell — Leveraging Icorene™ metallocene hexene powders and mPE grades, LyondellBasell focuses on rotomolding, automotive, and industrial markets—segments where product performance can justify technical collaboration and premium pricing.
-
TotalEnergies — Lumicene™ grades position TotalEnergies in flexible film and breathable applications, aiming to capture demand driven by lightweighting and functional laminates.
-
Regional and specialist players — New product introductions out of Russia and Central Europe, and launches from state-owned or regional NOCs, continue to diversify supplier options for converters and end-users, intensifying the need for credentialed technical support and co-development.
Recent industry developments that re-shape 2026 strategy
-
Capacity and product moves: Major announcements in 2025–2026 (including large-scale LLDPE/mPE-capable units and new specialty grade rollouts) are compressing the window to secure converter trials and long-term offtake agreements.
-
Feedstock dynamics: Analysts report substantial global ethylene capacity additions through 2025. These additions, including significant build-out in China, are contributing to improved ethylene supply security and downward pressure on regional feedstock costs — a structural input that materially affects integrated and merchant margin profiles in 2026.
-
Regulatory alignment: Regional packaging and environmental standards (notably in Asia) are encouraging investments in single-site catalyst technologies and enabling cleaner production narratives. Facility expansions that explicitly cite regulatory alignment (e.g., reduced environmental impact for flexible films) are gaining preferential attention from downstream customers and regulators.
Risk vectors and scenario planning
-
Feedstock price volatility — Even with sizeable ethylene additions, downstream margins remain exposed to short-term cracker outages and energy price shifts. Hedging strategies and feedstock diversification remain primary mitigation levers.
-
Overcapacity in the near term — Capacity additions concentrated in specific regions risk local price compression. Staged capacity ramp-up and commercial differentiation can reduce exposure.
-
Circularity and regulatory disruption — Accelerated mandates for recyclability, PCR content, or single-stream separation could both favor and penalize mPE depending on grade recyclability and certification.
-
Technological substitution — Alternative polyolefin technologies or catalyst breakthroughs that further lower mPE cost structures could emerge; continual R&D monitoring is essential.
How to use this intelligence in 90/180/360-day cycles
-
90 days: Conduct a quick-scan commercial readiness audit — grade portfolio fit vs. priority customers, sample and trial readiness, and short-term hedging posture for ethylene exposure.
-
180 days: Finalize capacity timing decisions and offtake/tolling structures; initiate converter co-development partnerships and prioritize market-entry geographies based on logistical cost-to-serve.
-
360 days: Execute capacity investments or JV formations, finalize M&A targets using our valuation frameworks, and embed circularity credentials to capture regulated procurement streams.
Closing — why PW Consulting’s study matters to your 2026 plan
Our analysis blends rigorous quantitative forecasting (2020–2025 historical data, a 2025 base year, and 2026–2032 scenarios), supplier-by-supplier strategic mapping, and executable commercial playbooks. The report translates a 6.8% CAGR and multi-billion-dollar market trajectory into portfolio-level choices: which grades to push, where to site new capacity, and how to structure offtake and pricing agreements to preserve margin in the face of evolving feedstock and regulatory realities.
To uphold the “preview” principle and preserve the commercial value of the downstream granularity that underpins investment-grade decisions, we have withheld the detailed regional and application split tables from this public overview. For clients requiring the full dataset — including the segmented demand curves, price and margin models by grade and geography, and our tailored M&A playbook — please consult the full report available via PW Consulting’s Metallocene Polyethylene Market page.
PW Consulting stands ready to translate these insights into a bespoke implementation roadmap for your organization in 2026 — from tactical commercial pilots to capex and M&A execution. Contact our team to schedule a strategy session and access the confidential appendices and modeling workbooks.
For detailed analysis of this topic, please visit the official page: Metallocene Polyethylene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com