

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: High Voltage Cables Market to Grow to USD 63.81M by 2032 (6.08% CAGR)

High Voltage Cables Market — Strategic Preview for 2026 Decision-Makers
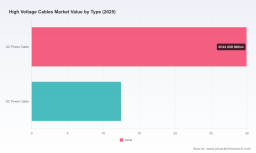
As energy systems accelerate toward higher-capacity transmission, deeper subsea links and widespread renewable integration, decisions made in 2026 will set the competitive trajectory for the next decade. PW Consulting’s High Voltage Cables Market study (base year 2025; forecast period 2026–2032) synthesizes historical performance, a rigorous forecast framework and project-level intelligence to translate market signals into executable strategies. The market has expanded materially from the early 2020s — rising from roughly USD 25–26 million in 2020 to an estimated USD 42.4 million in 2025 — and is projected to continue growing through 2032, reaching about USD 63.8 million under our central case. The 2026–2032 compound annual growth rate (CAGR) underpins that trajectory at approximately 6.08%.
High Voltage Cables Market
Why this study matters in 2026
-
Timing: 2026 is a hinge year for capex cycles and project awards across offshore wind, long‑distance DC transmission and national grid reinforcements. Several high‑value projects that will consume high‑voltage (HV) cable capacity are moving from feasibility to firm procurement, making supplier selection, manufacturing commitments and installation scheduling urgent.
High Voltage Cables Market -
Input‑cost volatility: raw materials and installation inputs remain a critical margin driver. For example, copper wire pricing and availability materially affect tender pricing and sourcing strategies; industry indices showed copper electric wire costs near USD 416 per thousand linear feet in April 2026, creating immediate implications for bids, hedging and contract structure.
High Voltage Cables Market -
Regulatory and system‑operator momentum: major system owners continue to propose and sanction sizeable HVDC programmes — exemplified by a multi‑billion capital plan submitted for an HVDC upgrade between major islands — and cross‑TSO coordination initiatives are forming new infrastructure corridors, especially in the North Sea and other offshore zones. These are structural demand drivers, not one‑off phenomena.
-
Technology and execution complexity: recent project milestones, including world‑record subsea installation depths and multiple high‑voltage contract awards, demonstrate rapidly evolving technical capability among suppliers and raise the bar for delivery risk management and installation logistics.
What this report delivers (practical, operational intelligence)
-
Market sizing and granular forecasting: transparent methodology and scenario outputs that translate macro drivers into a validated, project‑level demand runway for 2026–2032 (base year 2025).
-
Supply‑side capability maps: manufacturing capacity, installation fleet availability, lead times, and an assessment of technological readiness across AC and DC product families.
-
Procurement and cost modelling toolkit: indexed cost build‑ups that incorporate raw material trends, manufacturing yield assumptions, transport and installation risk premia — designed to be drop‑tested against live tenders.
-
Project pipeline and tender tracker: a curated dataset of near‑term to mid‑term projects, procurement windows and counterparty profiles to prioritize commercial effort and resource allocation.
-
Commercial playbooks: tailored go‑to‑market strategies for suppliers, utilities and investors — from pricing templates and risk allocation clauses to JV frameworks for offshore installation.
-
Risk matrices and scenario stress tests: quantified implications of material price shocks, permit delays, and installation failures on cash flows and delivery schedules.
Competitive landscape — who matters and what they signal
The market exhibits moderate concentration at the top: the top three groups account for a substantial share of global volume and capability, while the top five capture just over half the market by revenue and capability metrics. This concentration creates a dual dynamic — a small set of suppliers able to execute very large, complex projects, and a long tail of regional manufacturers and integrators competing on lead time, local content and aftermarket services.
-
Nexans (Paris, France) — Demonstrated capability in deep subsea HVDC with recent installation milestones at world‑record depths. Their execution competence for complex subsea links makes them an obvious counterparty for projects requiring novel installation techniques and risk‑sharing structures.
-
Prysmian Group (Milan, Italy) — Continued focus on high‑voltage HVAC solutions for floating offshore wind and integrated offshore platforms. Prysmian’s portfolio suggests strategic emphasis on adaptable HVAC systems that reduce offshore interface complexity.
-
NKT A/S (Copenhagen, Denmark) — Large, firm contracts for HVDC power cable systems demonstrate a leaning toward utility‑scale grid reinforcement projects. Their recent award for a major grid reinforcement underscores appetite for long‑duration contracts with system operators.
-
Sumitomo Electric Industries Ltd (Tokyo, Japan) — Strong in very high‑voltage HVDC lines and major subsea link supply. Recent contract awards for 525 kV HVDC projects show the company’s technical positioning at the highest voltage classes.
-
LS Cable & System Ltd (Seoul, South Korea) — Growing presence in high‑voltage HVDC applications and strategic programmes in Asia; capabilities suggest a focus on large interconnector and national transmission projects.
-
Regional and specialist players — Several firms from established manufacturing hubs (including Italy, India and elsewhere) provide competitive depth up to specific voltage classes and are often preferred for local content, shorter lead times and aftermarket services.
Recent developments provide telling market signals: Nexans’ completion of a record‑depth subsea 500 kV HVDC installation (Jan 2026) confirms both technology maturity and the premium buyers will pay for proven installation capability; Sumitomo’s late‑2025 contract for a 525 kV HVDC Sea Link underscores high‑voltage demand in national interconnection projects; and NKT’s firm contract wins (Mar 2026) highlight sizeable programme awards becoming available to bidders in 2026.
Market dynamics and near‑term headwinds
-
Input price inflation and hedging complexity — Copper and polymer feedstock price swings compress margins and complicate fixed‑price contracting. Buyers and suppliers must consider indexation, pass‑through clauses, or hedged procurement strategies.
-
Manufacturing bottlenecks and lead times — High‑voltage cable production and jointing capacity are capital‑intensive; firms that secure long‑lead manufacturing slots will gain bidding advantage for multi‑year programmes.
-
Regulatory programme timing — Decisions by TSOs and national governments (including multi‑billion capex proposals and coordinated offshore initiatives) will create concentrated procurement windows that favor vertically integrated suppliers or consortiums.
-
Installation risk and technical escalation — Deepwater and ultra‑high voltage projects carry installation and testing complexity; record installations signal capability but also raise the stakes on insurance, indemnities and performance bonds.
Practical recommendations — what executives should do in 2026
-
Procurement readjustments — Move from single‑round, fixed‑price tenders to staged contracting with material price indexation and firm slots for critical long‑lead items. Shortlist suppliers with demonstrable recent installation performance.
-
Supply‑chain hedging — Lock in raw‑material forward contracts where justified; use layered buying to smooth exposure and include contingency margins in financial models.
-
Strategic partnerships — Pursue consortiums for high‑risk offshore or HVDC projects to combine manufacturing scale, installation vessels and local permitting expertise.
-
Capability building — For suppliers: invest selectively in high‑voltage HVDC manufacturing lines and jointing technology. For buyers: expand in‑house project‑management teams with subsea and HVDC execution experience.
-
M&A and market entry — Target acquisitions that provide either installation fleet access or specialized jointing/termination capabilities rather than pure volume players. Assess targets against capacity, certificates and recent project track record.
-
Scenario planning — Run stress tests for +20% raw material shock, 6–12 month permit delays and a concentrated procurement window to quantify working capital and schedule impacts before committing to awards.
How boards, CFOs and operations teams should use this research
-
Boards : Use the report’s scenario suite to validate strategic capital allocation, JV structures and M&A prioritization before approving multi‑year commitments.
-
CFOs : Leverage the procurement and cost‑modeling toolkit to refine bid/no‑bid thresholds, approve hedging instruments, and structure payment milestones tied to installation milestones and CPI‑linked indices.
-
Operations and procurement : Adopt the supplier capability matrices and project pipeline tracker to optimize lead‑time sequencing, prequalify partners and align internal resourcing to the procurement calendar.
Conclusion — a strategic preview, not the full map: This article has outlined the strategic contours derived from PW Consulting’s High Voltage Cables Market study and highlighted the core commercial and technical levers that will matter in 2026. We have deliberately presented top‑line market growth indicators and synthesized directional competitive and technical signals to support boardroom decision‑making. For the full, actionable intelligence — including project‑level demand schedules, downloadable financial models, voltage‑class build‑outs, regional pipelines, and supplier scoring matrices — access the comprehensive report and dataset. That is where programmatic procurement decisions, M&A screening and capital planning for the next decade are executable with confidence.
For detailed analysis of this topic, please visit the official page: High Voltage Cables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com