

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Schistosomiasis Drug Market Set for 6.4% CAGR to 2032

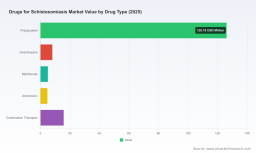
Drugs for Schistosomiasis Market: Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a forward-looking briefing that situates the Drugs for Schistosomiasis market within the strategic decision cycle for 2026. This preview highlights the macro trajectory, risk vectors, competitive dynamics, and the actionable themes executives must address to convert epidemiological need into resilient commercial and public-health outcomes. It intentionally surfaces high-value signals and practical implications while reserving granular segmentation and proprietary model outputs for our full market study.
Drugs for Schistosomiasis Market
Why this market matters in 2026
Schistosomiasis remains a high-priority neglected tropical disease with concentrated programmatic spending, frequent mass drug administration (MDA) campaigns, and evolving pharmaceutical supply needs. The overall market shows steady, predictable expansion: from an estimated USD 118.5 Million in 2020 to USD 160.0 Million in our base year (2025), with a compounded annual growth rate of approximately 6.4% through the forecast window to 2032. Under our central forecast the market approaches a mid-to-high two-hundred million USD valuation by 2032, reflecting continued demand for praziquantel-based treatments, pediatric formulations, and emerging combination therapies.
Drugs for Schistosomiasis Market
For corporate leaders—pharma CEOs, commercial heads, supply-chain chiefs, and public-sector procurement officers—this trajectory matters because it combines programmatic predictability with episodic volatility. That combination creates differentiated opportunity windows for manufacturers, contract manufacturers, logistics providers, and private–public partnership investors who can align production, pricing and access strategies with MDA cycles and WHO-driven procurement channels.
Drugs for Schistosomiasis Market
Core dynamics shaping 2026 strategic choices
-
Demand stability vs. episodic shocks: Endemic-country programs and donor-funded MDA create a baseline, predictable demand profile. However, geopolitical tensions, export restrictions, and capacity constraints in specialized manufacturing periodically compress supply—generating short-term price and access shocks that can disrupt national elimination campaigns.
-
Product evolution and access policy: The arrival of pediatric dispersible formulations and WHO prequalification of newer treatment variants has shifted procurement preferences in favor of child-friendly therapies, changing tender dynamics and enabling preferential pricing frameworks in many endemic countries.
-
Competitive structure and cost pressure: Off-patent status for core molecules has fostered a robust generic supply base from cost-optimized manufacturers, increasing price competition for large tenders while concentrating premium value on differentiated formulations and supply reliability.
-
Distribution and last-mile requirements: MDA programs rely on a mix of institutional channels—hospital and community health platforms, government procurement routes, and NGO distribution networks—with growing attention to cold chain simplification, dosing accuracy for children, and on-the-ground logistics capacity.
What this means for strategic planning in 2026
-
Manufacturing and capacity decisions: Firms must balance capitalizing on baseline growth with resilience to episodic supply disruptions. Options include selective capacity expansion, dual-sourcing of active pharmaceutical ingredients (APIs), and strategic contract manufacturing partnerships that prioritize regulatory readiness (e.g., WHO prequalification) for high-volume tenders.
-
Portfolio and product strategy: Plain dose competition will intensify. Margin protection will come from pediatric formulations, combination therapies, and value-added services (e.g., packaging for MDA distribution, integrated training materials). Early investment in child-specific formulations and scalable blister/pediatric packaging is likely to accelerate tender share in the 2026–2028 window.
-
Procurement and pricing playbooks: Buyers—governments and donors—are increasingly awarding contracts based on a mix of price, supply assurance, and WHO prequalification status. Suppliers should construct tiered pricing structures that reflect long-term procurement commitments and include volume and delivery guarantees to win multiyear tenders while preserving commercial viability.
-
Partnership and access models: Success will depend on hybrid models combining commercial distribution with NGO and multilateral partnerships. Strategic alliances with program implementers and funders—particularly those focused on pediatric access—can accelerate adoption while sharing implementation risk.
-
M&A and licensing considerations: Given the market’s moderate scale and the concentration of capability in a subset of suppliers, targeted acquisitions or licensing arrangements—especially for pediatric formulations, WHO-prequalified lines, or regional manufacturing footholds—are an efficient route to scale and tender eligibility.
Competitive landscape: capabilities that matter in 2026
The market is anchored by a small group of established manufacturers and a broader field of generics that serve government procurements. Strategic differentiation is not purely about price; it is about supply reliability, regulatory positioning, and formulation innovation.
-
Large innovator and established suppliers: Global players with WHO-prequalified products and partnerships with implementation bodies are positioned to capture premium opportunities tied to pediatric and program-integrated deliveries. Recent distribution and partnership moves that target preschool-aged children reflect a strategic shift toward integrated public-health engagement models.
-
Generic manufacturers in cost-competitive markets: Established producers in India and East Asia have strong cost positions and are primary contenders for large-volume tenders. Patent expiries have enabled wider participation, making procurement dynamics highly price-sensitive for commoditized formulations.
-
Regional and emerging suppliers: Smaller regional players can win on agility, local regulatory knowledge, and faster lead times—but they must demonstrate consistent quality standards and tend to be disadvantaged in large multilateral tenders without prequalification credentials.
Notable recent developments underscore the market’s practical dynamics: targeted delivery of pediatric formulations in field studies, strategic partnerships between suppliers and elimination-focused NGOs, and episodic production discontinuations that require rapid procurement adjustments. These events crystallize the competitive premium on program-aligned supply models and regulatory readiness.
Report contents — what PW Consulting delivers
Our full Drugs for Schistosomiasis Market report goes beyond top-line forecasting to deliver operationally actionable intelligence for 2026 planning cycles. Key inclusions:
- Robust market-sizing and growth scenarios (historical baseline 2020–2025; detailed forecasts through 2032) with sensitivity analysis to key variables such as API cost, tender volumes, and geopolitical disruption intensity.
- Segmentation analysis across product type, distribution channels and end-user cohorts—presented with commercial-grade assumptions and an interactive dashboard that supports “what-if” tender and pricing modeling.
- Supply-chain and manufacturing capacity maps, including concentration risk heatmaps and recommended dual-sourcing strategies to mitigate single-point failures.
- An operational playbook for winning institutional procurement (tender-response checklists, pricing templates, compliance milestones including WHO prequalification pathways).
- Competitive profiles and strategic scorecards for the key incumbents and high-potential entrants, including assessment of R&D pipelines for pediatric and combination therapies, regulatory posture, and historical tender performance.
- Risk register and mitigation matrix covering regulatory changes, logistics interruptions, reputational exposures, and demand variability tied to program funding cycles.
- Investor and M&A guidance: valuation frameworks, target screening criteria, and integration checklists tailored to the sector’s scale and concentration dynamics.
How to use this intelligence in 90–180 day planning
-
90-day tactical moves: Secure contingent API contracts, validate WHO prequalification status for product lines, and structure price-volume commitments for near-term tenders. Initiate conversations with program partners to align clinical acceptability and distribution readiness for pediatric formulations.
-
180-day strategic moves: Commit to capacity investments or contract manufacturing agreements, deploy a segmented pricing strategy for institutional vs. private-channel customers, and finalize at least one collaboration or distribution partnership in an endemic region to establish a procurement track record.
Bottom line for 2026 decision-makers
The schistosomiasis drugs market is not a high-margin blockbuster sector, but it is strategically significant for companies that can combine product reliability, regulatory readiness, and programmatic alignment. The predictable baseline growth—anchored by steady program funding and evolving pediatric needs—creates a durable commercial case for investments that enhance supply resilience and formulation differentiation. Conversely, failure to secure quality-certified capacity or to partner effectively with procurement stakeholders will relegate suppliers to cyclical, price-driven tendering with narrow margins.
PW Consulting’s full market study contains the granular segmentation, tender-level benchmarking, and proprietary scenario outputs required to operationalize these recommendations. For commercial teams, supply-chain leaders, and strategic planners who must present a defensible 2026 plan to boards or donors, the detailed appendices and playbooks in our report are the tools to close the gap between strategy and execution.
Next steps
To access the full dataset, tender-level intelligence, and the executable playbooks referenced here, consult the PW Consulting report page for the Drugs for Schistosomiasis Market. Our team is prepared to run a condensed, client-specific workshop to translate the findings into a 12–24 month action plan tailored to your organization’s role in the value chain.
For detailed analysis of this topic, please visit the official page: Drugs for Schistosomiasis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com