

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Pool Chemical Market: USD 1,565.89M in 2025, projected 4.51% CAGR (2026–2032) — PW Consulting

Pool Chemical Market 2026: Strategic Trailer for Executive Decision-Making
As PW Consulting’s lead industry analyst, I present a concise strategic briefing that translates our full Pool Chemical Market study into immediate, board‑level implications for 2026. This piece previews the report’s most consequential findings—market scale, growth trajectory, competitive dynamics, and actionable playbooks—while intentionally withholding the granular segmented tables and model outputs reserved for the full report. Think of this as the executive trailer: enough depth to inform decisions and provoke questions, not the complete dataset.
Pool Chemical Market
Macro picture: scale and trajectory
The global pool chemical market has moved from recovery into a steady expansion phase. Using 2025 as our base year, the market is projected to grow at a compound annual growth rate (CAGR) of approximately 4.51% through the 2026–2032 forecast window. After a post‑pandemic rebound, the market shows resilient structural demand drivers—ongoing residential pool installations, retrofit cycles in aging commercial facilities, and accelerating adoption of digital dosing and automation systems—supporting mid‑single‑digit growth into the next decade.
Pool Chemical Market
For executives planning 2026 capital allocation, the message is clear: the market is large enough to justify capacity and product investment, yet growth is moderate enough that share gains, margin improvement and cost management will be decisive in determining winners. Our full study provides the time‑series market size trajectory, scenario overlays and sensitivity to key inputs; in this summary we frame the strategic implications of those dynamics.
Pool Chemical Market
Why this matters for 2026 decisions
- Investment timing: Moderate, predictable growth favors targeted capital deployment—capacity optimization, automation, and selective M&A—over indiscriminate greenfield expansion.
- Margin leverage: With wholesaling and private‑label activity increasing, firms that control formulation, distribution and pricing can convert modest volume gains into outsized margin improvements.
- Supply‑chain resilience: Recent price volatility and logistical frictions have shown that supply stability and feedstock sourcing strategies are value drivers as important as top‑line growth.
- Regulatory compliance and ESG: Tighter environmental controls and product stewardship obligations are raising the cost of doing business—and creating opportunities for eco‑differentiated products.
Competitive landscape: consolidation, private labels, and technology entrants
The market exhibits a medium concentration profile: the top three firms account for just under half of market share, and the top five collectively hold a clear but not dominant majority. That structure favors both scale players seeking incremental consolidation and nimble specialists who can exploit product differentiation or channel niche plays.
Key strategic moves we tracked in 2025–2026 illustrate two concurrent themes: incumbents doubling down on private‑label and proprietary formulations to lift margins, and new/adjacent entrants pushing product innovation and digital services. Illustrative developments include:
- Leading distributors expanding private‑label offerings and reporting chemical category margin improvement—evidence that channel control matters.
- Technology providers launching integrated dosing and monitoring systems that blur the line between chemical supplier and service provider, enabling recurring revenue models.
- Established equipment and water‑treatment companies augmenting portfolios with eco‑friendly chemistries through strategic acquisitions.
Profiles of core competitors are included in the full report. Highlights you should know now: distributors with deep retail footprints and proprietary brands bring a distribution premium; manufacturers of core chlorine products retain pricing influence tied to chlor‑alkali cost cycles; and specialty chemical firms enjoy pricing power when paired with validated performance or regulatory advantage.
Recent events shaping 2026 strategy
- Commercial signals: Q1 and mid‑year earnings commentary from major distributors has pointed to higher chemical volumes and structural margin gains from private‑label lines—an important confirmation of the channel shift we modeled.
- Product innovation: New professional water‑management systems combining automated dosing, real‑time monitoring and integrated service contracts are changing buying criteria for commercial operators and higher‑end residential customers.
- M&A and portfolio moves: Acquisitions of eco‑chemical startups by equipment and service incumbents demonstrate an acceleration of sustainability‑driven product roll‑outs and vertical integration.
- Supply pressures: Weather, energy costs and port congestion have intermittently tightened chlorine and shipping markets, producing short‑term price movements that underscore the need for procurement playbooks.
- Regulatory overlay: Tariff actions and tightened environmental discharge guidance increase compliance costs—particularly for players reliant on complex international supply chains.
Operational risks and input cost outlook
Raw material and logistics risk are the primary near‑term operational vulnerabilities. Chlor‑alkali input cost behavior and transport frictions have been the most visible drivers of margin pressure; while feedstock indices have stabilized in recent months, episodic price upticks remain possible under energy or production disruptions. Tariff measures and tighter discharge regulations in major markets add a structural cost burden for firms with long, import‑dependent supply chains.
In practice, this means procurement teams must adopt layered risk management—hedging where feasible, establishing multi‑sourcing strategies, and building inventory playbooks for peak seasons—while commercial teams protect margin through smarter contract structures and value‑added services.
What’s inside the full PW Consulting report (practical tools for 2026)
The full study is designed to be operationally actionable for strategy, commercial, procurement and R&D teams. Key deliverables include:
- Market sizing and trend models with base year 2025 and a 2026–2032 forecast, plus scenario sensitivity to feedstock pricing and regulatory tightening.
- Competitive intelligence dossiers and capability maps for the leading players across distribution, manufacturing and specialty chemistry.
- Price‑to‑win matrices and commercial playbooks tailored to residential and commercial channels, including private‑label economics and margin modeling.
- Supply‑chain risk heatmaps and procurement strategies (multi‑source decision trees, forward purchasing thresholds and inventory optimization heuristics).
- Innovation trackers and go‑to‑market roadmaps for eco‑friendly chemistries, dosing automation, and service‑based monetization.
- Regulatory compliance checklists and cost impact assessments for major jurisdictions, plus an emissions/discharge compliance calculator for corporate reporting teams.
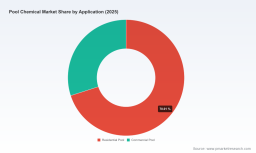
We intentionally omit the granular region‑by‑type‑by‑application tables here; those segmentation matrices and the underlying datasets are included exclusively in the paid report to preserve the competitive value of the insights.
Strategic recommendations for 2026 (prioritized)
- Protect and grow margins: Accelerate private‑label formulations and contract offerings that lock in long‑term, higher‑margin customer relationships—especially in retail and professional service channels.
- Invest selectively in automation: Prioritize partnerships or product roll‑outs that bundle chemicals with monitoring/dosing to convert commodity buyers into subscription service clients.
- Hedge and diversify supply: Implement a tiered procurement strategy: secured core supply agreements for key chlorinated feedstocks, a secondary pool of regional suppliers, and targeted inventory buffers ahead of peak seasons.
- Pursue bolt‑on sustainability targets: Use M&A or licensing to acquire validated eco‑friendly chemistries—these generate premium pricing and reduce regulatory downside.
- Optimize channel mix: Rebalance commercial vs residential focus based on gross margin contribution and service potential—details and quantitative thresholds are in the full model.
How PW Consulting’s outputs accelerate implementation
Boards and executive teams will find immediate value from three deliverables in the full report: (1) a market model calibrated for capital and M&A planning, (2) a competitor moves tracker to inform defensive/offensive actions, and (3) procurement and product commercialization playbooks that translate scenario results into 90‑, 180‑ and 360‑day actions. These are designed to be directly plugged into annual planning cycles and M&A diligence processes.
Next steps
If your 2026 plans involve capacity investment, private‑label expansion, vertical integration or an eco‑innovation pathway, the full PW Consulting Pool Chemical Market report contains the granular segmentation, price elasticity matrices and competitor benchmarking you will need to execute. Request the full report to access the detailed regional/type/application breakdowns, datasets, and the tactical templates referenced above.
For a bespoke briefing tailored to your strategy team—covering scenario stress‑testing against your supply chain, or a defensible M&A target short‑list—contact our Pool Chemical Market practice at PW Consulting. The window to translate the current market momentum into sustainable advantage is open; the right combination of procurement discipline, product differentiation and channel orchestration will determine who captures outsized returns in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Pool Chemical Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com