

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Colocation Market Set to Expand at 14.4% CAGR through 2032

Colocation Market 2026: A Strategic Preview for Enterprise Decision‑Makers
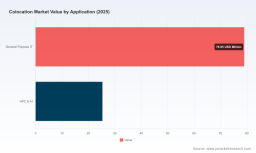
As organizations accelerate digital transformation and scale AI workloads, colocation has re-emerged as a strategic infrastructure choice. PW Consulting’s latest Colocation Market study (base year 2025, forecast 2026–2032) synthesizes five years of historical observation with forward-looking scenarios to equip executives with the evidence they need to make high‑stakes decisions in 2026. The market we modelled grew from roughly USD 47.3 million in 2020 to USD 104.3 million in 2025 and, under a central scenario, is projected to reach about USD 265.5 million by 2032 — representing a compound annual growth rate of 14.4%. Those headline numbers frame a market that is substantial, accelerating, and strategically differentiated by workload, sovereignty needs, and interconnection intensity.
Colocation Market
Why this study matters in 2026
-
Timing matters: Capital cycles, capacity ramp lead times and long procurement windows mean that decisions made in 2026 will determine latency, resilience and TCO outcomes for the next decade.
Colocation Market -
Workload differentiation: The contours of “colocation” are widening — from classic enterprise rack deployments to hyperscale campuses optimized for dense AI appliances. A one‑size procurement approach now carries execution risk.
Colocation Market -
Regulatory and energy dynamics: New reporting and interconnection rules, changes to grid policy and data‑sovereignty mandates have turned site selection and contract terms into regulatory as well as technical decisions.
What the report delivers — operationally useful outputs
This study is built as a practical playbook for strategists, real‑estate and IT procurement teams, and private capital managers. The full report goes well beyond high‑level forecasts and includes the following actionable modules:
-
Transparent market sizing and scenario engine — base case, upside (accelerated AI adoption), and downside (grid constraints) scenarios with Monte Carlo sensitivity around key variables.
-
Vendor and site scorecards — standardized, exportable templates that rank providers across interconnection density, AI readiness, sustainability credentials, contractual flexibility and time‑to‑service metrics.
-
Site selection toolkit — a weighted scoring model for prioritizing markets that balances latency, power availability, regulatory risk, and cost inputs. Includes a decision tree for colocating edge versus core workloads.
-
TCO and contract negotiation playbook — integrated capex/opex templates, power procurement strategies and a negotiation checklist that highlights clauses typically overlooked in colocation agreements.
-
Workload mapping and migration patterns — recommended packaging of workload types (including high‑density AI clusters) into deployment archetypes with migration timelines and dependency maps.
-
M&A and investment playbook — criteria for bolt‑on acquisitions, greenfield vs. buy decisions, and a private equity checklist that aligns IRR sensitivity with construction and permitting risks.
-
Regulatory overlay and sustainability metrics — compliance matrices for new reporting regimes and a set of KPIs to include in RFPs to track PUE, water usage effectiveness and embodied carbon.
-
Interactive dataset and dashboards — an online portal with downloadable model inputs, provider footprints and market access matrices to drive workshop sessions and vendor negotiations.
Note: this article intentionally highlights the report’s structure and tools without reproducing the full segmentation tables and granular regional shares. Those datasets, our provider benchmarking scores and model inputs are available in the full report and interactive portal.
Market dynamics — what’s driving growth and risk in 2026
-
AI and high‑density compute: The principal demand vector is densifying compute deployments. Providers that have invested in high‑power distribution, flexible floor space and chilled water systems are capturing disproportionate demand.
-
Interconnection and latency: Network effects are real — sites with deep interconnection ecosystems accelerate cloud on‑ramp and partner integrations for enterprises with hybrid architectures.
-
Data sovereignty and regulated workloads: Government mandates in multiple jurisdictions are forcing a segment of regulated workloads to remain onshore. This structural requirement reshapes procurement priorities and increases local colocation demand.
-
Policy and reporting: Regulatory changes requiring operational transparency (e.g., mandatory reporting of energy and water performance) are creating new compliance costs and differentiators for sustainable operators.
-
Supply constraints: Construction unit costs and skilled labor availability are limiting near‑term capacity expansion in key markets. These supply dynamics underpin pricing resilience despite efficiency gains.
-
Market concentration: The competitive landscape shows meaningful concentration at the top — the combined share of the largest three and five providers indicate an environment of regional incumbency plus room for specialist entrants.
Competitive landscape — who matters and why
The report profiles global and regional leaders and assesses how each player’s footprint, product strategy and recent investments position them against enterprise needs:
-
Equinix — The world’s largest carrier‑neutral colocation provider, notable for interconnection density and accelerating AI‑ready capacity. Recent expansion into new national markets highlights a strategy that blends sovereignty controls with hybrid multicloud tooling.
-
Digital Realty — A capacity‑centric operator with a large wholesale and enterprise colocation estate. Recent market entries in Europe underscore a continued emphasis on global scale and sustainability reporting.
-
Iron Mountain — A trusted provider for regulated industries, now scaling hyperscale campuses suited for AI workloads while preserving their compliance heritage.
-
QTS — Positioning around carrier neutrality and large‑scale capacity with a focus on North America and Europe, and messaging that leans into AI demand capture.
-
CoreSite — Strong in high‑density facilities and interconnection services, with thought leadership that frames colocation as the connective layer for hybrid IT.
-
Vantage Data Centers — Scalable wholesale and campus strategies that are tailored for hyperscale and enterprise customers needing modular expansion paths.
-
CyrusOne, Switch, NTT and ST Telemedia — Each brings differentiated strengths: enterprise reliability, cloud/edge integration, Asia‑Pacific reach, and regional interconnection ecosystems respectively.
Recent corporate moves included several targeted expansions and sustainability disclosures; these actions demonstrate that operators are contesting both capacity and policy leadership. For buyers, provider selection increasingly requires a dual assessment of physical capability and policy alignment.
Strategic implications and recommended responses for enterprise leaders
Organizations can translate the study’s insights into practical steps in 2026. The report recommends a prioritized set of actions:
-
Classify workloads by sovereignty, latency sensitivity and compute density. Treat AI/HPC clusters and regulated workloads as separate procurement tracks with distinct acceptance tests.
-
Use scenario TCO models to drive negotiation thresholds. Factor in power pass‑through, demand charges and escalation clauses tied to regulatory reporting requirements.
-
Embed sustainability and operational transparency into RFPs. Insist on measurable KPIs, audit rights and timelines for decarbonization commitments.
-
Lock in interconnection and cloud on‑ramps where latency or partner ecosystems matter; conversely, prioritize wholesale campus economics where raw capacity and scale are the driver.
-
Plan capex and release schedules against construction lead times; where speed matters, evaluate pre‑built or brownfield options to de‑risk go‑to‑market timelines.
-
Establish a governance cadence to monitor policy changes and grid interconnection developments that can materially affect site viability.
How to extract maximum value from the full PW Consulting study
This article is a strategic preview — a clear view of the market’s arc without publishing the report’s granular segmentation tables and vendor scorecards. The full study offers the complete dataset, downloadable models, and interactive dashboards that allow you to:
-
Run bespoke market share and location scenarios using your internal workload assumptions;
-
Download provider benchmark matrices and the negotiation playbook to accelerate RFP cycles;
-
Access the regulatory compliance matrix and sustainability KPI templates for inclusion in contracts and board reporting.
In 2026, colocation is not simply about space and power — it is a lever for enterprise agility, regulatory compliance and cloud‑adjacent performance. PW Consulting’s Colocation Market study equips leaders to convert market momentum into high‑confidence decisions. For the complete dataset, provider scoring sheets and interactive modeling tools, access the full report and portal to run tailored scenarios against your operating constraints and strategic priorities.
For detailed analysis of this topic, please visit the official page: Colocation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com