

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Car Bumpers Market — USD 16,500M in 2025, 4.2% CAGR through 2032

Car Bumpers Market 2026: Strategic Preview for Decision-Makers
Executive Snapshot
As the automotive industry shifts toward lightweighting, circularity, and differentiated aftermarket demand, the global car bumpers market is navigating steady expansion and structural change. PW Consulting’s latest analysis—anchored on a 2025 base year and a 2026–2032 forecast horizon—finds the market moving from roughly USD 14.1 billion in 2020 to about USD 16.5 billion in 2025, with a projected continuation to just over USD 22.0 billion by 2032 at a compounded annual growth rate (CAGR) of 4.2% for the 2026–2032 period (USD, Million). This trajectory masks important inflections in material choices, aftermarket dynamics, and regulatory pressure that will determine winners and losers in 2026 and beyond.
Car Bumpers Market
Why this matters for 2026 strategic planning
- Timing of capital deployment: A moderate, predictable CAGR creates a window for measured capital investment in tooling, recycling infrastructure, and material switching. Companies that deploy selectively in 2026—targeting modular manufacturing and adaptable tooling—will avoid stranded assets if demand composition shifts.
- Supply-chain repositioning: With polypropylene (PP) entrenched as the dominant bumper polymer, shifts in polyolefin feedstock pricing and recycling policies directly influence cost and design choices. Buyers and suppliers must lock in flex contracts or vertical partnerships to stabilize input cost exposure.
- Aftermarket and retrofit economics: The aftermarket continues to be a margin pool with different economics from OEM supply; differentiating channel strategies between painted CAPA-style parts, heavy-duty steel bumpers, and premium offroad offerings will be crucial.
- ESG and regulatory timing: Emerging regulatory signals—especially in Europe and select North American jurisdictions—intensify the need for circular design and take-back capabilities. 2026 is the inflection year for executing pilot recycling programs at scale.
Market Trajectory: Key Numbers to Guide Strategy
Use the following macro touchpoints as strategic guardrails when evaluating 2026 initiatives: the market expanded materially from the early-2020s through 2025, and our forecast shows a continuation of measured growth into 2032 under a 4.2% CAGR assumption for the 2026–2032 period. These aggregated figures are intentionally highlighted to support top-level budgeting, headcount planning, and portfolio prioritization. For granular regional, application, and type splits—critical when sizing investments by geography or product line—the full dataset and working models in the complete report are essential.
Car Bumpers Market
Segment & Supply-Chain Dynamics (What’s changing)
- Material mix evolution: Polypropylene remains the workhorse for bumpers—valued for low density, impact resistance, and cost efficiency—supporting lightweight vehicle design. At the same time, pockets of demand for steel, aluminum, and composites persist where durability, repairability, or premium positioning matter.
- Raw-material cost signals: Regional price movements for polypropylene and propylene feedstock softened in late-2025, reflecting weaker packaging and automotive demand in some Asian markets. Volatility in feedstock markets will determine the relative competitiveness of polymer-based versus metal bumpers through 2026.
- Recycling and circularity: Policy and commercial initiatives are accelerating closed-loop experimentation. Programs piloted in Europe and select North American locales show OEMs and recyclers converting end-of-life bumpers into reprocessed PP feedstock—an enabler of recycled-content mandates and a vector for sustainable differentiation.
- Aftermarket segmentation: The aftermarket is bifurcating: one track emphasizes low-cost CAPA/OEM-style painted replacements for mass-market vehicles; the other targets performance, offroad, and heavy-duty segments where steel and specialty finishes command premium margins and brand loyalty.
Competitive Landscape: Who to Watch
The market is populated by distinct competitor archetypes: specialized heavy-duty fabricators, precision offroad manufacturers, premium aftermarket OEMs, and parts suppliers focusing on painted body panels. The following firm-level perspectives highlight strategic postures relevant to 2026 planning:
Car Bumpers Market
- Buckstop Truckware (Prineville, OR) — An established manufacturer of heavy-duty aftermarket steel and winch bumpers for domestic truck platforms. Recent capacity shifts, including a facility relocation completed in mid-2026, signal a readiness to increase throughput and accelerate aftermarket delivery times. For incumbents and investors, Buckstop’s move highlights the importance of flexible U.S. fabrication capacity to serve regional aftermarket demand.
- Expedition One (Ogden, UT) — Focused on precision-built 4x4 offroad bumpers and overland accessories, this profile represents the premium, experience-driven aftermarket segment. Products in this category prioritize modularity and accessory integration (winches, lighting, sensors), offering higher margins but requiring close alignment with enthusiast channels and digital community engagement.
- Fab Fours (Lancaster, SC) — A U.S.-based manufacturer of premium steel truck and SUV bumpers and rock sliders. Their positioning underlines a continued domestic appetite for rugged, durable bumpers where repairability and heavy-duty performance trump lightweighting—an important counterbalance to polymer-focused OEM strategies.
- Partify (Warren, MI) — A supplier of painted aftermarket body parts and CAPA/OEM-style replacements, Partify exemplifies the mass-replacement channel with service-level differentiation (warranties, paint match, logistics). Partnerships between such suppliers and insurer/repair ecosystems represent a durable demand channel.
Across these archetypes, strategic choices in 2026 should focus on: manufacturing flexibility, aftermarket channel partnerships, and the ability to integrate recycled-content materials without compromising quality or warranty promises.
Regulatory & Sustainability Forces
- Policy acceleration in 2025–2026: European regulatory bodies released policy options for boosting plastic recycling in the automotive sector in late 2025. Complementary municipal-level moves—such as bans on automotive plastics to landfills—are catalyzing commercial recycling initiatives and local take-back schemes.
- Corporate recycling initiatives: Industry actors and recyclers have moved from pilots to scaled programs, collecting damaged or end-of-life PP bumpers and reprocessing them into new material streams—an operational reality that lowers the barrier to recycled-content mandates and can create a new feedstock arbitrage if collection logistics are optimized.
- Design-for-recycling: The next wave of competitive differentiation will be product designs that ease disassembly, reduce mixed-material joins, and enable high-value polymer streams—actionable levers for 2026 product development roadmaps.
Practical Implications & Strategic Playbooks for 2026
PW Consulting’s analysis translates market dynamics into decision-ready plays across four archetypal stakeholders:
- OEMs: Adopt modular bumper architectures that allow a single vehicle platform to accept different material inserts or reinforcement options. Prioritize validated recycled-content formulations and pilot closed-loop sourcing agreements in 2026 to smooth compliance risk and brand exposure.
- Tier Suppliers & Fabricators: Invest selectively in dual-capacity lines (polymeric injection/compression molding plus metal fabrication) and flexible finishing cells. Lock in feedstock flexibility—either through hedged contracts or strategic JV with recyclers—to maintain margin resilience if polymer costs rebound.
- Aftermarket & Specialty Brands: Differentiate via service—warranties, rapid-fit painted parts, and accessory ecosystems. For premium offroad and heavy-duty suppliers, prioritize direct-to-consumer community engagement and accessory modularity to capture higher lifetime value.
- Private Equity & Strategic Investors: Look for consolidation targets with strong aftermarket channels or proprietary supply-chain relationships (e.g., take-back/recycling contracts). M&A in 2026 will be most accretive where synergies reduce material cost exposure or expand aftermarket distribution networks.
What the Full PW Consulting Report Delivers (Practical, Executable)
Our comprehensive study goes beyond headline forecasts to deliver operational tools for 2026 implementation, including:
- Detailed demand models by geography, application, and material type (with customizable scenarios and sensitivity to feedstock price swings).
- Unit-cost and margin models for polymer versus metal bumpers across production scales.
- Supply-chain heatmaps and supplier risk matrices identifying single-source exposures and logistics choke points.
- Competitive dossiers, including capability audits and M&A readiness assessments for leading aftermarket and OEM suppliers.
- Regulatory scenario planning and compliance playbooks for recycled-content mandates and landfill diversion rules.
- Go-to-market strategies for aftermarket entrants and OEM sourcing tender templates for recycled-content procurement.
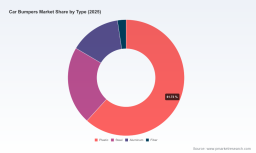
The public preview intentionally omits in-report tables that break down regional, application, and type-specific revenues and market shares—these are included in the full database and interactive models that PW Consulting provides to paying clients to support investment memoranda, sourcing RFPs, and product roadmaps.
Final Strategic Takeaways for 2026
- 2026 is a year to operationalize flexibility: invest in manufacturing adaptability and supply relationships rather than heavy, single-technology capital outlays.
- Material strategy is a profit lever: aligning design, procurement, and recycling partnerships will reduce cost exposure and meet tightening policy demands.
- Aftermarket remains a durable margin pool—differentiate by channel, service, and integration with repair ecosystems.
- Regulatory and municipal actions are moving the economics of recycling; early movers in take-back and recycled-content will gain both cost and reputational advantage.
Next Steps
For 2026 decision cycles, PW Consulting recommends commissioning the full report and accompanying model set to convert these strategic imperatives into executable project plans. Our full deliverable includes the granular segmentation, live spreadsheets, supplier scorecards, and board-level briefings that boards and executive teams need to authorize capital, M&A, and strategic partnerships with confidence.
For detailed analysis of this topic, please visit the official page: Car Bumpers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com