

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cephalosporin Market — USD 17,700M in 2025, 3.0% CAGR to 2032

Cephalosporin Market 2026 — Strategic Briefing for Executive Decision-Making
Executive snapshot
The global cephalosporin market is transitioning from a commodity antibiotic landscape into an arena shaped by supply‑chain concentration, regulatory repricing and targeted product innovation. Using a 2025 base year, PW Consulting’s proprietary modeling captures a market that reached approximately USD 17,700 Million in 2025 and moves forward at a steady compound annual growth rate (CAGR) of roughly 3.0% across our 2026–2032 forecast window. Under our baseline scenario, total market value expands materially by 2032, reflecting a combination of moderate demand growth, lifecycle substitution from older molecules, and premiumization driven by combination therapies and hospital‑procured sterile injectables.
Cephalosporin Market
Why this report matters for 2026 strategic choices
- Capital allocation — Prioritise investments in assets and geographies that hedge tariff and raw‑material concentration risks while capturing the upside from higher‑margin sterile injectable and late‑generation cephalosporins.
- Supply‑chain strategy — Decide between vertical integration, dual‑sourcing, or long‑term procurement contracts to neutralize concentrated intermediate supply and tariff exposure.
- Portfolio management — Balance generics volume plays (which continue to dominate the market) with selective innovation and fixed‑dose or combination therapeutic entries that command premium pricing and faster hospital adoption.
- M&A and partnerships — Use focused inorganic plays to secure capacity, regulatory dossiers and regional market access in an environment where three players control a meaningful share of the market (CR3 ~35%; CR5 ~42%).
- Regulatory readiness — Align site investments and clinical/regulatory timelines with accelerated review pathways for priority antimicrobials in the US and China.
Market dynamics: the structural forces shaping 2026
Three structural dynamics dominate the near‑term landscape.
Cephalosporin Market
- Supply concentration of key intermediates. A small number of Chinese production clusters continue to account for the bulk of 7‑ACA and 6‑APA intermediates and related fermentation outputs. This concentration creates meaningful pricing and reliability leverage for those suppliers and translates into tangible operational risk for global purchasers.
- Trade and tariff pressure. Since early 2025 expanded tariff measures have raised landed costs for some Chinese API and intermediate imports. In practical terms, increased duties have created new landed‑cost thresholds that procurement teams must bake into tender pricing and long‑term sourcing decisions.
- Regulatory and reimbursement context for generics and new entries. Generics remain the backbone of the market (more than half of total volume is supplied by off‑patent molecules), driven by hospital procurement policies and established formularies. At the same time, regulators in major markets are prioritising reviews for novel cephalosporin combinations addressing antimicrobial resistance, which creates windows for premium product launches if manufacturers can demonstrate GMP‑compliant production and robust clinical dossiers.
Recent industry developments (signals you cannot ignore)
- May 2026 — Regulatory green light: A US regulatory authority approval for a cefepime + beta‑lactamase inhibitor combination underscores the market’s movement toward combination therapies for complicated Gram‑negative infections; this approval illustrates both the clinical and commercial upside for differentiated products that address resistance.
- 2025–2026 — Capacity and licensing activity: Targeted plant inaugurations and new approvals in Asia signal demand for injectables and reinforce the strategic importance of regional manufacturing footprints in the face of trade friction.
Strategic implications and recommended plays for 2026
Executives should treat 2026 as a year to rebalance risk against optionality. Tactical and strategic moves with the highest expected value include:
Cephalosporin Market
- Sourcing diversification or nearshoring. Move beyond single‑cluster dependency by securing alternative suppliers in India, Europe or inland Chinese provinces, or by structuring joint ventures that provide priority access to intermediates.
- Dual‑track manufacturing investments. Invest selectively in modular sterile injectable capacity that can be scaled for both cephalosporins and other beta‑lactam classes; modularity reduces capital risk and accelerates time‑to‑market for high‑margin hospital products.
- Lifecycle management for generics. Use tender intelligence to identify generics with durable hospital demand and low price elasticity; pair volume supply agreements with low‑cost manufacturing to defend margin corridors.
- Premiumization via differentiated combinations. Prioritise R&D and regulatory filings for combination antibiotics that can access priority review pathways and command differentiated reimbursement in hospital formularies.
- M&A and capability buys. Pursue bolt‑on acquisitions to acquire GMP dossiers, sterile fill capabilities or regional market access—particularly where incumbent players hold concentrated shares but lack full end‑to‑end integration.
- Procurement and pricing playbook. Redesign procurement contracts to include tariff‑pass‑through clauses, indexation to intermediates, and co‑investments in supply security to stabilise long‑term costs.
Competitive landscape — who to watch and why
The competitive field is a mix of large diversified multinationals, speciality European manufacturers, and high‑volume Indian and Chinese API producers. Several profiles are especially instructive for strategic planners:
- Aurobindo Pharma Ltd. (Hyderabad, India) — A major producer of semisynthetic cephalosporin APIs and intermediates with integrated fermentation and chemical synthesis capabilities; a natural partner or acquisition target for companies seeking secure API capacity.
- Lupin Ltd. (Mumbai, India) — A GMP‑certified manufacturer of both APIs and finished formulations; competitive on volume supplies for established generics.
- Cipla Ltd. and Sun Pharmaceutical Industries Ltd. (Mumbai, India) — Large diversified players with USFDA‑approved sites; strength in both oral and injectable portfolios and notable presence in hospital procurement channels.
- Orchid Pharma (Chennai, India) and Wockhardt Ltd. (Mumbai, India) — Specialist suppliers focused on parenteral APIs and sterile formulations; strategically significant for hospital injectable markets and combination product filings.
- Teva, Pfizer, GSK, Novartis, Merck — Global firms that balance branded innovation with generics scale; they are gatekeepers for certain regulated markets and can redistribute supply rapidly through global networks.
- Chinese manufacturers (e.g., Shandong Lukang, Qilu) — High‑volume API and intermediate producers that influence global pricing and supply rhythms; their operation and policy environment underpin the market’s short‑term supply dynamics.
Market concentration metrics indicate an industry that is neither highly fragmented nor dominated by a single incumbent: the top three firms hold roughly 35% of sales, and the top five about 42%. That structure favors strategic consolidation where target companies add capability or geography rather than pure scale.
What the PW Consulting Cephalosporin market study delivers
This report is engineered for decision‑makers who need both strategic context and implementable tactics. Included modules are:
- Granular market sizing and forecast models (2020–2032) with alt‑scenarios and sensitivity testing around commodity pricing, tariff shocks and accelerated regulatory approvals.
- Supply‑chain risk maps that identify single‑point‑failure suppliers, tariff exposure corridors and hedging levers for procurement teams.
- Regulatory tracker for major agencies (US FDA, NMPA, EMA) and an assessment framework for how approvals or priority reviews change commercial timelines.
- Commercial opportunity matrices by product archetype (legacy oral generics, sterile injectables, late‑generation cephalosporins, and novel combinations) designed to guide R&D and go‑to‑market resource allocation.
- Competitive benchmarking dossiers for the leading 15 manufacturers with capability scoring (API fermentation, semisynthesis, sterile fill, regulatory approvals) and acquisition attractiveness indices.
- A procurement and pricing playbook tailored for hospital tender environments, including contract clauses, indexation approaches and risk‑sharing templates for customers and suppliers.
- Deal origination lists and quick‑win M&A targets scored on strategic fit, regulatory cleanliness and capacity uplift potential.
- Interactive Excel models and executive dashboards enabling rapid scenario analysis for Board presentations and investment committees.
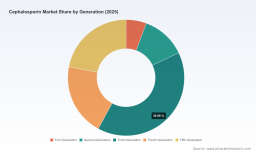
Note: while the public briefing above outlines core themes and high‑level figures, the report contains detailed splits by generation, application, region and route, as well as cell‑level forecasts and company‑level revenue estimates. These granular datasets and benchmarking tables are available exclusively in the full report and associated data pack.
How to use this intelligence in 90 / 180 / 360 days
- 90 days: Run a supply chain audit to quantify exposure to concentrated intermediates and renegotiate top‑tier supplier contracts to include contingency supply clauses.
- 180 days: Evaluate two strategic options—(a) a targeted joint venture in an alternative manufacturing hub, or (b) retrofit of modular injectable capacity—and model P&L outcomes under tariff stress scenarios.
- 360 days: Execute a priority regulatory filing for one differentiated product or a small bolt‑on acquisition to secure API capacity and accelerate hospital adoption pathways.
Conclusion — the 2026 mandate
For executives, 2026 is the year to convert awareness of structural risk into concrete strategic positioning. The cephalosporin market offers predictable top‑line growth and attractive cash generation for the right owners, but that potential is contingent on active management of supply concentration, tariff exposure and regulatory timing. PW Consulting’s market study provides the integrated analytics and the executable playbook to inform capital allocation, commercial tactics and M&A decision‑making. The overview presented here is intended to demonstrate the depth of our analysis—full granular breakouts, scenario inputs and company‑level financials are provided in the complete report and data package.
To access the comprehensive dataset, interactive models and the full competitive dossiers that underpin these conclusions, please visit our report page or contact PW Consulting’s Cephalosporin Practice Lead for a briefing and executive deck.
For detailed analysis of this topic, please visit the official page: Cephalosporin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com