

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cell Isolation Market to Grow at 13.62% CAGR Through 2032

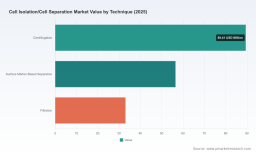
Cell Isolation & Cell Separation Market — Strategic Brief for 2026 Decision-Makers
Executive overview
As cell-based science accelerates from bench research to approved therapies and high-volume biomanufacturing, the cell isolation and separation market is maturing into a strategic infrastructure layer for life-science organizations. PW Consulting’s latest study (base year 2025) frames that transition with a data-driven market trajectory: from an estimated market in 2025 to a long-term forecast through 2032 driven by a compounded annual growth rate of 13.62%. The market’s historical evolution and multi-year forecast together illuminate where near-term investments will compound into sustainable advantage by 2028–2032.
Cell Isolation/Cell Separation Market
Market trajectory at a glance
-
Historical momentum: Our modeling traces a rapid recovery and expansion from the 2020 inflection point through 2025, reflecting increased adoption across research, clinical translation and early commercial cell therapy manufacturing.
Cell Isolation/Cell Separation Market -
Near-term inflection (2026): The market is set to continue its strong growth into 2026 and beyond; our forecast period (2026–2032) quantifies this momentum and scenarios for scale-up across both instruments and consumables.
Cell Isolation/Cell Separation Market -
Market structure: Concentration metrics indicate a market where a handful of global players retain meaningful share but room remains for specialist entrants and regional service providers to capture niche and adjacencies.
Why this report matters for 2026 corporate strategy
-
Investment prioritization — R&D vs. scale: The report identifies which product archetypes (automation platforms, high-throughput sorters, disposable consumables, closed-system processing) generate faster commercial ramp and recurring revenue, enabling finance and R&D leaders to prioritize capital allocation and product roadmaps.
-
M&A and partnership signal-mapping: Consolidation is selective and strategic. The study provides acquisition targets and partnership archetypes that accelerate entry into clinical GMP workflows, high-throughput sorting, or service-delivery models without overpaying for low-margin instrumentation.
-
Go-to-market optimization: With changing reimbursement and regulatory signals, device makers and CMOs must align sales channels, value propositions and pricing policies to both research and clinical buyers. Our analysis translates market growth into addressable opportunity by buyer persona and procurement cycle.
-
Regulatory & reimbursement readiness: The full research frames immediate compliance actions and payer engagement strategies that materially affect commercial timelines for clinical and commercial-scale cell processing.
What’s inside the report — practical outputs for action
-
Robust market sizing & scenarios: Bottom‑up market models (base year 2025) with sensitivity scenarios for conservative, base and accelerated adoption paths through 2032. Each scenario ties directly to key adoption drivers so leaders can stress-test investment choices.
-
Go-to-market playbooks: Tactical GTM templates for vendors and service providers, including channel selection matrices, segmented pricing playbooks, and customer-value messaging tailored for academic labs, biopharma CDMOs, and hospital/diagnostic end users.
-
Technology roadmaps and adoption curves: Comparative timelines for automation, magnetic separation, flow-based sorting and filtration modalities — including recommended trigger points for product launches and upgrade cycles.
-
Operational and manufacturing KPIs: Benchmarks for throughput, yield, cost-per-sample, and cleanroom/GMP conversion paths to guide capital equipment decisions and scale-up investments.
-
Regulatory & reimbursement playbook: Actionable guidance to align product development and submission strategies with evolving payer rules and device pathways, and checklists for GMP transition, ISO 13485 compliance and clinical trial integration.
-
Competitive landscaping and vendor scorecards: Deep, qualitative assessments (strengths, vulnerabilities, product roadmaps) of tier‑1 and emerging vendors with pragmatic partner evaluation criteria for alliances, OEM and distribution agreements.
-
M&A & corporate development toolkit: Valuation comparables, deal archetypes, integration risk checklists and a shortlist of capability gaps that acquisitions or JVs can rapidly fill.
-
Case studies & commercial pilots: Real-world examples illustrating how lab networks, CMOs and instrument vendors moved from pilot projects to recurring revenue models.
Competitive landscape — core players and strategic implications
The market is shaped by a mix of specialized innovators and diversified life‑science conglomerates. The competitive narratives below synthesize each player’s strategic posture and the near-term implications we expect to matter for 2026 planning.
-
STEMCELL Technologies Inc. — A specialist in immunomagnetic kits and automated sorters, STEMCELL’s recent acquisition of high‑throughput sorter technology accelerates its push into automated, high-purity sorting for cell therapy manufacturing. Expect bundled consumable+automation offerings and expanded service/validation support as their priority.
-
Miltenyi Biotec — A leader in clinically oriented magnetic-activated cell sorting and closed-system platforms with strong GMP pedigree. Its platforms are positioned for clinical translation; regulatory endorsements and clinical customer referenceability remain core advantages.
-
Thermo Fisher Scientific — Leverages scale and breadth across reagents, beads and instrument lines to offer end-to-end workflows for bead-based therapies. Their strategic play is integration — from consumables to manufacturing-scale workflows — and competitive pricing at volume.
-
Becton, Dickinson and Company (BD) — With flow cytometry systems and reagent suites, BD targets high-throughput, high-purity sorting for both research and translational labs. BD’s channel reach into hospitals and diagnostic labs is a powerful route-to-market for in-vitro diagnostics adjacent use-cases.
-
Danaher (Cytiva) — Focused on closed, GMP-scale processing and filtration systems, Cytiva is a natural partner for biomanufacturers scaling to commercial cell therapy batches. Its strength is process integration with bioprocessing ecosystems.
-
Merck KGaA (MilliporeSigma) , Agilent , Beckman Coulter , Terumo BCT , Lonza , Bio‑Rad — Each brings pockets of strength: reagent platforms, analytical/sorter combos, apheresis and clinical processing, or GMP-oriented consumables. Strategic partnerships and co-development agreements are the fastest way for niche vendors to scale with these incumbents.
Recent developments and regulatory backdrop
-
Notable transactions and service launches signal an emphasis on automation and outsourced services. For example, the integration of high‑throughput sorting technology into incumbents’ portfolios and the launch of commercial FACS services in regulated markets are early indicators of a shift toward service-enabled revenue models.
-
Regulatory and payer shifts materially affect unit economics. Recent policy changes that integrate certain manufacturing steps into reimbursement calculations and limited device exemptions under humanitarian pathways introduce both opportunities and constraints for commercialization timelines.
-
Quality and device certification remain table stakes. Major platforms adhere to ISO 13485 and other GMP-relevant standards — a requirement for market access in clinical programs and aggregated purchasing by CMOs and hospitals.
-
Emerging designations for manufacturing technologies that reduce process impurities are accelerating adoption in therapeutic manufacturing, and companies that can evidence lower host‑cell DNA or improved safety attributes can capture premium positioning.
Strategic imperatives for 2026
-
Prioritize consumables-led monetization: Consumables drive recurring revenue and create platform lock-in. Product leaders should design upgrade paths that combine single-use kits with subscription inventory models and validation support.
-
Invest selectively in automation that unlocks scale: Automation investments should be prioritized where they demonstrably reduce cost-per-dose, reduce variability, and shorten release cycles — criteria that matter to CDMOs and large biopharma customers.
-
Embed regulatory strategy into product design: Early alignment with GMP, ISO 13485 and payer requirements reduces time-to-market friction. Consider clinical-grade SKU roadmaps and companion validation packages for rapid customer qualification.
-
Build service and lab-network offers: Outsourced processing and commercial FACS services are accelerating. Vendors that can provide validated service networks or asset-light partnerships with third‑party labs will capture a portion of outsourced spend.
-
Use M&A to fill capability gaps: Bolt-on acquisitions in automation, high-throughput sorting, or software for process analytics can compress time-to-market and achieve scale economies faster than organic development.
-
Engage payers and policy makers proactively: Changes to reimbursement treatment for cell-manufacturing steps require proactive engagement to preserve economic models for clinical and commercial therapies.
-
Harden supply chain and manufacturing readiness: Single-use consumables and bespoke reagents require resilient sourcing and predictable manufacturing scale plans to support larger clinical and commercial customers.
Final note — where to go next
PW Consulting’s full Cell Isolation/Cell Separation Market report provides the confidential, segment-level breakdowns, vendor scorecards and model files needed to translate the headline growth trajectory into executable 12–36 month plans. This strategic brief is structured to show the depth of our analysis while preserving the detailed segmentation and financial models that are the operational tools for decisive action. For the full dataset, scenario workbooks and bespoke advisory support to convert this intelligence into a tailored market-entry or scale-up plan, please refer to the PW Consulting report page or contact our advisory team.
For detailed analysis of this topic, please visit the official page: Cell Isolation/Cell Separation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com