

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PID Sensors Market to Reach USD 304.7M by 2032 at 6.5% CAGR

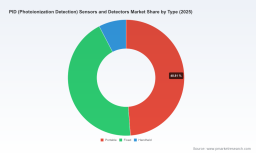
PID Sensors and Detectors Market — Strategic Outlook for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present a concise, decision‑focused preview of our new PID (Photoionization Detection) Sensors and Detectors Market study. The attached research is designed to arm executives, product strategists, and investors with the practical intelligence they need to make confident 2026 choices — from R&D priorities and go‑to‑market planning to M&A and compliance investments. This preview demonstrates the analytical depth and actionable framing you will find in the full report while deliberately withholding the detailed segment tables and proprietary breakouts that drive tactical execution.
PID (Photoionization Detection) Sensors and Detectors Market
Market trajectory at a glance
PID sensor and detector demand has moved beyond niche environmental projects and is now a staple of industrial safety and continuous environmental monitoring programs. Our analysis uses 2025 as the base year and covers historical performance from 2020–2025 and a forecast horizon through 2032. The market expanded from roughly USD 120.5 Million in 2020 to an estimated USD 195.0 Million in 2025, and our central forecast shows compound annual growth of 6.5% over the 2026–2032 window, bringing the market to approximately USD 305 Million by 2032. That trajectory reflects accelerating adoption across compliance‑led monitoring, remote infrastructure deployments, and replacement cycles driven by upgraded sensor performance.
PID (Photoionization Detection) Sensors and Detectors Market
Why this research matters for 2026 decisions
- Timing for investment and product bets: With mid‑single‑digit CAGR and clear pockets of accelerating demand, 2026 is a window to scale production capacity, secure component supply, or fast‑track next‑gen lamp and electronics improvements that yield step changes in field performance.
- Regulatory and standards risk management: VOC exposure limits, evolving EU regulatory frameworks, and calibration accreditation expectations are changing procurement criteria — companies that map product specs to compliance outcomes will win enterprise contracts.
- Commercial prioritization: The market is neither fragmented chaos nor monopolized dominance — strategic consolidation and targeted partnerships can produce disproportionate returns if timed to forecast inflections.
- Operational resilience: Battery life and low‑power electronics matter for portable/handheld use cases. Operational plans that ignore electronics and calibration economics will underperform in real deployments.
Market dynamics that will shape corporate strategy
- Regulatory push drives procurement: Stricter VOC exposure thresholds and chemical registration requirements have pushed large industrial buyers and environmental agencies to prioritize PID‑based solutions for real‑time verification and compliance documentation.
- Standardization and calibration: ISO 17025 accreditation requirements for calibration labs raise the bar for vendors offering calibration services and after‑sales support. Buyers increasingly evaluate total cost of ownership, not just sensor purchase price.
- Technology differentiation: Recent product introductions emphasize ppb‑level sensitivity, longer lamp life, and sensor‑to‑sensor repeatability. Those attributes reduce field recalibration and improve data quality — critical differentiators for high‑value contracts.
- Infrastructure integration: Remote monitoring architectures in oil & gas, petrochemical, and large chemical plants are integrating PID sensors into SCADA and cloud analytics for plume tracking and leak localization. That trend elevates systems integrators as strategic channel partners.
- Power and portability constraints: Achieving ppb sensitivity while maintaining battery life requires trade‑offs in electronics design. Solutions that optimize ultra‑low power consumption while preserving analytical performance will capture a growing share of portable and handheld segments.
Competitive landscape — what to watch
The market is characterized by a compact set of established vendors, several of which have invested heavily in product upgrades and brand initiatives over the past 18–24 months. Top vendors account for a material share of the market, with the three largest players occupying roughly a third of sales and the top five just over half — a structure that encourages both competitive R&D and opportunistic consolidation.
PID (Photoionization Detection) Sensors and Detectors Market
- ION Science Ltd (Fowlmere, UK) — Recognized as a market leader in PID sensor manufacture, ION Science has broadened its portfolio and launched a new brand to sharpen innovation positioning. Their moves signal continued focus on performance‑oriented detectors and multi‑gas platforms for compliance monitoring.
- Alphasense (Chorleywood, UK) — Alphasense’s PIDX range targets sensor‑to‑sensor repeatability and extended lamp life, directly addressing OEM concerns about calibration burden. Their technology roadmap suggests a push into higher‑volume OEM deployments.
- AMETEK MOCON (Brooklyn Park, USA) — A key OEM supplier with newly introduced piD‑TECH sensors designed for industrial safety and environmental monitoring. AMETEK’s product refreshes highlight the competitive focus on accuracy and field usability.
- PID Analyzers, LLC (HNU, Sandwich, USA) — Offers PID‑branded analyzers across air, water, and process monitoring, maintaining a stable role in specialized applications and channel partnerships with system integrators.
- RKI Instruments (Hayward, USA) & WatchGas (UK) — Both firms round out the competitive map with differentiated portable/multi‑gas detector offerings that embed PID functionality for VOC detection in safety and industrial use cases.
Recent product launches and brand initiatives through 2024–2025 have intensified competition around lamp life, repeatability, and integration readiness. For example, AMETEK MOCON’s introduction of a next‑generation piD‑TECH sensor and Alphasense’s PIDX range are explicit attempts to capture the OEM upgrade cycle. ION Science’s new brand and multi‑gas detector introductions further demonstrate how incumbents are broadening their addressable market.
Strategic implications and recommended actions for 2026
- Manufacturers & OEMs: Prioritize modular, drop‑in designs and standardized calibration interfaces. Investments in lamp technology, sensor repeatability, and low‑power electronics will reduce buyer switching costs and lengthen product lifecycles.
- Channel & system integrators: Build calibration and data‑management services into contracts; create bundled offerings that combine PID hardware, accreditation‑compliant calibration, and analytics for regulatory reporting.
- End‑users (industrial, governments): Treat PID procurement as a system purchase — include lifecycle calibration costs, data quality requirements, and integration timelines in RFPs. Prioritize vendors that can demonstrate ISO 17025 calibration pathways and proven field performance.
- Investors & corporate development: Look for M&A opportunities that close gaps in calibration networks, software analytics, or low‑power electronics capabilities. Given market concentration, small bolt‑on acquisitions can rapidly scale addressable offerings and margin profiles.
- Product strategy teams: Use multi‑scenario roadmaps to balance near‑term portable/handheld upgrades with mid‑term fixed‑monitoring deployments tied to remote‑monitoring architectures.
What PW Consulting’s full report delivers (practical highlights)
Our full PID Sensors and Detectors Market report is structured to convert insight into action. Key deliverables include:
- Validated market sizing and a 2026–2032 forecast model, with sensitivity analysis and scenario variants that reflect regulatory and technology risk.
- Go‑to‑market playbooks for OEMs, distributors, and systems integrators that include pricing archetypes, contract structures, and channel economics.
- Vendor benchmark and capability heatmap — assessing product performance (sensitivity, lamp life, repeatability), calibration support, and integration readiness.
- Supply‑chain and component risk analysis, with recommendations to de‑risk lamp and electronics sourcing through strategic supplier agreements or dual sourcing.
- Regulatory impact assessment and compliance cost templates that map VOC/REACH/CLP scenarios to procurement and lifecycle costs.
- Operational models for calibration and after‑sales services, including a guide to building ISO 17025‑aligned calibration networks or partner ecosystems.
- M&A and investment shortlist with rationale and integration playbooks focused on targeting capability gaps rather than geographic expansion alone.
Each section is accompanied by pragmatic templates — procurement checklist, RFP language, total cost of ownership calculator, and deployment sequencing guidance — enabling rapid translation from insight to boardroom decisions.
How to apply this intelligence in 2026 — five practical moves
- Embed calibration economics into every product business case: require TCO analyses that include ISO 17025‑compliant calibration to avoid post‑purchase surprises.
- Prioritize low‑power, ppb‑capable product lines for pilot deployments in remote monitoring; these pilots will validate upgrade economics for larger fixed installations.
- Pursue strategic OEM partnerships that offer drop‑in replacements and clear upgrade paths to lock in channel partners and reduce long‑term churn.
- Align R&D roadmaps with regulatory timelines: calibrate feature release schedules to expected compliance deadlines in key verticals to capture early procurement cycles.
- Evaluate targeted acquisitions that instantly add calibration capacity, analytics software, or low‑power electronics expertise rather than green‑field investment.
Final note — what this preview omits and where to go next
This preview intentionally demonstrates the report’s analytic sophistication while withholding the granular segment tables, region‑by‑application splits, and proprietary vendor scoring that we use to recommend specific tactical actions. Those segment‑level figures and supplier scorecards are the core proprietary assets of the full PID Sensors and Detectors Market study and are available in the complete report.
If your 2026 planning requires precise addressable market sizing by channel, product variant, or application, or if you want bespoke scenario runs calibrated to your product roadmap, PW Consulting can provide the full dataset, vendor heatmaps, and customized advisory support. Our team will help translate the market forecast into procurement specs, product roadmaps, and M&A playbooks that deliver measurable returns within 12–24 months.
For detailed analysis of this topic, please visit the official page: PID (Photoionization Detection) Sensors and Detectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com