

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hybrid Adhesives & Sealants Market — USD 8,879M in 2025; 6.12% CAGR to 2032

Hybrid Adhesives & Hybrid Sealants Market — Strategic Outlook for 2026 Decision Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a condensed strategic primer drawn from our forthcoming Hybrid Adhesives & Hybrid Sealants Market study (base year 2025). This brief is designed as a high-value preview for executives who must make decisive 2026 investments — in procurement, R&D, capacity, M&A, and go-to-market — while intentionally withholding the granular segment tables and country-level allocations that make up the full paid report.
Hybrid Adhesives & Hybrid Sealants Market
Market at a Glance: Trajectory and Structural Facts
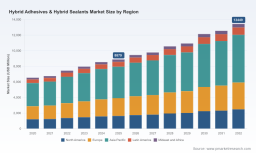
The hybrid adhesives and sealants market is exhibiting steady, structurally supported expansion. Our market model pegs the global industry at approximately USD 8,879 million in 2025, growing at a compound annual growth rate (CAGR) of 6.12% across the 2026–2032 forecast window. Under the baseline scenario, the market is modeled to cross the USD 13 billion mark by the end of the forecast horizon.
Hybrid Adhesives & Hybrid Sealants Market
This is not a cyclical blip: the historical series from 2020 through 2025 shows recovery and incremental acceleration as applications in construction, transportation electrification, and electronics drive sustained demand. At the same time, market concentration metrics indicate a moderate-to-high consolidation profile with the top three players capturing a meaningful share of demand and the top five controlling well over half of total revenues — an important consideration for competitors and buyers alike when assessing negotiation leverage and innovation partnerships.
Hybrid Adhesives & Hybrid Sealants Market
What’s Driving Growth — and What Could Stall It
- Demand-side vectors: Structural demand is underpinned by building & construction renovation cycles, expanding automotive applications (notably EV battery and lightweight assembly), and increased electronics packaging complexity. Hybrid chemistries are displacing legacy silicones and polyurethanes where formulators can offer multi-performance benefits (adhesion, elasticity, low-VOC emissions).
- Supply-side constraints and raw material volatility: Input-cost dynamics are now a central strategic risk. Recent industry events — including major silicone suppliers announcing double-digit price adjustments and acute silane spot-price pressure linked to photovoltaic feedstock demand and trade barriers — have materially increased production cost uncertainty. Tariffs and supply restrictions (including very high import duties in some markets) exacerbate cost pass-through challenges and inventory management complexity.
- Regulation and sustainability: Low-VOC formulations, greener precursors, and end-of-life considerations are shaping product road maps. Buyers will reward suppliers who can demonstrate lower life-cycle impact without compromising performance.
- Technology substitution and product innovation: The field is evolving beyond simple replacements: hybrid binders and silane-modified polymers are being engineered to meet multi-material bonding demands and faster cycle times, enabling new assembly processes across transport and industrial segments.
Competitive Landscape — Who Matters and Why
The competitive map is populated by consolidated global chemical majors and specialty formulators. Leading incumbents combine broad formulation portfolios with deep channel and OEM relationships; agile regional players compete on price and custom formulation services. Below is a high-level synthesis of strategic positioning among the core players covered in our study:
- Henkel AG & Co. KGaA (Düsseldorf, Germany): Leverages strong brand equity (Loctite, Teroson) and MS-polymer technologies with solutions tailored to automotive assembly and construction. Their R&D emphasis on low-VOC, flexible adhesive systems positions them well for regulatory-driven procurement.
- Sika AG (Baar, Switzerland): A dominant presence in construction and waterproofing with the Sikaflex MS polymer family. Sika’s global distribution and project-level engineering support make them a preferred partner on large infrastructure and commercial builds.
- 3M Company (Saint Paul, US): Differentiates through product-system selling and specialty hybrid adhesive-sealant platforms optimized for UV resistance and industrial bonding. 3M’s technical channels and OEM co-development capabilities are a strategic edge.
- Dow Inc. (Midland, US): Focused play in high-growth segments such as EV battery assembly and industrial bonding, leveraging polymer science to serve electrification trends.
- H.B. Fuller, Bostik (Arkema), Wacker, RPM, and others: These players form a second tier of scale and specialization: hot-melt hybrids, marine-grade formulations, and silane-modified polymers for niche industrial and construction use-cases. Several are accelerating production investments and regional capacity to de-risk supply chains.
Collectively, the market shows active strategic repositioning: production capacity investments, next-gen launches, and targeted product introductions aimed at application-specific performance improvements. Our full report includes competitive scorecards, product pipeline analyses, and supplier risk matrices for these companies.
Recent Developments — Signals You Need to Act On
- Manufacturing scale-up: In mid-2025, a major polymer producer commenced hybrid polymer production at a new European site, signaling renewed upstream investment and potential regional supply rebalancing.
- Next-generation product launches: Late-2025 saw leading adhesive brands introduce MS polymer hybrid solutions tailored for automotive display bonding with improved flexibility and sustainability credentials — a clear indicator that OEM demands for integrated performance and regulatory compliance are accelerating product development cycles.
- Input-price shocks: Since early 2026, notable suppliers have announced significant price increases on silicone inputs after catalyst cost escalations; simultaneously, silane spot markets remain elevated due to competing demand and tariff-driven import constraints. These signals point to an elevated near-term cost base and incentivize buyers to re-evaluate sourcing strategies and hedging frameworks.
Strategic Implications for 2026 Decision Makers
For 2026 corporate planning, the interplay of robust end-market demand and heightened raw-material volatility creates both opportunity and risk. Below are prioritized strategic actions that PW Consulting recommends for market participants, from OEMs and formulators to private equity and distributors.
- Procurement and supply security: Move from spot-centric buying to a hybrid procurement model: longer-term supplier contracts tied to indexed pass-through mechanisms, strategic stockpiles for critical silane and silicone derivatives, and secondary sourcing in lower-tariff jurisdictions. Evaluate supplier performance beyond price — include delivery, formulation fidelity, and sustainability metrics.
- Pricing and margin strategy: Implement value-based pricing for performance-differentiated hybrid solutions (e.g., EV battery adhesives or architectural low-VOC sealants). Use a tiered approach to recover input-cost inflation while protecting volume through contractual escalation clauses and shared-savings clauses for cost reductions.
- R&D and product roadmap: Prioritize chemistries that reduce dependency on tariff-exposed feedstocks and catalysts susceptible to price shocks. Accelerate low-VOC, lower-silane-content formulations, and modularized product platforms that can be rapidly tailored for OEM specifications.
- Capacity investment and localization: Target regional capacity expansions where demand growth is highest and supply-chain friction is most acute. For smaller players, consider toll-manufacturing partnerships with established producers to de-risk capital spend while retaining formulation IP.
- M&A and alliances: The mid-market is ripe for consolidation and capability acquisitions — especially specialist formulators with automotive or electronics credentials. Buyers should prioritize targets with unique formulations, long-term offtake contracts, or localized manufacturing footprints.
- Commercial go-to-market: Differentiate by bundling technical service, application testing, and certification support. Use pilot programs with OEMs to secure specification wins that create switching costs and recurring revenue streams.
What the Full PW Consulting Report Delivers (Operationally Focused)
Our full market study is structured to convert insight into action. Key deliverables include:
- Bottom-up revenue model and scenario forecasts (2026–2032) with sensitivity testing under alternative raw-material and tariff scenarios.
- Competitor scorecards with product portfolios, capacity maps, and strategic positioning assessments.
- Customer segmentation and buying-behavior archetypes for construction, transportation, electronics, and industrial OEMs.
- Detailed supplier risk matrix and procurement playbook (contract templates, indexing approaches, and stock buffer calculus).
- Go-to-market & commercialization playbooks, including value-pricing models and channel optimization recommendations.
- M&A target-screening tool and integration checklists for acquirers.
Note: In keeping with our “teaser-first” approach, this preview intentionally omits the granular segment tables, regional allocations, and per-application revenue tables that substantiate the forecast and inform precise tactical decisions. Those data layers are reserved for subscribers and report purchasers to preserve competitive intelligence value.
Recommended Next Steps for Executives — A 90-Day Roadmap
- Week 1–4: Convene a cross-functional Rapid Response Team (Procurement, R&D, Sales, Finance) to stress-test current supplier contracts and identify critical single-source exposures.
- Week 5–8: Launch RFPs for alternative silane/silicone supply and secure pilot of low-silane formulations with a preferred OEM to validate performance claims and pricing elasticity.
- Week 9–12: Finalize a prioritized investment case (capex vs. toll-manufacturing) and shortlist M&A or partnership targets assisted by our target-screening framework.
Closing — Why 2026 Is a Pivotal Year
The hybrid adhesives and sealants market in 2026 sits at the intersection of accelerating end-market demand and structural supply-chain stress. Companies that move early — securing diversified feedstock access, protecting margin through disciplined pricing, and differentiating via product performance and sustainability — will gain asymmetric advantage. PW Consulting’s full study provides the quantitative foundation and tactical playbooks you need to execute with conviction. For clients ready to convert insight into near-term action, the full dataset and scenario tools unlock the precise levers required to defend margin, capture growth, and evaluate strategic transactions in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Hybrid Adhesives & Hybrid Sealants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com