

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Machinery & Automotive
Air Intake Resonator Market: What the 6.85% CAGR Reveals About 2032 Growth
By pmarketresearch, 2026-09-18
Strategic Outlook: Navigating the Air Intake Resonator Market (2026–2032)
Market Overview and Core Challenges
The global air intake resonator market is characterized by steady, predictable growth driven by the broader automotive production landscape. Between 2020 and 2025, the market expanded from approximately $612.45 million to $812.4 million, reflecting a compound annual growth rate (CAGR) of 6.85% through the forecast period ending in 2032. This trajectory suggests a mature but evolving sector where volume growth is increasingly tied to technological refinement rather than raw unit production alone. By 2032, the market is projected to reach $1,291.2 million, indicating significant headroom for value creation despite the commoditization risks inherent in component manufacturing.
Regionally, the market weight is shifting. While North America and Europe remain substantial contributors with established OEM relationships, the Asia Pacific region currently represents the largest revenue share. This distribution highlights the dependency on manufacturing hubs in China, India, and Southeast Asia, where vehicle production volumes continue to outpace Western markets. However, reliance on these regions introduces exposure to supply chain volatility and varying regulatory timelines.
Three critical challenges define the current inflection point for industry stakeholders. First, the transition toward electrification complicates demand forecasting. While internal combustion engine (ICE) vehicles continue to dominate the global fleet, the long-term shift toward EVs threatens the traditional volume base for intake resonators, which are primarily designed for air-cooled combustion processes. Manufacturers must decide whether to pivot designs for hybrid applications or consolidate around ICE production in emerging markets where EV adoption lags.
PW Consulting Automotive & Machinery Research Center
Second, regulatory pressure is intensifying. Emission standards, particularly the EU Euro 7 framework, are expected to drive investment in advanced air intake systems that optimize combustion efficiency and reduce NOx and particulate emissions. Compliance is no longer optional but requires material and design changes that impact cost structures. Third, cost pressures from raw materials are reshaping bidding dynamics. The industry is seeing a divergence in material selection, where cost-effective polymers compete with high-performance engineering plastics, forcing suppliers to balance performance requirements against margin erosion.
Key Drivers of Market Dynamics
Several interconnected factors are propelling the market forward, creating both opportunities and constraints for participants. Understanding these drivers is essential for aligning product development and supply chain strategies with future demand.
Technological Innovation and Material Science
Material selection has become a primary battleground for performance differentiation. The industry is witnessing a dual-track development where glass-fiber-reinforced polyamides (PA6/PA66) continue to dominate premium turbocharged intake applications due to superior thermal resistance up to 220°C. These materials are critical for modern engines that operate at higher temperatures and pressures to meet efficiency targets. Conversely, polypropylene (PP) used in intake components offers a 15-20% cost reduction versus polyamide (PA) but is limited to lower temperature applications around 130-140°C. This cost-performance trade-off creates a segmentation opportunity where suppliers can target budget-conscious OEMs with PP solutions while retaining high-margin contracts with premium brands requiring PA-grade durability.
Innovation is not limited to materials. In-line resonators are capturing a larger share of the type segmentation compared to side branch resonators, reflecting a design preference for compact integration that minimizes engine bay footprint without sacrificing noise reduction. This shift aligns with the industry trend toward downsized, high-efficiency engines where packaging space is at a premium.
Policy and Regulatory Environment
Regulatory frameworks are acting as a forced catalyst for product upgrades. The anticipated implementation of EU Euro 7 emission standards is expected to drive investment in advanced air intake systems optimizing combustion efficiency and reducing NOx and particulate emissions. Unlike previous standards that focused heavily on tailpipe outputs, Euro 7 places greater emphasis on real-world driving emissions and durability, requiring intake systems that maintain performance consistency over the vehicle's lifespan. This regulatory shift benefits suppliers capable of engineering resonators that manage airflow turbulence and temperature more precisely, as inconsistent intake flow can lead to inefficient combustion and higher emissions.
In parallel, noise pollution regulations in urban centers are reinforcing the acoustic function of resonators. As cities impose stricter noise limits, OEMs are increasingly specifying resonators that contribute to overall vehicle sound signature management, extending the component's value proposition beyond mere engine protection.
Demand-Side Shifts and Consumer Behavior
Consumer preferences are bifurcating the market. On one end, the mainstream passenger car segment continues to drive the majority of volume, with buyers increasingly sensitive to fuel efficiency and engine smoothness. Resonators that contribute to quieter, more refined engine operation are becoming standard expectations rather than optional upgrades. On the other end, the performance aftermarket segment is showing renewed vigor. High-performance enthusiasts and modifications for trucks and SUVs are creating niche demand for resonator designs that balance airflow enhancement with sound tuning.
Recent product launches illustrate this demand divergence. In April 2025, K&N Engineering introduced NextGen Air Intake Systems for trucks and SUVs delivering horsepower gains, signaling sustained interest in performance-oriented intake upgrades. Similarly, in May 2025, Dinan released the LCI X3 M40i / X4 M40i Cold Air Intake with performance enhancements, targeting specific luxury performance models. These releases demonstrate that even as OEM volumes face long-term electrification risks, the aftermarket channel remains a viable growth vector for companies with strong brand recognition and engineering credibility.
Supply Chain and Cost Structure Evolution
Supply chain resilience has moved from a back-office concern to a strategic priority. The concentration of manufacturing in Asia Pacific means that geopolitical tensions, logistics disruptions, or regional policy changes can ripple through global availability. Suppliers are responding by diversifying supplier bases and exploring near-shoring options for critical components. Additionally, the cost structure is heavily influenced by polymer pricing volatility. The ability to switch between PP and PA based on application requirements provides a lever for cost management, but this requires flexible production lines and precise engineering validation to ensure material substitution does not compromise performance.
Cost pressures are also reshaping the competitive landscape. Companies that can achieve scale efficiencies while maintaining material flexibility are better positioned to protect margins during periods of raw material inflation. The market concentration, with the top three players holding a combined share of 38.5% and the top five at 52.7%, indicates that scale matters, but niche specialization can still command premium pricing.
Competitive Landscape and Leading Strategies
The market is defined by a mix of global Tier-1 suppliers, specialized automotive component manufacturers, and aftermarket performance leaders. Each segment employs distinct strategies to capture value, reflecting different risk tolerances and customer relationships.
Strategic Positioning of Key Players
MANN+HUMMEL stands out as a global leader in filtration solutions, designing and manufacturing air intake systems and resonators integrated into air cleaner housings for passenger cars, heavy-duty, and industrial applications. Their strategy centers on noise reduction and performance optimization, leveraging a broad portfolio that spans multiple vehicle segments. By integrating resonators directly into air cleaner housings, MANN+HUMMEL reduces separate component complexity for OEMs, offering a value proposition based on systems integration and reliability.
Röchling Automotive specializes in air intake systems with high-frequency resonators for optimized sound and performance. Their focus on integrating resonators, ducts, and filtration components for OEM automotive propulsion systems positions them as a solutions provider rather than a commodity parts supplier. This integration capability allows Röchling to capture higher margins by solving multi-functional requirements such as acoustic tuning, airflow management, and filtration in a unified design.
Toyoda Gosei manufactures air cleaner hoses with resonators and noise-absorbing air intake ducts to reduce engine intake noise while providing clean air for engine efficiency. Their approach emphasizes noise absorption and efficiency, catering to OEMs that prioritize refined engine characteristics. As a Japanese manufacturer, Toyoda Gosei benefits from strong relationships with domestic automakers and suppliers, though they face competition from European and North American players expanding into Asian markets.
Worldwide Automotive Air Filter Housing Market
Magna International provides comprehensive powertrain and vehicle engineering including air intake systems and components as part of broader automotive solutions for OEMs. Magna's scale and engineering breadth allow them to offer air intake resonators as part of a larger package, which can be attractive to OEMs seeking single-source accountability for complex vehicle subsystems. This holistic approach differentiates Magna from component-only suppliers.
Automotive Air Intake Manifold Market
K&N Engineering occupies a unique position as an aftermarket performance leader, offering cold air intake systems, some incorporating or compatible with resonator designs for enhanced airflow and sound. Their strength lies in brand loyalty among performance enthusiasts and a direct-to-consumer channel that bypasses traditional OEM supply chains. K&N's ability to deliver horsepower gains and sound enhancement makes them a benchmark for aftermarket quality, creating a halo effect that can influence OEM specifications indirectly.
Market Evolution and Competitive Trends
The competitive landscape is evolving through a combination of consolidation among large players and differentiation among specialists. The market concentration indicates that scale advantages are significant, encouraging mergers and partnerships that expand geographic reach and product portfolios. However, the presence of strong niche players like K&N Engineering suggests that specialization in performance or specific vehicle segments remains viable.
New entrants face high barriers due to the need for engineering validation, OEM qualification processes, and established supply chain relationships. However, companies that can innovate in material science or acoustic engineering may find opportunities to disrupt traditional supplier relationships, particularly if they can demonstrate clear advantages in cost or performance. The recent product activity from Dinan and K&N highlights that the aftermarket remains a dynamic space where innovation cycles are faster than in the OEM channel, providing a testing ground for new designs and materials.
Strategic differentiation is increasingly tied to material flexibility and regulatory compliance capabilities. Suppliers that can seamlessly switch between PP and PA grades based on application requirements, while meeting Euro 7 and noise standards, are better equipped to win contracts across diverse OEM segments. The ability to offer integrated solutions that combine resonators with filtration and ducting is also becoming a key differentiator, as OEMs seek to reduce assembly complexity and weight.
Future Trends and Commercial Opportunities
Looking toward the 2026–2032 horizon, several trends will shape the market's trajectory and create distinct commercial opportunities for prepared stakeholders.
Trend 1: Hybrids as a Bridge for Resonator Demand
The transition to full electrification will not be uniform across all markets. Hybrid vehicles, which retain ICE components alongside electric drivetrains, will sustain demand for air intake resonators in regions where full EV infrastructure is slow to develop. This creates a medium-term opportunity for suppliers to design resonators optimized for hybrid-specific operating conditions, such as frequent start-stop cycles and varied load demands. Manufacturers that can demonstrate improved durability and efficiency for hybrid applications will capture value from OEMs extending the life of ICE technology in hybrid platforms.
Trend 2: Material Innovation Driving Margin Recovery
As cost pressures persist, material innovation will be a critical lever for margin recovery. The divergence between PP and PA applications suggests that suppliers with expertise in material optimization can offer tiered solutions that match cost to performance requirements. Opportunities exist for companies that can develop novel composites or recycling pathways that reduce material costs while maintaining thermal and acoustic performance. Additionally, the push for sustainability may drive demand for resonators made from recycled polymers or bio-based materials, particularly in European markets where OEMs face pressure to reduce the carbon footprint of their supply chains.
Trend 3: Acoustic Performance as a Differentiator
Noise regulations and consumer expectations for refined vehicle acoustics will elevate the resonator's role beyond functional airflow management. Suppliers that can deliver precise acoustic tuning, reducing specific frequency bands associated with engine noise while maintaining airflow efficiency, will gain a competitive edge. This trend opens opportunities for collaboration with acoustic engineering firms or the development of proprietary tuning algorithms that optimize resonator design for specific engine families. The integration of resonators with active noise cancellation systems or variable geometry designs could further enhance value propositions for premium vehicle segments.
Risk Factors and Uncertainties
Despite these opportunities, risks remain. The pace of EV adoption could accelerate faster than anticipated in key markets, compressing the timeline for ICE component demand. Raw material costs could spike due to supply constraints or geopolitical events, squeezing margins for suppliers unable to pass costs through. Regulatory changes could also introduce new compliance requirements that increase engineering costs or delay product launches. Finally, the aftermarket segment, while dynamic, is subject to cyclical consumer spending and may not fully offset declines in OEM volumes if electrification progresses rapidly.
Strategic Actions for Decision Makers
Navigating the air intake resonator market requires aligned strategies across manufacturing, investment, and procurement functions. The following recommendations address the core priorities for each stakeholder group.
For Manufacturers and Suppliers
- Invest in material flexibility and engineering validation. Develop production capabilities that can efficiently switch between PP and PA grades based on customer requirements. Validate performance across temperature ranges to maximize application coverage while controlling costs.
- Strengthen hybrid and performance aftermarket capabilities. As ICE volumes face long-term headwinds, expand design expertise for hybrid-specific resonators and deepen aftermarket partnerships to capture growth from performance enthusiasts and modification markets.
- Align with regulatory roadmaps. Proactively engineer solutions that meet Euro 7 and emerging noise standards. Early compliance reduces qualification delays and positions suppliers as trusted partners for OEMs facing stringent emission targets.
For Investors and Strategic Partners
- Evaluate scale versus specialization. Assess potential targets based on their ability to leverage scale efficiencies while maintaining differentiated capabilities in material science, acoustic tuning, or aftermarket channels. Companies with both breadth and niche strength are better positioned to withstand margin pressures.
- Monitor regional shifts. Track production and demand trends in Asia Pacific, where volume growth is strongest, and assess exposure to supply chain risks. Investments in diversified manufacturing footprints or near-shoring capabilities can mitigate disruption risks.
- Consider aftermarket dynamics. Recognize that aftermarket performance brands can provide resilient revenue streams and brand visibility even as OEM volumes fluctuate. Partnerships or acquisitions in this space can offer growth avenues independent of traditional supply chain cycles.
For Procurement and OEM Stakeholders
- Prioritize suppliers with integrated solutions. Evaluate partners that can combine resonators with filtration and ducting to reduce assembly complexity and weight. Integrated offerings can lower total system cost and improve quality control.
- Develop material strategy aligned with application needs. Work with suppliers to match PP and PA materials to specific temperature and performance requirements, optimizing cost without compromising durability or compliance.
- Engage early in regulatory planning. Collaborate with suppliers to anticipate Euro 7 and noise regulation impacts, ensuring that intake system designs are validated well before mandatory implementation dates to avoid production delays.
The air intake resonator market is at a point where steady growth intersects with technological and regulatory change. Stakeholders who align their strategies with material innovation, hybrid demand, and acoustic differentiation will be best positioned to capture value through the forecast period. For deeper segmentation data, regional breakdowns, and customized strategic scenarios, access to comprehensive market intelligence is essential to refine these insights and support precise decision-making.
For detailed analysis of this topic, please visit the official page: Air Intake Resonator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
AGV Charging System Market: Why 8.45% CAGR and Asia Pacific’s Lead Redefine Investment
By pmarketresearch, 2026-09-18
The AGV Charging System Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The automated guided vehicle charging infrastructure market has transitioned from a peripheral consideration to a central component of intralogistics strategy. The sector expanded from roughly 312 million USD in 2020 to an estimated 613 million USD in 2025, with projections indicating a steady trajectory toward just over 1 billion USD by 2032. This growth reflects annualized expansion of 8.45 percent, a pace that outstrips broader industrial automation adoption and signals a structural shift in how facilities approach material handling power management.
Despite the upward trajectory, the market sits at a critical inflection point. Operators are no longer evaluating charging systems as simple utility attachments. Instead, charging infrastructure is becoming a bottleneck or an accelerant for throughput, depending on design choices. Three challenges define the current landscape.
First, downtime economics have intensified. Warehouse and manufacturing environments now operate under tighter labor constraints and higher throughput expectations, making vehicle idle time directly visible in operational cost. Charging solutions that require prolonged dock occupancy or complex manual alignment create hidden capacity losses that compound across fleets. Second, standardization gaps persist across safety, interoperability, and performance metrics. As automated vehicle deployments scale across mixed fleets and multi-vendor environments, facilities encounter integration friction when charging hardware, communication protocols, and docking behaviors are not aligned. Third, the pace of battery chemistry evolution is outstripping charger design cycles. Higher energy densities, faster charge acceptance, and shifting thermal profiles require charging systems that can adapt without forcing full vehicle redesigns.
These challenges are not isolated technical issues. They shape procurement decisions, vendor selection, and facility planning. Companies that treat charging as an afterthought increasingly discover that power delivery constraints limit automation ROI, while early actors are using charging architecture to differentiate operational flexibility.
Strategic Drivers Reshaping the Market
The expansion of AGV charging infrastructure is being pulled by a combination of technology, regulatory pressure, operational behavior, and cost dynamics. Understanding how these forces interact is essential for anticipating where value will concentrate.
Technology Innovation and Performance Thresholds
Charging technology is moving away from static, long-duration docking toward high-efficiency, flexible power delivery. Inductive and contact-based systems are both advancing, but the strategic question is increasingly about when and where energy is transferred. Opportunities for in-process or short-break charging reduce the need for large battery packs and long charging windows. Award recognition for in-process charging technology in early 2025 highlighted how the industry is rewarding solutions that minimize interruption rather than simply improving charger wattage. At the same time, high-voltage DC connectors and microgrid-enabled fast charging concepts have emerged to support next-generation vehicles with reduced downtime.
Battery-side developments reinforce this shift. Lithium-ion adoption continues to benefit from cost and performance improvements, and charging architectures are being optimized for higher charge rates, including transitions from conventional 1C charging toward 3C surge profiles in suitable applications. This changes the design logic for both stationary and onboard charging units, placing greater importance on thermal management, power conversion efficiency, and control software.
Policy Pressure and Compliance-Driven Adoption
Regulatory expectations are reshaping industrial facility planning. European sustainability targets require industrial operations to move toward carbon neutrality by 2050, with a 55 percent emission reduction milestone by 2030. These targets accelerate interest in efficient charging approaches that reduce energy waste and support broader decarbonization strategies. Wireless and opportunity charging solutions gain relevance here because they can lower mechanical wear, simplify integration into continuous workflows, and support more consistent energy use patterns when deployed thoughtfully.
Safety and interoperability standards are equally influential. Conformance to AGV safety requirements drives demand for charging systems that are not only electrically robust but also integrated into the vehicle’s operational safety logic. In warehouse automation, this means charging infrastructure must align with vehicle behavior, zone design, and risk controls rather than functioning as a standalone utility.
Demand-Side Changes in Logistics and Manufacturing
Operational expectations are changing on the demand side. Facilities are deploying larger fleets of automated vehicles and expecting them to support continuous or near-continuous workflows. This is especially visible in warehousing and logistics, where throughput pressure has made charging strategy part of overall slotting, routing, and shift design. Automotive manufacturing and adjacent industrial sectors are also pushing for more flexible power solutions that can accommodate high-utilization vehicles without expanding floor congestion.
Behaviorally, operators are moving from a “charge when parked” mindset to a “charge where and when it fits the process” mindset. That shift increases interest in solutions that support fast top-ups, autonomous docking, and reduced manual intervention. The commercial implication is that charging systems are being evaluated on process compatibility as much as on electrical performance.
Supply Chain and Cost Structure Evolution
Cost dynamics are improving the feasibility of advanced charging solutions, but they are also reshaping supplier competition. Better lithium-ion economics reduce the penalty of higher-performance batteries, which in turn enables more aggressive charging strategies. However, total cost of ownership calculations now include power conversion efficiency, maintenance exposure, and integration labor. Suppliers that can reduce mechanical wear, simplify installation, or support modular scaling gain an advantage because facilities are looking to avoid hidden operational costs.
Supply chain maturity is also affecting time-to-deployment. As charging modules, connectors, and control systems become more standardized in certain segments, integration complexity can decline. Yet in custom intralogistics environments, bespoke engineering remains a significant value driver, especially where high-current delivery, custom docking, or mixed-vehicle environments are involved.
Competitive Dynamics and Differentiated Playbooks
The market features a diverse set of participants spanning specialist charging providers, industrial power companies, and broader automation integrators. Rather than competing on a single dimension, leading players are defining advantage through technology focus, deployment scale, integration depth, and regional footprint.
Wireless inductive specialists have positioned themselves around continuous operation and reduced mechanical wear. Wiferion, for example, has built recognition around inductive systems designed for opportunity charging, with recent industry acknowledgment for in-process charging technology. The strategic appeal is clear: if vehicles can charge without precise mechanical engagement or extended stationary periods, facilities can reduce downtime and maintenance overhead. VAHLE takes a complementary angle with conductive contacts and shuttle charging systems, emphasizing high-current fast charging and custom integration in intralogistics. This reflects a different bet: that robust contact-based infrastructure remains essential where high power, predictability, and integration with existing floor systems matter most.
Other participants compete on scale and ecosystem breadth. Delta Electronics has emphasized a large deployed base across industrial vehicles and AGVs, presenting its charging portfolio as part of a broader mobility and automation offering. This scale narrative matters because it suggests maturity in manufacturing, support, and multi-vehicle compatibility. Micropower Group focuses on high-frequency battery chargers for AGV applications, including onboard and stationary units with support for lithium-ion and opportunity charging, targeting flexibility on both the hardware and application side. EnerSys leans into integrated battery and charging solutions, framing power delivery as part of reliable industrial automation rather than as a standalone hardware category.
In Asia, several firms emphasize precision docking, non-contact power transfer, and system-level integration. Daihen and B&PLUS illustrate the focus on docking and non-contact power supply mechanisms, while Daifuku positions charging within broader material handling automation solutions. Guangdong Titans Intelligent Power highlights autonomous docking and multi-function charging for automated material handling, reflecting an emphasis on customized deployment and functional integration. Vicor Power enters from a different angle with high-efficiency power conversion and charging modules tailored for AGV battery systems, showing how component-level performance can matter as a differentiated layer within broader assemblies.
Recent events illustrate how these positions are being reinforced. Delta Electronics showcased its battery charging portfolio at LogiMAT in early 2026, underscoring the reach of its deployed solutions. Schaltbau advanced high-voltage DC connectors and microgrid concepts for faster charging of next-generation AGVs, pointing toward infrastructure-level enablement beyond individual vehicle charging units. These moves suggest a market that is not only refining vehicle-side charging but also rethinking how power is delivered, distributed, and integrated across facilities.
Looking ahead, the competitive landscape is likely to evolve through both convergence and specialization. Integration-heavy players may absorb more charging functionality into automation platforms, while specialist suppliers may deepen advantage in wireless efficiency, high-current contact systems, or docking precision. New entrants can still compete by targeting specific pain points such as autonomous docking reliability, modular scalability, or plug-and-play interoperability. The most important strategic question is whether a supplier competes as a component vendor, a system enabler, or a process-integrated solution provider.
PW Consulting Automotive & Machinery Research Center
Outlook: Key Trends Over the Next Three to Five Years
The next phase of market development will likely be defined by how charging systems fit into broader operational design rather than by simple capacity increases. Several trends stand out.
One major direction is the rise of charging as an integral workflow element. Facilities will increasingly design routes, staging areas, and vehicle Utilization patterns around short charging windows and opportunity charging points. This creates demand for systems that support autonomous alignment, fast energy transfer, and dependable docking behavior. The commercial opportunity lies in solutions that reduce the operational friction of charging rather than only improving raw power output.
Worldwide Mobile Charging Robot for Electric Vehicle Market
A second trend is the continued blending of contact and wireless approaches. Different applications will favor different methods, but many environments will need hybrid strategies. High-utilization vehicles may benefit from inductive top-ups in flow paths, while fixed docking points may use contact systems for rapid high-power replenishment. Suppliers that can offer interoperable architectures or clearly defined application-specific playbooks will be better positioned than those pushing a single technology in all contexts.
A third trend is infrastructure-level thinking. As charging demand grows, facilities will pay more attention to power distribution, microgrid integration, and centralized energy management. This shifts some value from pure vehicle-side hardware to broader electrical architecture and control software. Companies that can connect charging performance with facility-level energy planning will have an opening to become strategic partners rather than equipment suppliers.
These trends are not without risk. Standardization may lag behind deployment, creating fragmentation and integration cost. Overly aggressive charge-rate expectations could introduce thermal or battery-life constraints if not matched with robust system design. Demand may also vary by region and sector, making broad generalizations risky. The opportunity is strongest where charging strategy is aligned with actual process requirements, fleet composition, and total cost of ownership rather than treated as a one-size-fits-all upgrade.
Strategic Actions for Decision-Makers
For AGV manufacturers and automation integrators, the priority is to treat charging as part of the vehicle and workflow architecture, not as a bolt-on accessory. Design choices around battery size, docking tolerance, charge acceptance, and safety integration will influence customer throughput and maintenance costs. Suppliers that can demonstrate measurable reductions in downtime, simpler installation, or cleaner integration with mixed fleets will differentiate more effectively than those competing only on hardware specifications.
Worldwide Automatic Guided Vehicle Sensing System Market
For investors and corporate strategy teams, the most valuable exposure may come from companies that combine technical differentiation with deployment scalability. Wireless efficiency, high-current contact reliability, power conversion performance, and integration-ready software are all potential value drivers, but the key is whether those capabilities translate into repeatable deployments and lower integration risk. Monitoring how suppliers expand from component or system roles into broader facility-level solutions can provide early signals of competitive momentum.
For procurement and operations leaders, charging decisions should be evaluated against process impact. The right solution depends on vehicle utilization patterns, shift structure, floor layout, and tolerance for manual intervention. Opportunities to reduce idle time, simplify docking, or support opportunity charging in active flow paths can create operational benefits that outweigh raw hardware comparisons. Detailed segment-level data, application-specific benchmarks, and vendor-by-vendor capability mapping can materially improve procurement decisions and reduce implementation risk. For teams planning multi-phase automation rollouts, deeper research into charging architecture options, regional supplier dynamics, and total cost of ownership scenarios can help convert a technical choice into a strategic advantage.
For detailed analysis of this topic, please visit the official page: AGV Charging System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fast Electric Rolling Door Market: How 7.85% CAGR and Shifts Reshape Strategy Through 2032
By pmarketresearch, 2026-09-18
The Fast Electric Rolling Door Market: Strategic Trends and Commercial Opportunities (2025–2032)
Market Landscape and Core Challenges
The fast electric rolling door market has evolved into a critical infrastructure segment for industrial, commercial, and logistics operations worldwide. Valued at approximately 712.6 million in 2025, the market is projected to reach 1.2 billion by 2032, expanding at a compound annual growth rate of 7.85 percent over the forecast period. This trajectory reflects more than steady replacement cycles; it signals a structural shift in how facilities manage energy, throughput, and environmental controls. The base year of 2025 captures a market that has already absorbed several years of accelerated demand, with historical growth from 2020 through 2025 demonstrating consistent upward momentum across multiple end-use sectors and geographies.
Beneath the headline figures, three interconnected challenges are reshaping how manufacturers, distributors, and end-users approach this market. First, raw material volatility has become a persistent margin pressure. Steel and aluminum pricing swings, compounded by trade policy adjustments in recent years, are creating unpredictable input costs and forcing suppliers to reconsider pricing structures, inventory strategies, and product mix. Second, energy efficiency expectations are no longer optional specifications. Federal building energy standards and revised incentive frameworks are pushing facility operators to prioritize doors that reduce air exchange, limit thermal loss, and integrate more tightly with broader building management systems. This shifts procurement discussions from simple durability and cycle speed toward total cost of ownership and compliance alignment.
Third, the market is navigating a quality-versus-speed tension that affects both product design and adoption curves. Operators in high-traffic environments demand faster cycle times, improved impact resistance, and reliable automated refeed functionality, yet these performance enhancements often require more sophisticated control electronics, reinforced components, and tighter manufacturing tolerances. Suppliers that can balance rapid deployment with long-term reliability are gaining traction, while those competing primarily on price are facing margin compression and higher warranty exposure. Together, these challenges define a market that is maturing quickly but still offers meaningful differentiation for players that can align product architecture, cost discipline, and regulatory awareness.
Key Demand Drivers Reshaping the Segment
Technology Innovation and Performance Expectations
Product innovation remains one of the most direct catalysts for market expansion. High-speed door manufacturers are increasingly launching tiered product families that balance premium performance with cost-sensitive configurations. Recent releases have emphasized enhanced customization, modular control options, and variants designed for distinct industrial environments, allowing buyers to match door specifications more precisely to application requirements. At the same time, advances in fabric-based rolling systems, rigid slat designs, and composite constructions are broadening the range of operating conditions these doors can support. The practical effect is not just faster doors, but doors that integrate more cleanly into modern facility workflows, reduce downtime during maintenance, and maintain performance in aggressive environments such as cold storage and high-traffic loading areas.
High Speed Doors Market
Policy and Regulatory Environment
Regulatory and incentive mechanisms are becoming powerful levers in procurement decisions. Federal building energy efficiency standards are pushing commercial and industrial facilities to reduce on-site energy consumption, which directly increases the value of doors that minimize conditioned air loss during frequent openings. At the same time, incentive programs tied to certified efficient exterior doors have improved the financial case for upgrades, particularly for organizations planning phased facility modernization. These dynamics are not simply compliance issues; they are reshaping specification criteria. Facility managers and engineers increasingly evaluate door selections through an energy-performance lens, weighing cycle speed, sealing behavior, and integration potential alongside traditional factors like durability and footprint.
Demand-Side Shifts in Warehousing, Cold Chain, and Manufacturing
End-use demand is being driven by operational intensity rather than incremental replacement alone. Warehouse and logistics facilities continue to prioritize throughput, requiring door systems that support frequent, automated passage while controlling environmental drift. Food processing and cold storage operators face even stricter temperature retention requirements, making fast cycle times and reliable sealing critical to product integrity and energy costs. Automotive and general manufacturing environments add another layer of demand, where impact resistance, safety performance, and integration with material-handling workflows matter as much as speed. As these sectors expand or modernize, the door becomes less of a passive barrier and more of an active component in facility efficiency, which broadens the addressable market and raises the performance baseline for competitive products.
Automatic Door Market
Supply Chain and Cost Structure Dynamics
Cost structure pressures are reshaping supplier strategies across the value chain. Fluctuations in steel pricing, along with periodic trade measures affecting steel and aluminum inputs, have translated into meaningful installation-level price variability depending on material composition. These conditions reward manufacturers that can optimize material usage, offer alternative constructions where appropriate, and maintain flexible production planning. They also encourage greater attention to regional production footprints and supply continuity. Recent expansion activity in select markets, including localized production moves in Southeast Asia, reflects an effort to reduce exposure to logistics delays, currency risk, and input cost uncertainty. For buyers, this environment means that lead times, warranty terms, and service availability are becoming just as important as unit price in evaluating long-term value.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of specialized high-speed door manufacturers, broader rolling-door producers, and regional players with strong compliance or installation capabilities. Market concentration remains moderate, with the top three and top five firms holding meaningful but not dominant shares, indicating room for continued differentiation and selective consolidation. Leading participants generally compete on a combination of speed, durability, automation features, and application-specific engineering rather than on commodity pricing alone. This positions the market as one where product architecture, control technology, and service networks often determine share gains more than volume alone.
Several strategic profiles stand out. Some manufacturers emphasize high-performance fabric and rigid overhead systems designed for industrial, cold storage, and commercial environments, building reputation on large installed bases and repeatable reliability. Others focus on high-speed roll-up and fabric door lines that target logistics and facility applications where throughput and ease of operation are paramount. European manufacturers have often leaned into advanced control technology, spiral and vertically opening high-speed designs, and refined engineering for demanding industrial use. In parallel, U.S.-based producers have expanded product lines that highlight energy efficiency, impact resistance, and automated refeed capabilities for warehouses and loading docks. Traditional steel door manufacturers and service-door specialists remain relevant in applications where security, heavy-duty use, and code compliance carry significant weight. Meanwhile, regional fabricators with hurricane-zone or local code expertise maintain strong positioning in jurisdictions where compliance and installation know-how are decisive buying factors.
Recent company actions illustrate how these strategies are evolving. Tiered product launches are giving buyers more granular choices across premium, eco, and basic configurations, supporting customization without forcing a one-size-fits-all approach. Updates to existing high-performance lines have reinforced the importance of energy efficiency and impact resistance for commercial facilities. Selective geographic expansion, including regional acquisitions to strengthen local production, indicates a growing emphasis on supply resilience and proximity to end markets. New high-performance steel door introductions with improved opening speeds also show that speed remains a competitive battleground even in more traditional product categories.
The broader market evolution appears to be moving along two tracks simultaneously. On one hand, integration is likely to continue as larger players seek to strengthen regional presence, acquire niche capabilities, or broaden application coverage. On the other hand, segmentation will remain important because requirements differ sharply across cold storage, logistics, manufacturing, and specialty code-driven environments. New entrants face a realistic bar: success typically depends on solving a clear operational pain point, such as cycle speed with robust refeed behavior, improved thermal performance, or compliance-ready designs for specific regions. Companies that can pair product performance with reliable service, clear specification support, and cost-stable material strategies are best positioned to convert market growth into durable share.
Forward-Looking Trends for the Next Three to Five Years
Several trends are likely to shape the market through the late 2020s and early 2030s. The first is deeper integration of door performance with building energy strategy. As efficiency expectations become embedded in procurement specifications and incentive structures, fast electric rolling doors will increasingly be evaluated as part of a facility’s overall energy and environmental control system rather than as standalone hardware. That shift opens opportunities for manufacturers and solution providers that can demonstrate measurable gains in air exchange reduction, thermal retention, and operational consistency.
The second trend is continued product stratification. Buyers will likely demand more clearly differentiated options between premium high-speed systems, cost-efficient standard configurations, and application-tailored variants for cold storage, high-impact zones, or specialized code environments. Suppliers that can manage this stratification efficiently, without sacrificing quality or service reliability, will be better placed to capture both performance-driven and price-sensitive demand.
The third trend is supply-side localization and cost resilience. Input cost volatility and trade dynamics will keep pressure on margins, encouraging more regional production, diversified sourcing, and product designs that reduce material exposure where possible. At the same time, service coverage and uptime assurance will become stronger differentiators, especially in markets where facility downtime carries high operational cost. The main uncertainty lies in the pace and direction of regulatory incentives, material pricing, and adoption speed in newer geographic markets. Organizations that rely on a single product narrative or a narrow pricing strategy may find it harder to adapt if incentive frameworks shift or if input costs reaccelerate.
Strategic Actions for Decision Makers
Manufacturers and product developers should prioritize clear performance tiers, energy-aligned specifications, and service reliability as core commercial levers. Differentiating through measurable efficiency benefits, cycle consistency, and application-specific engineering can help protect margins in an environment where raw material and trade conditions remain variable. It is equally important to treat installation support, parts availability, and maintenance workflows as competitive assets rather than back-office functions.
Investors and corporate strategy teams should pay close attention to companies that combine technology differentiation with resilient supply strategies and credible regional reach. Opportunities are likely to emerge where providers can demonstrate integrated value across hardware, controls, and service, especially in logistics, cold storage, and energy-conscious facility upgrades. Monitoring consolidation activity, localized production moves, and product launches that address both speed and efficiency will help identify where competitive advantage is being built.
PW Consulting Automotive & Machinery Research Center
Procurement leaders and facility operators should evaluate fast electric rolling door purchases with a longer time horizon, weighing total operating cost, energy performance, downtime risk, and compliance alignment alongside initial price. Specification clarity matters: matching door type and control configuration to actual traffic patterns and environmental requirements can reduce operational losses and improve return on investment over the asset life.
For organizations that need deeper segmentation detail, regional granularity, company-level benchmarks, and tailored sourcing or expansion scenarios, a dedicated market research report can provide the structured data and scenario analysis needed to support precise decisions. Access to more detailed breakdowns can help translate these broad trends into actionable plans with clearer assumptions and better risk control.
For detailed analysis of this topic, please visit the official page: Fast Electric Rolling Door Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Snowblower Market Trends: Why Two-Stage Models and North America Reshape Growth by 2032
By pmarketresearch, 2026-09-18
Navigating the Snowblower Market: Strategic Trends and Commercial Opportunities (2026-2032)
Market Overview and Core Challenges
The global snowblower market has demonstrated steady growth over the past five years, expanding from approximately $10.82 billion in 2020 to an estimated $12.61 billion in 2025. This trajectory reflects consistent demand drivers tied to winter preparedness, residential infrastructure expansion, and commercial facility management. Looking ahead to 2032, the market is projected to reach $15.61 billion, representing a compound annual growth rate of 3.1 percent. While the growth rate suggests maturity rather than explosive expansion, the underlying dynamics reveal significant shifts in how snow removal equipment is developed, distributed, and utilized.
Revenue distribution across regions highlights a clear concentration pattern. North America accounts for the largest share of global sales, reflecting the region's climate profile, established consumer base, and mature distribution networks. Europe follows as the second-largest market, driven by consistent winter conditions and a growing emphasis on commercial snow management solutions. Asia Pacific, Latin America, and the Middle East and Africa collectively represent smaller but emerging opportunities, where infrastructure development and variable winter patterns create niche demand segments.
Within the product landscape, two-stage snow blowers dominate the market, valued at over $7.08 billion, reflecting their versatility and effectiveness for moderate to heavy snow conditions. Single-stage models, valued at approximately $4.01 billion, serve lighter snowfall regions and residential applications where ease of use and lower cost take priority. Three-stage units, valued at around $1.51 billion, capture a specialized segment focused on extreme conditions and professional-grade performance. Application-wise, the residential segment leads with approximately $7.43 billion in revenue, while commercial applications contribute roughly $5.18 billion, indicating strong demand from property management firms, municipal operations, and facility maintenance providers.
Several challenges are reshaping how companies approach strategy in this market. First, the supply chain environment has become increasingly volatile. Raw material costs, particularly for steel and aluminum, have been influenced by tariff policies and global supply fluctuations. In early 2026, U.S. hot-rolled coil steel prices ranged from $935 to $965 per ton, driven in part by tariffs affecting snow blower manufacturing costs. The continued imposition of Section 232 tariffs on steel and aluminum imports at 25 percent has further complicated sourcing for manufacturers reliant on imported components. Global steel supply chain dynamics show apparent steel consumption projected to recover by 3.1 percent in 2026 following prior declines, but this recovery introduces pricing uncertainty that manufacturers must carefully manage.
Second, regulatory and safety scrutiny has intensified. Product safety incidents have prompted recalls and heightened attention to design integrity. For instance, Ariens recalled Deluxe, Platinum, and Professional series snow throwers due to impeller and auger assembly continuing to rotate after control lever release, as documented by the U.S. Consumer Product Safety Commission in early 2025. This event underscores the importance of robust engineering and quality assurance processes, particularly for companies competing on performance and durability.
Third, the market is experiencing a technology transition as battery-electric alternatives gain traction. While traditional gas-powered models continue to lead in many segments, the introduction of cordless and low-emission options is reshaping consumer expectations and forcing incumbents to invest in powertrain diversification. Companies must balance the performance advantages of internal combustion engines with the environmental and operational benefits of electric platforms, all while managing cost structures and consumer education.
For decision-makers, these dynamics signal a market where growth is no longer solely about volume expansion. Strategic positioning requires attention to cost resilience, product safety, and adaptation to evolving powertrain preferences. Companies that can navigate these pressures while delivering reliable, differentiated solutions will be best positioned to capture value in the coming years.
Key Drivers Shaping the Market
Technological Innovation and Performance Differentiation
The snowblower market is undergoing a period of meaningful technological evolution. Manufacturers are investing in engine optimization, clearing technology improvements, and user-centric design features that enhance performance across diverse snow conditions. Ariens introduced 2026 Platinum series updates with enhanced 389cc engines designed for heavy snow conditions, demonstrating how incremental engineering advancements can reinforce market leadership in the two-stage segment. Similarly, Toro released a 2025-2026 lineup including 60V MAX Power Max e26 two-stage battery snow blower models, signaling a strategic push toward electric platforms that combine performance with reduced noise and emissions.
Beyond powertrain shifts, three-stage clearing technology has emerged as a differentiator for heavy-duty applications. This configuration, which incorporates an accelerator in addition to the auger and impeller, addresses scenarios where rapid snow displacement is critical. Cub Cadet's 3X series and Troy-Bilt's Storm series have both emphasized three-stage options, illustrating how brands are using advanced clearing architectures to appeal to users who face frequent, intense snowfall. These advancements are not merely incremental; they reflect a broader industry trend toward segment-specific engineering, where product design aligns closely with regional climate profiles and usage intensity.
For manufacturers, the implication is clear: competitive advantage increasingly depends on delivering measurable performance improvements that resonate with specific user needs. Companies that invest in R&D focused on engine reliability, clearing efficiency, and ease of operation can command premium positioning and foster brand loyalty in a market where replacement cycles create recurring demand opportunities.
Policy and Regulatory Environment
Regulatory developments continue to shape cost structures and product strategy. The persistence of U.S. Section 232 tariffs on steel and aluminum imports at 25 percent in 2026 has direct implications for snow blower manufacturing, as these materials are fundamental to chassis construction, auger systems, and impeller assemblies. Imported components and raw materials face higher costs, prompting manufacturers to evaluate sourcing strategies, domestic production adjustments, and pricing models.
Fully Automatic Snow Blower Market
At the same time, safety regulations and consumer protection oversight are becoming more rigorous. Recalls and incident reporting highlight the need for proactive compliance and design validation. The Ariens recall exemplifies how mechanical failure modes can trigger regulatory action and reputational risk, reinforcing the importance of thorough testing protocols and quality control across production lines.
Policy uncertainty also extends to environmental expectations. While no sweeping regulatory mandate currently dictates powertrain transitions in snow removal equipment, shifting consumer sentiment and local emissions considerations are influencing purchasing behavior. Manufacturers that anticipate these trends by developing lower-emission options and communicating environmental benefits can position themselves ahead of potential regulation while appealing to eco-conscious buyers.
Demand-Side Changes in Consumer and Commercial Behavior
Demand patterns are evolving as end users reassess their snow removal priorities. In the residential segment, homeowners are increasingly seeking equipment that balances power, ease of use, and operational cleanliness. Battery-powered snow blowers, such as those offered by EGO Power+ and Greenworks, address concerns around noise, emissions, and maintenance while providing sufficient clearing capability for typical residential snowfall. These products appeal particularly to users in suburban areas where garage space, storage, and proximity to neighbors make quieter, cordless operation desirable.
On the commercial side, facilities management teams and municipal operators are prioritizing reliability and throughput. Snow Joe and similar affordable electric and battery options target lighter residential removal, while commercial-focused users look for durability and clearing speed. The broader trend indicates a bifurcation in demand: lighter-duty, user-friendly products for homeowners and more robust, high-performance systems for businesses that cannot afford clearing downtime.
Weather variability also influences purchasing timing and volume. Regions experiencing heavier or more unpredictable winter patterns tend to see stronger equipment demand, while milder winters can temporarily suppress replacement cycles. This volatility encourages manufacturers to maintain flexible production planning and regional marketing strategies that align with localized climate expectations.
Supply Chain and Cost Structure Evolution
Cost pressures from raw materials and trade policy are reshaping margin expectations. Steel price fluctuations, tariffs on imported inputs, and global supply chain adjustments have forced manufacturers to examine component sourcing, inventory management, and pricing strategies more closely. The projected 3.1 percent recovery in global steel consumption in 2026 suggests improving availability, but price stability remains uncertain.
Manufacturers are responding by diversifying supplier bases, evaluating domestic production options, and exploring design efficiencies that reduce material intensity without compromising durability. Battery-electric models also introduce a different cost structure, shifting expense from fuel and maintenance toward battery technology and electronic components. Over time, as battery costs evolve and production scales, the economics of electric snow blowers may improve, expanding their viability beyond niche applications.
For industry participants, supply chain resilience has become a strategic priority. Companies that can manage input cost volatility, maintain production continuity, and adapt pricing to preserve value perception will be better equipped to sustain margins in a fluctuating cost environment.
Competitive Landscape and Leading Strategies
The market features a mix of established manufacturers, brand portfolios under larger industrial groups, and emerging electric-focused entrants. Ariens stands out for its focus on two-stage snow blowers with Deluxe, Platinum, and Professional series targeting heavy-duty residential and commercial snow removal. Its recent product updates and engine enhancements reflect a strategy centered on performance credibility and segment specialization. Toro Company complements this approach with a broad portfolio spanning gas and battery-powered models, including Power Max and Power Clear series, enabling it to serve both traditional and transitioning customer preferences.
Honda Power Equipment maintains a premium positioning known for reliability, with HSS series two-stage models leveraging Honda engines optimized for performance and ease of use. This reputation for durability supports a higher price point and appeals to users who prioritize long-term value. Cub Cadet and Troy-Bilt, both part of the MTD Products network, offer distinct brand positioning: Cub Cadet emphasizes power steering and three-stage clearing technology through its 2X and 3X series, while Troy-Bilt focuses on affordable, high-performance two and three-stage options via its Storm series. This parent-company strategy of managing multiple brands allows coverage across price points and feature sets without internal cannibalization.
Husqvarna and John Deere both integrate snow blowers into broader outdoor power equipment lineups, leveraging brand trust and cross-category customer relationships. Craftsman provides single, two, and three-stage models distributed through major retail channels like Lowe's, capitalizing on widespread retail access and brand recognition. EGO Power+ and Greenworks represent the electric-focused cohort, specializing in battery-powered and corded electric solutions that emphasize quiet, emission-free operation for residential applications. Snow Joe and RYOBI target affordability and accessibility, with Snow Joe known for lighter residential electric and battery throwers and RYOBI offering battery and gas options sold primarily through Home Depot. KOVACO adds European manufacturing presence with compact and professional snow blowers, reflecting localized product strategies in regional markets. Simplicity, also MTD-affiliated, reinforces the durability-focused homeowner segment.
Several strategic patterns emerge from this landscape. First, brand portfolios and multi-tier offerings enable companies to address diverse customer segments while maintaining operational efficiencies. Second, electric powertrain development is becoming a competitive differentiator, with incumbents expanding battery lines and specialized entrants building credibility around cordless performance. Third, product safety and quality assurance are increasingly visible elements of brand reputation, as recalls and regulatory scrutiny can influence consumer trust and retailer relationships.
The competitive environment is evolving through both consolidation and fragmentation. Larger industrial groups continue to manage multiple brands, creating economies of scale in manufacturing and distribution while preserving distinct brand identities. At the same time, the rise of electric solutions and specialized clearing technologies opens space for focused entrants that can innovate quickly in specific niches. Trade show participation, such as RPM Tech exhibiting the PB-2000 snow blower at the Atlantic Heavy Equipment Show to showcase municipal and airport clearing capabilities, illustrates how new and expanding players are targeting specialized commercial applications beyond traditional residential markets.
Worldwide Hand Held Blower Market
For market participants, the key question is not simply who leads today, but which companies can adapt product architectures, supply chains, and brand messaging to align with shifting consumer expectations and cost realities. Differentiation will increasingly depend on performance consistency, powertrain flexibility, and the ability to communicate value in ways that resonate with both traditional and new user priorities.
Future Trends and Strategic Implications
Looking ahead to the 2026-2032 period, several trends are likely to shape market evolution. The first is the continued expansion of battery-electric options across residential and light commercial segments. As battery technology improves and production scales, cordless snow blowers will become more capable of handling moderate to heavy snowfall, broadening their addressable market. Manufacturers that develop reliable electric platforms and educate consumers on performance realities will capture early-mover advantage in an transitioning segment. However, this trend carries uncertainty around battery cost trajectories, charging infrastructure expectations, and consumer willingness to adopt cordless solutions for heavy-duty use.
The second trend is increasing focus on segment-specific engineering and application alignment. As climate variability and regional snowfall patterns influence purchasing decisions, companies will likely invest further in product configurations tailored to distinct use cases. This includes three-stage systems for extreme conditions, compact electric units for suburban homeowners, and commercial-grade equipment for municipal and facility operations. The strategic opportunity lies in matching product portfolios to regional demand profiles and avoiding one-size-fits-all positioning that may dilute brand relevance.
The third trend involves supply chain and cost management as persistent competitive factors. Tariffs, steel price volatility, and global material flows will continue to influence manufacturing economics. Companies that diversify sourcing, optimize material usage, and maintain pricing flexibility will protect margins more effectively than those dependent on single supply routes or rigid cost structures. At the same time, any relaxation or reconfiguration of trade policy could shift cost dynamics quickly, requiring agile planning and scenario readiness.
These trends create commercial opportunities for manufacturers that can balance innovation with operational resilience, for investors seeking exposure to brands that demonstrate adaptability across powertrain transitions, and for procurement teams that benefit from understanding which suppliers are best positioned to deliver consistent quality amid cost volatility. The primary risk is complacency in the face of technological and regulatory shifts; companies that treat the market as static may lose ground to competitors who anticipate changing user expectations and cost environments.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to strengthen product differentiation through targeted engineering and powertrain diversification. Investing in engine reliability, clearing technology, and electric platform development can reinforce market position across segments. Equally important is proactive quality assurance and compliance to mitigate safety-related disruptions that can affect brand trust and retail relationships. Companies should also evaluate supply chain flexibility, including multi-source sourcing and material optimization, to manage cost volatility without sacrificing product durability.
For investors, the strategic focus should be on companies that demonstrate adaptability across traditional and electric product lines, maintain strong brand equity in core regions, and exhibit disciplined cost management. Brands with multi-tier portfolios and clear segment positioning may offer more resilient growth profiles in a market where demand is bifurcating between lightweight residential solutions and heavy-duty commercial systems. Monitoring trade policy developments and raw material trends can also help anticipate shifts in manufacturer margins and pricing strategies.
PW Consulting Automotive & Machinery Research Center
For procurement and purchasing leaders, understanding supplier positioning and product architecture differences can inform sourcing decisions for residential, facility, or municipal applications. Evaluating manufacturers based on engineering depth, safety track records, and powertrain options enables more informed selection aligned with operational requirements and environmental preferences. Building relationships with suppliers that demonstrate supply chain resilience and consistent quality can reduce disruption risk during peak demand periods.
Detailed segmentation data, cost structure analysis, and customized strategic guidance can provide deeper clarity for organizations making specific investment or sourcing decisions. A complete research report offers granular breakdowns across regions, product types, and applications, along with forward-looking scenarios that support more precise planning.
For detailed analysis of this topic, please visit the official page: Snowblower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Stern Drive Boat Propeller Market: Why 6.7% CAGR Reshapes the $3.57B Outlook to 2032
By pmarketresearch, 2026-09-18
Stern Drive Boat Propeller Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The stern drive boat propeller market has demonstrated resilient expansion over the past half-decade, reaching an estimated valuation of USD 3,567.0 million in 2025. Historical data from 2020 through 2025 indicates a compound annual growth rate of 6.7 percent, positioning the sector on a solid trajectory toward USD 5,616.39 million by 2032. This growth reflects steady demand across recreational and commercial marine segments, alongside incremental technological upgrades that enable vessels to achieve better fuel efficiency and maneuverability. As marine propulsion systems evolve, the propeller component remains a critical interface between engine performance and hydrodynamic efficiency, making it a focal point for manufacturers and buyers alike.
Despite the favorable overarching trajectory, the industry faces several structural challenges that demand strategic attention. First, material cost volatility introduces pronounced uncertainty into pricing and margin forecasting. Raw material markets, particularly nickel-based alloys used in corrosion-resistant propeller designs, have experienced notable price swings between 2024 and 2025. Such fluctuations compress profitability for manufacturers operating on fixed-price contracts while simultaneously pressuring downstream buyers who seek predictable procurement costs. Second, the market exhibits moderate concentration, with the top three firms accounting for approximately 38.5 percent of total revenue and the top five controlling roughly 52.8 percent. This landscape creates both competitive stability and barriers for emerging players, particularly when established incumbents leverage decades of OEM relationships, proprietary hub architectures, and extensive aftermarket distribution networks. Third, the shift toward electrified and hybrid marine propulsion systems is gradually reshaping performance requirements. Traditional stern drive configurations must adapt to new torque curves, weight constraints, and acoustic expectations, compelling propeller designers to reconsider blade geometry, cavitation behavior, and integration standards.
For strategic decision-makers, these dynamics suggest that market participation requires more than scale alone. Success increasingly depends on material sourcing agility, technical differentiation, and the ability to align product portfolios with evolving vessel architectures. Organizations that anticipate these shifts rather than react to them are better positioned to capture share in both OEM channel development and aftermarket replacement cycles.
The intersection of growth momentum and structural complexity defines the current operating environment. Market participants must balance near-term revenue opportunities against longer-term technology transitions, while navigating cost pressures that affect both production economics and end-customer affordability. Understanding these forces is essential for prioritizing capital allocation, partnership strategies, and product roadmaps.
Key Drivers of Market Evolution
Three interconnected forces are shaping the directional path of the stern drive propeller market: material innovation, regulatory and environmental expectations, and shifting demand-side behavior in both recreational and commercial marine segments. Each driver carries distinct implications for product design, supply chain planning, and competitive positioning.
Material Innovation and Performance Optimization
Material selection continues to influence durability, weight, and operational efficiency across stern drive propeller applications. Aluminum and stainless steel formulations remain dominant in the market, with aluminum propellers representing the largest material category by revenue and stainless steel offering enhanced wear resistance for higher-performance applications. Alongside these mainstream materials, advanced nickel-aluminum bronze and specialty alloys retain importance for applications demanding superior corrosion resistance in saltwater environments. The breadth of material options allows manufacturers to tailor offerings to specific duty cycles, vessel weights, and propulsion loads.
Recent product activity underscores the strategic importance of material engineering and blade configuration. Michigan Wheel has reinforced its focus on core North American segments following the strategic divestiture of its United Kingdom operations to Nakashima Propeller, sharpening its attention on aluminum and stainless steel profiles compatible with major sterndrive platforms. This realignment reflects a broader pattern in which manufacturers concentrate resources on markets where OEM integration and aftermarket demand provide the strongest return on engineering investment. Meanwhile, Solas has emphasized renewed product visibility around both outboard and sterndrive propeller lines, signaling continued investment in material-grade differentiation and hub system compatibility such as RUBEX configurations.
From a commercial perspective, material-driven innovation affects more than technical specifications. It influences lead times, inventory planning, and dealer-level service capabilities. Manufacturers that stabilize alloy sourcing while offering clearly differentiated performance tiers can better manage cost volatility and present compelling upgrade paths to boat builders and fleet operators.
Regulatory and Environmental Pressures
Marine environmental standards and emissions expectations are gradually influencing propulsion system design, which in turn affects propeller engineering. While stern drive systems are not subject to the same regulatory intensity as automotive powertrains, broader maritime efficiency goals and local water-quality initiatives contribute to a performance mindset that favors reduced fuel consumption, lower vibration, and improved hydrodynamic behavior. These priorities encourage propeller designs that maximize thrust efficiency without increasing engine strain.
The regulatory environment also interacts with material choices. Corrosion resistance, service life, and recyclability are increasingly considered in procurement decisions for commercial fleets and high-use recreational vessels. Operators seek components that reduce downtime and maintenance exposure, particularly in regions where seasonal usage compresses available operating windows. Consequently, product longevity and reliability have become important selling points alongside raw performance metrics.
Demand-Side Shifts in Recreational and Commercial Segments
Recreational boating remains the largest application segment in the market, reflecting sustained consumer interest in leisure marine activities and aftermarket replacement cycles. Buyer behavior in this segment increasingly favors performance upgrades, easier installation compatibility, and visually distinctive blade profiles that align with customized boat configurations. At the same time, commercial operators prioritize durability, predictable maintenance intervals, and compatibility with existing drive families, especially where fleet standardization reduces training and parts complexity.
Within this demand landscape, product specialization is gaining traction. Sharrow Marine has extended testing and rollout activity for its looped propeller designs, including configurations intended for dual-prop sterndrive setups used with major drive platforms. This approach illustrates a broader trend: rather than competing solely on material grade, some manufacturers are pursuing aerodynamic and hydrodynamic geometry as a source of differentiation. The commercial relevance lies in the potential for improved efficiency and reduced vibration, which can appeal to both performance-oriented recreational buyers and commercial users seeking operational savings over long service intervals.
Supply Chain and Cost Structure Dynamics
Supply chain stability remains a defining concern for propeller manufacturers and downstream buyers. Fluctuations in key input costs, particularly for nickel-bearing alloys, have periodically reshaped pricing strategies and margin planning. Between 2024 and 2025, nickel-related pricing moved within a wide band, creating variable cost conditions for manufacturers producing corrosion-resistant propeller lines. This environment rewards companies with diversified sourcing strategies, forward procurement arrangements, and flexible production scheduling.
Cost structure pressures also influence the balance between standardized and customized offerings. High-volume standardized propeller families support efficient production and broader aftermarket availability, while specialized blade geometries and hub systems require more focused engineering and lower-volume runs. Companies that can maintain efficient core production while selectively introducing differentiated variants are better equipped to serve mixed demand without sacrificing margin integrity.
Competitive Landscape and Leading Strategies
The competitive environment in the stern drive propeller market is characterized by a blend of OEM-aligned suppliers, independent performance specialists, and integrated drive system manufacturers. The presence of both established marine propulsion names and focused propeller innovators creates a multifaceted landscape where differentiation can emerge from material technology, compatibility breadth, brand trust, or structural design innovation.
Strategic Positioning Among Key Players
Michigan Wheel occupies a prominent position through its extensive aluminum and stainless steel portfolio designed for sterndrive applications and its strong compatibility with widely used drive platforms. Its recent strategic decision to divest UK operations reflects a deliberate concentration on core market segments where distribution reach and aftermarket support provide durable advantage. By prioritizing compatibility and breadth of blade options, the company reinforces its role as a practical partner for both OEM integration and replacement demand.
Sharrow Marine differentiates itself through patented looped propeller technology and an emphasis on efficiency-oriented performance. Its continued expansion into dual-prop sterndrive configurations indicates a strategy centered on product architecture rather than commodity material competition. For buyers evaluating efficiency gains and refined handling characteristics, this positioning offers a distinct value proposition that complements traditional product categories.
Solas maintains a broad manufacturing footprint and strong compatibility across multiple sterndrive engine families, supported by hub technologies such as RUBEX systems. Its recent product display activity highlights ongoing attention to both outboard and sterndrive propeller lines, reinforcing its ability to serve multi-platform demand. Volvo Penta and Mercury Marine, as major OEM players, leverage their integrated system expertise to offer propellers that align closely with dedicated drive architectures, including counter-rotating and multiple blade configurations optimized for their respective units. This OEM alignment provides a strong baseline for compatibility trust, particularly among buyers seeking seamless system performance.
Marine Propeller Market
Several independent manufacturers, including Turning Point Propellers, PowerTech Propellers, Konrad Marine, and Hill Marine, add further diversity to the market. Their focus areas range from high-quality aluminum and stainless steel profiles to performance stainless steel designs and heavy-duty commercial applications. This breadth allows buyers to select from a range of price-performance points, while also creating opportunities for specialized distributors and service networks.
Market Structure and Evolution Trends
The market remains moderately consolidated, but it is not static. Consolidation pressures may continue in areas where scale, OEM access, and global distribution confer durable advantages. At the same time, product innovation and niche application focus create room for differentiation even in a concentrated environment. The most notable evolution is the increasing importance of technology-led positioning: companies are competing not only on material and compatibility, but also on blade geometry, vibration reduction, and application-specific tuning.
Another emerging trend is the interplay between OEM channels and independent aftermarket demand. While OEM relationships provide volume stability, aftermarket replacement and performance upgrades can offer higher margin opportunities and faster product iteration cycles. Manufacturers that manage both channels effectively are able to balance predictable volume with selective premium offerings. This dual-channel capability is increasingly important as recreational boat owners seek upgrade paths and commercial operators evaluate lifecycle cost rather than initial purchase price alone.
Geographic dynamics also matter, though competitive advantage is often determined less by regional volume leadership than by proximity to major boat-building clusters, service infrastructure, and drive-platform ecosystems. Firms with strong operational presence in key North American and European marine markets benefit from shorter feedback loops with boat builders and faster response to regional product preferences. Meanwhile, manufacturers with multi-region production and distribution capabilities can better manage supply continuity and currency exposure in a volatile input-cost environment.
PW Consulting Automotive & Machinery Research Center
For commercial strategists, the key question is not simply who holds the largest share today, but which companies can sustain differentiation through product engineering, channel flexibility, and cost control. Competitive success will likely favor organizations that can align proprietary design advantages with reliable supply execution and clear compatibility messaging.
Forward-Looking Trends and Commercial Implications
Looking ahead across the 2026 to 2032 horizon, the stern drive propeller market is likely to be shaped by three broad movements: incremental efficiency-focused product design, more segmented material strategies, and a continued rebalancing between OEM integration and aftermarket specialization. These trends are not independent; each reinforces the others and influences how manufacturers, distributors, and end users allocate resources.
First, efficiency-oriented propeller design is expected to gain further prominence. Buyer sensitivity to fuel consumption, noise, and handling refinement supports continued interest in blade geometry innovations and dual-prop configurations where applicable. As more vessels adopt modern drive platforms and operators seek operational savings, products that deliver measurable performance improvements without compromising compatibility will likely find strong market receptivity. This creates opportunities for companies that can substantiate performance claims with clear testing and application-specific guidance.
Second, material strategies are likely to become more segmented. Broad-based aluminum and stainless steel portfolios will remain important for volume and compatibility, but specialized alloys and corrosion-resistant formulations will continue to matter for demanding environments and longer service life expectations. Cost volatility in key inputs will reward suppliers that can balance efficiency in standard production with selective premium offerings for high-value applications. In practice, this means more deliberate segmentation between mainstream replacement products and performance or commercial-grade lines.
Third, the relationship between propulsion system evolution and propeller design will intensify. Even if full electrification remains a gradual transition in sterndrive applications, hybrid configurations and revised torque characteristics will influence blade loading, hub requirements, and integration tolerances. Manufacturers that invest early in understanding these interaction points will be better prepared to support next-generation drive families and to reduce time-to-market for new compatible propeller lines.
These trends carry commercial opportunity, but they also introduce uncertainty. Material price swings, changing regulatory emphasis, and the pace of propulsion system modernization can all alter the speed and direction of demand. For investors and executives, the practical implication is that long-range planning should account for both baseline growth and scenario variability, especially where product roadmaps depend on input cost stability or specific drive-platform adoption patterns.
Strategic Recommendations for Decision-Makers
For manufacturers, the most effective strategy is to pursue disciplined differentiation rather than undifferentiated volume expansion. Strengthening compatibility with widely used sterndrive platforms, stabilizing material sourcing for corrosion-resistant lines, and developing clear performance narratives around efficiency and durability can help protect margins in a competitive environment. Companies should also evaluate channel balance carefully, ensuring that OEM relationships and aftermarket distribution complement rather than conflict with one another.
For investors, the priority is to identify businesses with defensible technical positions, flexible cost structures, and demonstrated ability to serve both established drive ecosystems and emerging performance niches. In a market where material volatility and product specialization both matter, firms with strong engineering execution and channel resilience are better positioned to sustain earnings through cycles. Due diligence should extend beyond headline revenue trends to include product pipeline relevance, hub and compatibility strategies, and exposure to input-cost sensitivity.
For procurement leaders and fleet operators, the focus should be on total lifecycle value rather than unit price alone. Compatibility assurance, predicted service life, maintenance impact, and supplier responsiveness all influence long-term operating costs. Standardizing on propeller families that align with existing drive platforms can reduce complexity, while selectively adopting higher-efficiency or higher-durability variants can improve performance where usage intensity justifies the investment. Maintaining visibility into supplier roadmaps and material availability will also support more resilient procurement planning.
For stakeholders seeking deeper segment-level data, regional revenue splits, application-level dynamics, and detailed competitive benchmarking, the full PW Consulting report provides a more granular view of market structure and forward scenarios. Detailed segmentation data and tailored strategic guidance can help translate these market-level observations into actionable plans aligned with specific product portfolios, geographies, and operating models.
Airplane Propellers Market
For detailed analysis of this topic, please visit the official page: Stern Drive Boat Propeller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Powder Transfer Pumps Market Hits $420M in 2025, Projects 5.5% CAGR to 2032
By pmarketresearch, 2026-09-17
Strategic Imperatives in the Powder Transfer Pumps Market: A 2026 Outlook
The global landscape for material handling is undergoing a subtle but significant transformation. As industrial operations demand higher levels of safety, efficiency, and hygiene, the machinery responsible for moving dry bulk solids has moved from a background utility to a strategic asset. For decision-makers navigating the 2026 fiscal year, understanding the trajectory of the Powder Transfer Pumps Market is no longer optional; it is a critical component of operational planning and capital allocation.
PW Consulting has released a comprehensive market research study designed to decode these complexities. This article serves as an executive preview of the findings, outlining the macro-economic trajectory, the evolving competitive landscape, and the regulatory pressures shaping the industry. While we highlight the strategic contours here, the full report contains the granular data necessary for precise forecasting and vendor selection.
Market Trajectory and Financial Scope
The financial health of the powder transfer pump sector reflects broader industrial confidence. Our analysis covers a substantial historical window from 2020 through 2025, providing a robust baseline for future projections. The market has demonstrated resilience despite supply chain volatilities and shifting industrial outputs during this period. In 2020, the global revenue stood at approximately 345.21 Million USD. Following a period of fluctuation, the sector climbed to 420.0 Million USD by 2025.
Looking forward, the forecast period spanning 2026 to 2032 indicates sustained growth. The market is projected to reach 443.54 Million USD in 2026, accelerating towards a peak valuation of 610.97 Million USD by 2032. This expansion is driven by a Compound Annual Growth Rate (CAGR) of 5.5 percent. For CFOs and operations directors, this growth rate signals a stable investment environment, though one that requires careful attention to inflationary pressures and technological adoption curves.
It is important to note that these figures represent the aggregate global value. The distribution of this revenue across specific geographies and application verticals varies significantly based on local industrial maturity and regulatory enforcement. Our full report dissects these variations to help stakeholders identify high-opportunity zones without relying on generalized assumptions.
Segmentation Dynamics: Type and Application Nuances
Understanding where value is generated within the supply chain is vital for product development and sales strategies. The market is broadly categorized by pump technology and end-use industry. In terms of technology, pneumatic solutions currently dominate the revenue share, reflecting their widespread adoption in standard industrial environments. Electric variants and other specialized types constitute the remainder, often serving niche requirements where automation or specific power constraints are prioritized.
On the application side, the pharmaceutical industry remains a primary revenue driver. The stringent hygiene standards required in drug manufacturing align perfectly with the contained transfer capabilities of modern powder pumps. The food and beverage sector follows closely, driven by the need for contamination-free processing of ingredients. The chemical industry and mining sector also contribute substantial volume, though their requirements often lean towards durability and hazard compliance rather than sanitary design.
A key insight from our analysis is the shift towards portable and modular systems. Many powder pumps now serve as cost-effective, portable alternatives to complex pneumatic conveying systems or mechanical conveyors for dry powder transfer. This flexibility allows smaller facilities or temporary production lines to adopt high-quality transfer technology without massive infrastructure investment. However, the specific revenue contribution of each segment is detailed in the proprietary tables of the full study, as these figures are subject to rapid change based on regional economic conditions.
Regional Overview and Industrial Hubs
Geographically, the market is distributed across five major regions: North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Asia Pacific represents a significant portion of the global volume, reflecting the concentration of manufacturing and pharmaceutical production in the region. North America and Europe maintain strong positions, largely fueled by stringent safety regulations and high replacement cycles for aging machinery.
Latin America and the Middle East and Africa represent emerging opportunities. While their current share is smaller compared to the established industrial hubs, growth rates in these areas are influenced by infrastructure development and foreign investment in chemical and processing facilities. For companies looking to expand their footprint, understanding the specific regulatory and logistical hurdles in these regions is essential. The complete report provides a detailed breakdown of market size by region, allowing strategists to prioritize market entry or expansion efforts effectively.
Competitive Landscape and Key Players
The market structure is moderately fragmented, with the top three companies holding a combined market share of 32.5 percent and the top five accounting for 41.8 percent. This concentration suggests that while large players dominate, there is ample room for specialized manufacturers to compete on technology, compliance, or regional service capabilities.
Several key companies define the current competitive arena. Tapflo, based in Sweden, offers compact powder diaphragm pumps such as the TXP series. These are designed for the economical transfer of industrial and sanitary process powders, including carbon black, resins, and food ingredients, with options for ATEX and FDA compliance. Similarly, Piab, also headquartered in Sweden, provides piFLOW vacuum conveyors tailored for hygienic, ATEX-compliant powder and bulk transfer in food, pharma, and industrial applications.
In the United States, Iwaki Air, located in Holliston, MA, provides AODD Portable Powder Pumps in aluminum or stainless steel. These are engineered for the safe, clean transfer of fine, dry, low bulk density powders. ARO, part of Ingersoll Rand, also operates out of the USA, offering powder transfer AODD pumps in the PP series ranging from 1 to 3 inches. These are positioned as a cost-effective alternative to complex systems for fast, clean bulk powder handling.
European engineering is further represented by De Dietrich Process Systems in France. They specialize in dense-phase Powder Pumps designed for contained, dust-free transfer in chemical and pharmaceutical industries, including mobile cart systems. In Asia, Yamada Corporation from Japan manufactures heavy-duty diaphragm Powder Pumps, specifically the BH series, which are built for fine-grained, low bulk density dry powders in dust-free operations. Ceracin, based in Vadodara, Gujarat, India, acts as a manufacturer and supplier focused on the effective transfer of powdered chemicals with high efficiency and portability.
Recent Developments and Innovation Trends
Innovation in this sector is currently driven by safety, flexibility, and containment. Recent activities among key players highlight this shift. In September 2025, De Dietrich Process Systems introduced flexible rental options for mobile Powder Pump carts. These units offer throughputs up to 3,250 lbs/hr, specifically targeting process trials and temporary use cases. This move indicates a market trend towards lowering the barrier to entry for advanced transfer technology.
Further emphasizing safety, Ovell Pump released details in January 2026 regarding their pneumatic powder diaphragm pumps. The promotion highlighted contained, spark-free transfer capabilities specifically designed for hazardous areas. This aligns with the growing demand for equipment that mitigates ignition risks in volatile environments. Additionally, in December 2025, Iwaki Air updated their information on AODD Powder Transfer Pumps, focusing on configurations in aluminum and stainless steel for fine, dry powders. These updates suggest a continued refinement of material choices to balance durability with product purity.
Regulatory Environment and Safety Dynamics
Compliance is no longer just a checkbox; it is a market driver. Many powder pumps currently comply with ATEX directives for explosion-proof operation in dust hazard zones and FDA standards for food and pharma applications. Manufacturers like Tapflo and ARO have integrated these standards deeply into their product documentation and design philosophies. As regulatory bodies tighten enforcement, non-compliant equipment faces increasing liability risks and market exclusion.
Furthermore, safety protocols are evolving. The OSHA Combustible Dust National Emphasis Program (NEP) continues to target industries such as food and chemicals for enhanced safety in powder handling operations. As of 2026, this ongoing initiative pressures facilities to audit their transfer equipment rigorously. Equipment that guarantees dust-free transfer and minimizes spark risks is becoming preferred procurement choices for EHS managers. The full market study includes a detailed regulatory impact analysis, quantifying how these directives influence purchasing cycles and equipment specifications across different sectors.
Strategic Value of the Full Report
While this overview provides the strategic framework, the complete PW Consulting report offers the tactical data required for execution. Decision-makers need more than top-line aggregates; they require segment-specific growth rates, detailed competitive profiling, and supply chain risk assessments. The full study allows stakeholders to:
- Validate investment decisions with precise historical and forecasted revenue data.
- Identify gaps in the current product offerings of key competitors like Tapflo, Piab, and ARO.
- Assess the impact of regulatory changes on operational costs and compliance timelines.
- Evaluate regional opportunities based on detailed market size splits rather than global averages.
The Powder Transfer Pumps Market is poised for steady expansion, but the winners in 2026 and beyond will be those who navigate the nuances of safety compliance, technological flexibility, and regional demand shifts. Accessing the full intelligence behind this preview is the next logical step for any organization serious about optimizing its material handling strategy.
Powder Transfer Pumps Market
Magnetic Pumps Market
For detailed analysis of this topic, please visit the official page: Powder Transfer Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: GRIN Lenses Market Hits $1,685.2M in 2025, Projecting 8.15% CAGR to 2032
By pmarketresearch, 2026-09-17
GRIN Lenses Market Outlook 2026-2032: Strategic Intelligence for Industry Leaders
The gradient index lens ecosystem is entering a phase of decisive structural expansion, driven by converging demands across precision optics, advanced imaging, and high-bandwidth communication infrastructure. For executives navigating technology procurement, R&D allocation, and competitive positioning, understanding the trajectory of this specialized market is no longer optional. This strategic briefing distills the most critical intelligence from the latest GRIN Lenses Market report, framing the 2026-2032 horizon through a lens of actionable insight rather than speculative forecasting.
The Macro Trajectory: Compounding Growth in a Precision Optics Niche
The global gradient index lens market has demonstrated consistent, compounding momentum over the past half-decade. Historical valuation data from 2020 through the 2025 base year reveals a clear upward arc, with revenue scaling from approximately $1,024.5 million to $1,685.2 million. This foundational growth establishes a robust baseline entering the forecast window. Looking ahead, the market is projected to accelerate through 2032, with 2026 valuations anticipated at $1,882.01 million and a terminal forecast value reaching $2,918.2 million by the close of the period.
The compound annual growth rate of 8.15% across the 2026-2032 forecast window signals more than incremental demand. It reflects a structural shift in how gradient index optics are specified, manufactured, and integrated across end-use sectors. Unlike commodity optical components, GRIN lenses deliver compact form factors, reduced aberration, and specialized light-manipulation capabilities that make them indispensable in applications where space, weight, and precision are simultaneously constrained. The sustained expansion rate indicates that adoption curves are maturing, with early-stage experimental deployments transitioning into standardized engineering requirements.
For corporate strategists, this trajectory carries immediate implications. Capital planning cycles that treat GRIN optics as peripheral components risk underinvestment in supply chain resilience and application-specific engineering capabilities. Conversely, organizations that align procurement roadmaps with the 8.15% growth axis can secure first-mover advantages in qualifying alternative suppliers, locking in technical specifications, and developing proprietary integration methodologies before demand intensifies across overlapping verticals.
Beyond the Headline: Where the Real Strategic Leverage Lies
Aggregate market sizing establishes the scale of opportunity, but the operational intelligence that drives competitive advantage resides in the granular segmentation architecture. The report deconstructs the market along three critical axes: geographic distribution, optic typology, and application-driven demand. Each dimension reveals distinct risk-reward profiles that procurement leaders, product managers, and investment committees must evaluate independently.
GRIN Lenses Market
Regional analysis maps the concentration of demand against manufacturing proximity, regulatory environments, and logistics complexity. While North America and Europe maintain established footprints in high-precision optical procurement, the Asia Pacific corridor represents a dynamically expanding demand zone that is reshaping supplier engagement models. Latin America and the Middle East and Africa present emerging deployment contexts where cost-structure optimization and localized technical support are becoming decisive procurement criteria. The geographic breakdown is not merely a demand heatmap; it is a blueprint for supply chain diversification, tariff mitigation, and regional partnership strategy.
Typological segmentation illuminates how engineering priorities are bifurcating. Radial gradient index lenses continue to command substantial market share, particularly where cylindrical symmetry and self-focusing properties deliver unmatched performance in micro-endoscopy, beam transformation, and compact imaging assemblies. Axial gradient index lenses occupy a specialized but rapidly evolving position, especially in applications requiring planar light propagation control, thermal imaging integration, and defense-related optical architectures. The residual category captures emerging custom configurations that blur traditional boundaries, reflecting the market's drift toward application-specific lens engineering rather than off-the-shelf standardization. Understanding these typological dynamics enables R&D teams to align material selection, ion-exchange process compatibility, and coating strategies with the precise performance envelopes their products require.
Application-driven segmentation translates market demand into functional need states. Optical communication systems leverage GRIN lenses for fiber coupling efficiency, mode-field matching, and collimation stability in high-throughput data transmission environments. Imaging systems depend on gradient index elements to minimize volumetric complexity while preserving resolution and chromatic fidelity. Medical instruments represent a particularly high-stakes segment, where biocompatibility, miniaturization, and repeatability directly influence clinical outcomes and regulatory clearance pathways. Consumer electronics integration continues to pressure suppliers toward cost-optimized scaling without compromising optical throughput. The residual application cluster encompasses industrial metrology, sensing architectures, and specialized research instrumentation, each carrying distinct qualification standards and lifecycle expectations. Mapping demand against these application vectors allows product strategists to prioritize development pipelines and anticipate specification drift before it manifests in procurement bottlenecks.
Competitive Architecture: Navigating a Consolidated yet Differentiated Landscape
The GRIN lens market operates under a moderately concentrated competitive structure, with the top three firms capturing approximately 38.5% of aggregate revenue and the top five extending their collective share to 52.8%. This concentration level indicates a market where incumbent technological leadership, process patents, and established qualification histories confer meaningful barriers to entry. Yet the remaining addressable share distributed across a broader supplier base ensures that niche specialization, regional responsiveness, and custom engineering capabilities remain viable differentiation pathways.
GRINTECH GmbH, headquartered in Jena, Germany, stands as a definitive reference point in the gradient index micro-optics landscape. The company's proprietary non-toxic silver and lithium ion exchange process in glass distinguishes its manufacturing methodology from conventional approaches, enabling rod lenses, objective lenses, and customized micro-optical systems that serve endoscopy, neuroscience, metrology, and industrial inspection applications. Importantly, GRINTECH's manufacturing process has achieved biocompatible certification according to the EN ISO 10993-1 standard, a credential that directly intersects with medical device procurement requirements and regulatory submission pathways. Recent activity reinforces this positioning: in January 2026, the company released an updated GRIN Rod Lenses catalog specifying non-toxic glass lenses across diameters ranging from 0.25 mm to 2.0 mm, followed by active participation at Photonics West 2026 in January, where it showcased its latest micro-optics solutions to a global audience of engineers, researchers, and procurement decision-makers.
Thorlabs Inc., based in Newton, New Jersey, operates as a widely accessible catalog supplier of GRIN lenses tailored for imaging, fiber coupling, and collimation workflows. Its offerings span uncoated and coated variants optimized for confocal microscopy, multiphoton imaging, and laser diode applications, positioning the firm as a reliable source for standardized optical elements that integrate quickly into laboratory and production environments.
Edmund Optics, also headquartered in Barrington, New Jersey, supplies gradient index rod lenses with a specified numerical aperture of 0.55, available across multiple working distances. Its portfolio addresses fiber coupling, laser diode collimation, and focusing applications, serving engineers who require predictable optical performance with straightforward integration parameters.
LightPath Technologies, operating from Orlando, Florida, differentiates through its GRADIUM axial GRIN lens offerings and custom gradient index solutions. The company's emphasis on IR GRIN optics for thermal imaging, defense, and industrial applications highlights a strategic focus on wavelength regimes and environmental conditions where conventional optical materials face performance limitations.
Complementing these established players, regional and portfolio-oriented suppliers such as FemtoTech (Xi'an) Co., Ltd. and Hobbite contribute to a diversified supply ecosystem. FemtoTech appears within photonics directories as a manufacturer of GRIN lenses serving optical application contexts, while Hobbite positions gradient index lenses within a broader optics portfolio, offering procurement teams alternative sourcing vectors for non-critical or cost-sensitive deployments. The presence of such suppliers reinforces the market's multi-tiered competitive structure, where tier-one technology leadership coexists with flexible, application-tailored sourcing options.
Integrating Regulatory Tailwinds and Innovation Signals
Market expansion does not occur in a vacuum. The GRIN lens landscape is being shaped by regulatory frameworks that increasingly intersect with material science, manufacturing safety, and end-use compliance. The documented use of non-toxic silver and lithium ion exchange processes, coupled with EN ISO 10993-1 biocompatibility certification for relevant product lines, represents more than a technical specification. It constitutes a procurement filter. Medical device OEMs, clinical research organizations, and regulated industrial manufacturers are progressively mandating supplier documentation that demonstrably aligns with biocompatibility standards and hazardous substance mitigation. Suppliers that can provide certified process documentation, traceable material provenance, and unambiguous safety data sheets are gaining preferential positioning in qualified vendor lists, while those lacking such compliance infrastructure face elongated evaluation cycles or exclusion from high-value procurement rounds.
Simultaneously, the cadence of industry events and catalog releases functions as an early-warning system for specification evolution. Participation at major photonics forums and the publication of updated lens catalogs signal where manufacturers are directing R&D attention, which diameter ranges and coating configurations are being prioritized, and how quickly catalog availability is expanding to cover emerging use cases. The January 2026 release of an expanded GRIN Rod Lenses catalog by a leading German manufacturer, followed by a prominent trade show presentation at Photonics West, illustrates how product documentation and live technical demonstrations converge to accelerate adoption cycles. Procurement teams monitoring these signals can anticipate specification standardization, identify forthcoming supply availability, and adjust internal qualification timelines accordingly.
What the Full GRIN Lenses Market Report Delivers
The complete market research deliverable extends far beyond aggregated sizing and high-level segmentation summaries. It functions as an operational playbook designed for cross-functional deployment across strategy, engineering, procurement, and investment functions. The report architecture is built around actionable intelligence layers that translate market data into decision-ready frameworks.
At the foundation level, the report provides a rigorously reconstructed historical baseline spanning 2020 through the 2025 base year, establishing verifiable demand trajectories that anchor forward-looking projections. The forecast period extending through 2032 applies scenario-aware modeling that accounts for application adoption curves, supply chain capacity constraints, and technological substitution risks. This temporal architecture enables executives to evaluate near-term procurement commitments against long-range capacity planning without conflating cyclical fluctuations with structural growth.
Optical Lenses Market
The segmentation depth within the full report isolates regional demand clusters, typological performance characteristics, and application-driven specification requirements without diluting analytical precision. Each segmentation layer is accompanied by demand-driver analysis that identifies the engineering, regulatory, and economic variables propelling volume expansion or contraction within that segment. Procurement leaders can use these breakdowns to evaluate supplier geographic exposure, assess logistics and tariff implications, and structure multi-source procurement strategies that balance cost efficiency with qualification reliability.
Competitive profiling in the complete deliverable moves beyond organizational summaries to map strategic postures, process differentiation, certification portfolios, and recent market signaling events. The inclusion of recent developments—such as catalog expansions, trade show presentations, and process certification milestones—provides a timeline-based view of how incumbents and challengers are actively shaping the supply environment. This temporal competitive intelligence allows product managers to benchmark their own development roadmaps against supplier capability trajectories and anticipate when particular lens configurations may shift from specialized availability to broader commercial accessibility.
Furthermore, the report integrates regulatory and standards-based considerations directly into the market dynamics discussion. Rather than treating compliance as a peripheral concern, the analysis positions material safety certifications, biocompatibility documentation, and process transparency as factors that influence supplier qualification velocity, procurement cycle duration, and total cost of ownership. Engineering teams responsible for design-in decisions receive contextualized guidance on which specifications carry regulatory weight in their target end-markets and which parameters remain purely performance-driven.
The deliverable is structured to support both strategic planning and operational execution. Executive summaries provide high-level directional clarity for board-level discussions and capital allocation reviews. Detailed segmentation tables and analytical narratives equip category managers and sourcing specialists with the granularity required to construct request-for-quotation packages, evaluate technical proposals, and negotiate supply agreements with informed confidence. Investment committees and corporate development teams gain access to market concentration metrics, growth axis projections, and competitive positioning assessments that inform M&A screening, partnership evaluation, and capability-investment prioritization.
Strategic Implications for 2026 Decision-Making
The GRIN lens market in 2026 sits at an inflection point where historical momentum, regulatory maturation, and application diversification converge to reshape procurement and engineering priorities. Organizations that treat this landscape as a static component category risk encountering specification bottlenecks, supply concentration exposure, and missed integration opportunities. Those that engage with the market through a structured intelligence framework can convert optical component strategy into competitive differentiation.
Immediate strategic imperatives include aligning internal qualification processes with suppliers that demonstrate certified process transparency and regulatory-aligned documentation, particularly for medical and defense-adjacent applications. Procurement roadmaps should incorporate regional demand shifts and evaluate multi-source architectures that reduce dependency on any single geographic or typological supply corridor. R&D and product engineering teams should monitor catalog expansions and trade show disclosures as leading indicators of specification standardization, using those signals to anticipate when custom configurations may become catalog-available and when legacy designs may require revision to maintain performance parity.
The moderately concentrated competitive structure also warrants deliberate supplier engagement strategies. Tier-one manufacturers with proprietary ion-exchange processes and established certification portfolios offer reliability and technical depth, while secondary suppliers provide flexibility, cost-optionality, and rapid responsiveness for non-critical or volume-sensitive deployments. Constructing a tiered supplier matrix that maps each vendor's process strengths, certification status, diameter ranges, and application fit against internal project requirements enables procurement teams to optimize for both performance assurance and commercial agility.
Access the Complete Strategic Intelligence
The macro trajectory, segmentation architecture, competitive profiles, and regulatory dynamics outlined here represent a strategic preview of the full GRIN Lenses Market research deliverable. The complete report provides the exhaustive dataset, scenario-based forecasts, detailed segmentation breakdowns, and vendor-evaluation frameworks required to translate directional insight into executed strategy. For executives, engineers, and procurement leaders seeking to secure supply resilience, align development roadmaps with market demand vectors, and position their organizations ahead of the 8.15% growth curve through 2032, the full research package offers the depth and operational specificity necessary for confident decision-making.
Detailed market sizing across all forecast years, comprehensive regional and application-level segmentation, proprietary competitive assessment matrices, and actionable procurement playbooks are available in the complete report. Access the full analysis to obtain the granular intelligence required to convert market trajectory into structural advantage.
For detailed analysis of this topic, please visit the official page: GRIN Lenses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Audio Cabinets Market Revenue Hits $1.82B in 2025, Projected 5.85% CAGR Through 2032
By pmarketresearch, 2026-09-17
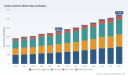
Strategic Intelligence for the 2026 Audio Cabinets Market: Navigating Growth, Consolidation, and Material Volatility
The global audio equipment ecosystem is undergoing a structural transformation, and audio cabinets remain at the physical and acoustic core of that evolution. As design philosophies shift toward integrated furniture-grade acoustics, professional touring demands intensify, and regional manufacturing footprints realign, enterprise leaders require more than headline revenue projections. They need a disciplined, decision-grade framework that connects material economics, competitive positioning, application-level demand vectors, and regional growth trajectories into a coherent roadmap for 2026 and beyond. Our newly released Audio Cabinets Market research report delivers exactly that: a comprehensive, data-backed intelligence asset engineered to de-risk capital allocation, product strategy, and supply chain planning.
The market has demonstrated resilient expansion across the 2020–2025 historical window, moving from approximately $1,420.45 million to $1,824.50 million. That trajectory reflects more than cyclical recovery; it signals durable demand across consumer, professional, and specialized automotive audio verticals. Looking ahead, the forecast period from 2026 through 2032 maps sustained momentum, with the market projected to reach $1,926.79 million in 2026 and expand to $2,718.95 million by 2032, underpinned by a compound annual growth rate of 5.85%. These figures are not abstract milestones. They represent the growth envelope within which manufacturing capacity, distribution partnerships, and product architectures will be evaluated, contested, and scaled over the next seven years.
For executives, procurement leaders, and strategy teams, the strategic question is no longer whether the market is expanding, but how value will be captured in an environment defined by material cost asymmetry, regional manufacturing realignments, and a moderately concentrated competitive field. This research is purpose-built to convert macro momentum into actionable strategic clarity.
The Strategic Imperative for 2026 Decision-Making
Entering 2026, the audio cabinets sector operates at the intersection of acoustic engineering, material science, and consumer-facing design expectations. The convergence of these forces creates both opportunity and friction. Organizations that rely on legacy cost structures or static product roadmaps will face margin compression, competitive displacement, or both. Conversely, firms that align product development cycles with regional demand patterns, material availability, and application-specific performance requirements will be better positioned to defend share while capturing incremental growth.
The report is structured to surface those alignment opportunities. Rather than treating the market as a single homogeneous category, it decomposes growth drivers by technology architecture, end-use application, and geographic demand centers, enabling decision-makers to identify where strategic focus yields the highest return on investment. The analysis is calibrated for leaders who need to evaluate manufacturing footprint decisions, assess entry or exit viability in specific applications, benchmark competitive positioning, and anticipate how raw material cost differentials will cascade through unit economics over the forecast horizon.
Audio Cabinets Market
Decoding the Research Architecture: What the Report Delivers
The Audio Cabinets Market study is organized as a practical intelligence toolkit rather than an academic survey. Its architecture is designed to support sequential decision-making, from high-level market sizing to granular competitive and operational insights. Key components include:
- Comprehensive historical reconstruction from 2020 through 2025, establishing baseline demand behavior, growth inflection points, and structural shifts that inform forward-looking forecasts.
- An extended forecast model spanning 2026 to 2032, providing a structured view of anticipated revenue expansion, CAGR dynamics, and the progression of market value across the prediction window.
- Segment-level analytical frameworks across product types, application verticals, and regional markets, enabling targeted scenario planning without exposing organizations to one-size-fits-all assumptions.
- Competitive landscape mapping that profiles leading manufacturers, evaluates positioning strategies, and contextualizes market concentration dynamics within the broader industry structure.
- Technology and material considerations, including how enclosure construction choices influence acoustic performance, cost profiles, and sourcing strategy.
- Recent market developments and product launches that signal emerging design directions, partnership models, and category expansion patterns relevant to 2026 planning.
Each section is developed to support operational decision-making. Product managers can use the application and type perspectives to prioritize enclosure designs and driver-integration strategies. Supply chain and procurement leaders can contextualize material selection within cost-performance trade-offs. Executive teams can leverage regional demand insights to anticipate where distribution scale, localization, or partnership structures will matter most. The report is intentionally designed to be referenced across functions, not siloed within a single business unit.
Competitive Landscape: Concentration, Positioning, and Strategic White Space
The competitive structure of the audio cabinets market reflects a moderately consolidated environment, with the top three players collectively representing approximately 38.5% of market share and the top five reaching roughly 52.7%. This concentration pattern suggests that established manufacturers hold meaningful positioning advantages in branding, distribution, and product credibility, while still leaving substantial room for specialized, regional, and application-focused competitors to compete on customization, acoustic tuning, and material execution.
Our competitive profiling examines players across multiple strategic archetypes. In the professional and touring audio segment, organizations such as JBL Professional and Martin Audio anchor demand for high-performance loudspeaker cabinets and enclosures built for live sound and installed systems. In the guitarist and bassist amplifier enclosure space, U.S.-based Avatar Speakers has sustained a factory-direct model centered on premium driver integration since the early 1990s, while U.K.-based Zilla Cabs competes on bespoke, handmade construction aimed at professional musicians seeking tailored tonal and structural characteristics.
On the high-fidelity and furniture-integrated side, the landscape includes premium acoustic furniture specialists and ecosystem-driven hi-fi brands. Spectral Audio Möbel emphasizes acoustic performance and design-led hi-fi cabinet construction for premium systems. Naim Audio integrates speaker enclosures and cabinets within a broader high-fidelity ecosystem, reinforcing system-level coherence rather than standalone component positioning. Quadraspire focuses on performance-oriented audio racks and cabinets engineered to reduce resonance and enhance clarity through material selection and structural design. These players illustrate how cabinet value is increasingly framed not only as acoustic containment, but as part of an integrated listening experience, interior design aesthetic, and system architecture.
The manufacturing dimension adds another strategic layer. Woodsat Audio Technology, operating as an OEM supplier of custom wooden enclosures since 2005, reflects the continued importance of contract manufacturing and white-label capability in serving global audio brands. This OEM dynamic matters because it shapes how quickly brands can scale enclosure programs, manage cost structures, and adapt to design changes without expanding their own fabrication capacity.
Recent 2026 developments reinforce the trend toward integration, customization, and category blending. In March 2026, ADI advanced its portfolio with the launch of more than 120 new Triad amplification, home cinema speaker, and subwoofer solutions, including customizable sound options that underscore demand for configurable audio environments. In April 2026, La-Z-Boy introduced the AudioLuxe premium audio furniture line at High Point Market, integrating Klipsch sound systems into customizable cabinets. These launches are strategically significant because they signal two parallel movements: the expansion of configurable professional and home-cinema audio offerings, and the migration of high-performance audio into furniture-grade, design-conscious enclosures. Both movements influence how cabinet manufacturers and audio brands think about enclosure form factor, finish, acoustic tuning, and channel strategy.
Server Cabinet Market
Material Economics and the Cost-Performance Equation
A critical, often under-modeled dimension of cabinet strategy is raw material economics. Enclosure construction directly affects acoustic behavior, durability, manufacturing complexity, and ultimately unit cost. As of the second quarter of 2025, Baltic birch plywood in 12mm 4x8 sheet format was priced in the range of $89 to $112 across North America and Europe, while standard MDF in 18mm 4x8 sheet format ranged between $42 and $58 in the same markets. That spread is not merely a procurement detail. It is a strategic variable that influences product tiering, margin architecture, and supplier negotiation leverage.
Industry data from early 2026 reinforces why MDF remains the preferred baseline for many speaker cabinet applications. Its consistent density and acoustic damping properties make it attractive for controlled enclosure performance, while its lower material cost, typically 30% to 40% below birch plywood, supports more favorable cost structures at scale. At the same time, premium and design-forward applications continue to justify higher-cost substrate choices when tonal character, furniture-grade aesthetics, or structural rigidity are differentiated value propositions. The strategic implication is clear: material selection is increasingly a portfolio decision rather than a single-specification rule. Companies that map substrate economics to application requirements, target price points, and regional sourcing conditions will have more flexibility to protect margins while meeting performance expectations.
Why This Research Matters for 2026 Planning Cycles
The 2026 planning cycle demands intelligence that can be used, not just read. Market momentum is evident, but momentum alone does not define where to invest, which applications to prioritize, or how to position against concentrated incumbents and agile specialists simultaneously. This report is built to convert growth signals into strategic action by connecting market sizing, segmentation logic, competitive behavior, and material cost dynamics into one coherent analytical environment.
By grounding the narrative in verified historical performance and extending it through a structured 2026–2032 forecast, the research gives leaders a defensible basis for scenario planning. The market’s projected progression from $1,926.79 million in 2026 to $2,718.95 million in 2032 provides a macro frame, while the segmentation, competitive, and material insights provide the executional detail necessary to interpret that frame in operational terms. This is the difference between knowing the market is growing and knowing where the growth is structurally coming from, which players are shaping it, and which cost and design variables will determine whether a company captures value or merely competes in it.
Positioning for informed strategic action
The audio cabinets market is not simply expanding; it is recalibrating around integration, customization, material economics, and application-specific performance demands. In that environment, the organizations that thrive will be those that pair growth awareness with disciplined strategic segmentation, competitive intelligence, and cost-aware design strategy. This research is designed to provide that foundation, giving executives and operational leaders a credible, detailed, and decision-ready view of the market landscape as they plan for 2026 and the years ahead.
To access the full segmentation detail, regional demand analysis, complete competitive profiles, and extended forecasts underpinning this overview, we invite you to explore the complete report on our website. The summary presented here is intended to establish the strategic context and analytical rigor of the study; the full intelligence package provides the comprehensive data architecture required for precise planning, investment evaluation, and competitive positioning across the 2026–2032 forecast period.
For detailed analysis of this topic, please visit the official page: Audio Cabinets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vortex Cooler Market Hits $728.5M in 2025, Poised for 5.85% CAGR to 2032
By pmarketresearch, 2026-09-17
Strategic Intelligence for the Vortex Cooler Market: Navigating Growth Trajectories Through 2032
Industrial cooling technologies have evolved from auxiliary utilities to mission-critical components in modern manufacturing ecosystems. As compressed air infrastructure becomes increasingly optimized and environmental regulations tighten around refrigerant-based systems, the vortex cooler market stands at a strategic inflection point. This article serves as a foundational preview of our comprehensive market research, designed to equip executive decision-makers with the macro-level intelligence required to allocate capital, position product portfolios, and anticipate competitive shifts across the 2026 to 2032 forecast horizon.
Worldwide Immersion Coolers Market
The trajectory of this sector is not merely a function of incremental demand growth. It reflects deeper industrial transformations: the push toward maintenance-free thermal management, the phasing out of synthetic refrigerants in sensitive electrical enclosures, and the geographic redistribution of manufacturing capacity. Our latest publication decodes these structural forces into actionable intelligence, bridging historical performance with forward-looking scenario modeling. The following analysis outlines the strategic architecture of the report, highlights the competitive dynamics shaping market share, and demonstrates why precise segmentation data remains indispensable for calibrated enterprise planning.
Market Architecture and Historical Trajectory
The vortex cooler market has demonstrated consistent expansion over the past half-decade, driven by sustained industrialization, automation scaling, and the operational advantages of compressed-air-based cooling systems. Our baseline analysis establishes a clear historical arc: from a foundational valuation of USD 512.45 million in 2020, the market advanced through successive growth cycles to reach USD 728.5 million by 2025. This progression underscores steady adoption across industrial environments where reliability, simplicity, and absence of moving parts translate directly into reduced downtime and lower maintenance overhead.
Looking forward, the forecast window from 2026 through 2032 projects a compound annual growth rate of 5.85 percent. This rate places the sector on a measured but unambiguous expansion path, culminating in a projected market valuation exceeding the one-billion-dollar threshold by the early 2030s. Such growth is not uniform; it is shaped by regional industrial density, material preference shifts, and application-specific thermal management requirements. Executives evaluating capacity expansion, supply chain localization, or product line diversification must understand how these structural variables interact. Our full report isolates these dynamics without obscuring them behind aggregated averages, ensuring that strategic plans are anchored in regionally and segmentally precise intelligence.
Vortex Cooler Market
Operational Scope of the Market Study
A market research publication is only as valuable as the decision-making clarity it delivers. Our vortex cooler study is structured to move beyond descriptive market sizing and into operational deployment. The report contains a modular assessment framework that covers the following core components:
- Historical baseline reconstruction spanning 2020 through 2025, with validated revenue trajectories and demand driver mapping
- Forward-looking scenario modeling across the 2026 to 2032 period, incorporating base, optimistic, and conservative growth pathways
- Material and engineering segmentation analysis, distinguishing adoption patterns across stainless steel configurations, polycarbonate alternatives, and other structural variants
- Application-level demand mapping that isolates industrial cooling, spot cooling, and electronics cooling as distinct thermal management use cases
- Regional market architecture covering North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, with localized demand intensity and infrastructure dependency indicators
- Regulatory and compliance context analysis, including NEMA enclosure ratings, hazardous location certifications, and refrigerant-free operational mandates
- Supply-side operational parameters, including compressed air pressure thresholds, filtration standards, and durability requirements in corrosive industrial environments
This structure is intentionally designed for cross-functional consumption. Engineering leaders can reference application-specific thermal performance parameters, procurement teams can align material and supply specifications with operational environments, and commercial strategy units can map regional growth intensity against sales territory planning. The full dataset, complete with segmentation values, pricing proxies, and adoption elasticity indicators, is available through the complete report download.
Competitive Landscape and Strategic Positioning
The vortex cooler segment is characterized by a moderately concentrated competitive structure. Current market analysis indicates that the top three participants collectively command approximately 42.8 percent of total market revenue, while the top five firms extend that influence to roughly 58.6 percent. This concentration pattern signals a market where established engineering capability, application-specific certification portfolios, and regional distribution networks create meaningful barriers to entry. At the same time, it leaves substantial addressable space for specialized players, regional distributors, and engineering-focused entrants that can differentiate through material durability, CFM capacity ranges, or enclosure integration design.
Several core enterprises define the competitive baseline. EXAIR Corporation, headquartered in Cincinnati, Ohio, offers stainless steel vortex tubes and spot coolers engineered for industrial applications capable of producing cold air down to negative 50 degrees Fahrenheit without moving parts, supplemented by cabinet cooler systems. ITW Vortec, also based in Cincinnati, pioneered commercial vortex tube technology in 1961 and continues to supply vortex A/C enclosure coolers in NEMA-rated and hazardous location configurations with cooling capacities spanning 400 to 5000 BTU per hour. Nex Flow Air Products Corp., operating from Ontario, Canada, manufactures Frigid-X vortex tubes in stainless steel with welded construction, targeting spot cooling and enclosure cooling applications. Meech International, based in the United Kingdom, provides stainless steel vortex tubes and cabinet coolers for spot cooling, machine cooling, and enclosure temperature control. nVent HOFFMAN, operating from the United States, supplies vortex cooling systems for indoor and outdoor enclosures that rely on compressed air rather than refrigerants. Streamtek Corp., headquartered in Canada, offers vortex tubes in stainless steel or aluminum with multiple CFM capacities for diverse cooling applications. AiRTX, known as Air Research Technology in the United States, specializes in precision stainless steel vortex tubes designed for spot cooling deployments.
Competitive differentiation in this space rarely depends on price alone. It emerges from certification breadth, material durability in corrosive environments, compressed air efficiency, and the ability to integrate cooling modules directly into electrical enclosure architectures. Recent market activity reinforces this pattern. ITW Vortec returned to trade show and exhibition spaces in August 2024, showcasing compressed air cooling products including vortex A/C enclosure coolers, signaling renewed emphasis on live demonstration and direct technical engagement with industrial buyers. Meech International updated its vortex cooling range brochure in April 2025, detailing stainless steel vortex tubes and cabinet coolers with revised performance specifications, reflecting an ongoing focus on specification transparency and application matching. These moves illustrate a sector where technical credibility and product documentation quality directly influence procurement confidence.
Industry Dynamics and Structural Drivers
The operating environment for vortex coolers is shaped by a combination of regulatory frameworks, material engineering realities, and utility infrastructure dependencies. Understanding these dynamics is essential for evaluating both market growth and implementation risk.
Regulatory and Certification Context
Vortex coolers are positioned as refrigerant-free thermal management solutions, which makes them particularly relevant in environments where chemical refrigerants are restricted, undesirable, or impractical. Compliance with NEMA 12, NEMA 4, and NEMA 4X enclosure standards, alongside hazardous location certifications such as ATEX, enables deployment in industrial electrical enclosures where environmental sealing and explosion safety are mandatory. This certification footprint is not incidental; it expands the addressable application base beyond standard factory floors into outdoor industrial sites, washdown environments, and classified hazardous zones. Organizations evaluating thermal management strategies must therefore treat certification readiness as a market access precondition, not a post-purchase consideration.
Material Engineering and Durability
Material selection directly influences lifecycle performance in industrial cooling applications. Vortex tubes are primarily constructed from stainless steel to deliver corrosion resistance and structural durability in demanding industrial environments. This material baseline aligns with the operational requirements of facilities exposed to moisture, chemical splash, particulate contamination, or temperature cycling. Alternatives such as polycarbonate and other materials serve specific cost, weight, or application constraints, but stainless steel remains the engineering default for high-intensity industrial deployments. Procurement and engineering teams evaluating total cost of ownership must weigh initial material cost against maintenance frequency, failure rates, and enclosure compatibility over multi-year deployment horizons.
Compressed Air Infrastructure Dependency
Performance optimization for vortex cooling systems depends on compressed air supply stability. Industry product guidelines indicate that compressed air at 80 to 100 PSIG is required for optimal vortex tube performance, with filtration recommended to 5 microns or better. This operational parameter creates a direct link between vortex cooler adoption and a facility existing compressed air infrastructure. Enterprises planning deployment must assess air quality, pressure consistency, and filtration readiness, because degraded air supply can reduce cooling efficiency and increase wear on internal components. In turn, this dynamic creates an adjacent market for filtration integration, air preparation accessories, and system sizing consultation, expanding the strategic relevance of vortex cooler vendors beyond the tube itself.
Strategic Implications for 2026 Decision-Making
The 2026 planning cycle requires executives to make capital and portfolio decisions against a backdrop of moderate but consistent growth, a competitive field with clear leaders yet meaningful fragmentation, and a technology profile that favors reliability, certification readiness, and infrastructure compatibility over novelty. Several strategic implications follow directly from the macro architecture of this market.
First, growth visibility in the vortex cooler sector is sufficient to justify capacity planning and distribution investment, but it does not eliminate the need for segmentation precision. Aggregate growth rates and total market size establish the ceiling; regional intensity, material preference, and application mix determine where value is actually captured. Companies that operate solely on headline growth figures risk misallocating sales resources, over-indexing on low-intensity territories, or under-serving high-demand application verticals.
Second, the moderately concentrated competitive structure suggests that market share gains will depend on technical differentiation and application-specific trust rather than broad-based discounting. Certification portfolios, enclosure compatibility, CFM range breadth, and material durability are the parameters that industrial buyers evaluate when selecting between established vendors and emerging alternatives. Strategic newcomers and regional players can compete effectively by narrowing their focus to specific enclosure types, hazardous location requirements, or compressed air integration specialties rather than attempting to replicate full-line incumbents from day one.
Third, regulatory and environmental trends continue to reinforce the strategic appeal of refrigerant-free cooling. As industrial facilities navigate compliance complexity, enclosure protection requirements, and maintenance efficiency targets, vortex coolers offer a mechanically simple, chemically benign alternative. This positioning does not guarantee automatic market share expansion, but it does expand the strategic conversation from cost-per-unit to lifecycle reliability and compliance alignment. Decision-makers should therefore evaluate vortex cooler adoption within broader facility thermal management strategies, not as isolated component purchases.
Fourth, compressed air dependency introduces both an adoption requirement and a service integration opportunity. Facilities with mature, well-filtered compressed air systems will extract optimal performance from vortex cooling modules. Facilities with inconsistent pressure delivery or poor filtration will face reduced efficiency and higher maintenance exposure. This reality creates strategic value for vendors and channel partners who bundle air preparation guidance, filtration recommendations, and system sizing support alongside the cooling hardware itself.
Why Complete Intelligence Matters
Strategic planning in a growing but structurally nuanced market requires more than directional confidence. It requires precise regional demand indicators, application-level adoption intensity, material-segment revenue distribution, and competitive share mapping that can be translated directly into territory planning, product roadmap decisions, and procurement forecasting. Aggregated market size and a credible CAGR provide the narrative frame; segmentation detail provides the operational map.
Our full vortex cooler market research delivers that operational map. It expands each macro dimension discussed here into validated figures, scenario parameters, and segment-level comparisons that enable procurement, engineering, sales leadership, and corporate strategy teams to align on the same evidence base. Readers seeking the complete dataset, including regional and application splits, material-segment valuations, concentration analysis, and forward scenario ranges, should access the full report through our source page. The complete publication is designed to support quantifiable investment cases, capacity allocation models, and competitive response planning across the 2026 to 2032 forecast period.
The vortex cooler market is not a high-volatility sector, but it is a strategically dense one. Growth is real, competitive positioning is measurable, and adoption outcomes depend on infrastructure readiness, certification alignment, and material durability. For organizations operating in industrial cooling, enclosure thermal management, or compressed air system integration, the difference between a reactive market posture and a proactive strategic position lies in the depth of intelligence available at the point of decision. Our research is built to provide that depth, and the complete market study remains the most direct path to securing it.
For detailed analysis of this topic, please visit the official page: Vortex Cooler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Nacelle Test Rig Market to Reach $908M in 2025, Growing at 6.1% CAGR Through 2032
By pmarketresearch, 2026-09-17
The Nacelle Test Rig Market in 2026: Strategic Intelligence for Next-Gen Wind Energy Investments
Executive Overview
The nacelle test rig market stands at a critical inflection point in 2026. As wind turbine architectures push toward larger rotor diameters, higher capacity ratings, and increasingly complex drivetrain configurations, the infrastructure required to validate these systems under realistic operational conditions has evolved from a niche engineering requirement to a foundational pillar of global wind energy deployment. Our latest Nacelle Test Rig Market research study is designed to equip executives, project developers, testing facility operators, and equipment manufacturers with the analytical clarity needed to navigate this rapidly maturing landscape.
This article serves as a strategic preview of the full report. It outlines the macro trajectory of the market, highlights the operational and regulatory forces shaping procurement and facility planning, and maps the competitive architecture that defines today’s testing ecosystem. In keeping with a trailer-style approach, we surface the methodological depth and actionable frameworks contained in the study while reserving granular segmentation breakdowns, regional allocation matrices, and company-level revenue benchmarks for the complete publication. Decision-makers who require precise allocation models, scenario-based forecasting, and vendor capability comparisons will find the full report structured to support board-level strategy, capital budgeting, and partnership evaluation.
Market Trajectory and Growth Architecture
The market has demonstrated consistent expansion across the historical review window, with global revenue climbing from approximately $612 million in 2020 to an estimated $908 million by 2025. This growth trajectory reflects a compounding set of tailwinds: accelerated turbine upscaling, tighter certification timelines, and the strategic imperative to de-risk performance before field installation. Looking forward, the forecast period through 2032 projects a compound annual growth rate of 6.1 percent, signaling a market that is not merely expanding in absolute terms but also maturing in its testing methodologies, geographic distribution, and application diversity.
The forward revenue path does not follow a straight line. The forecast model captures the natural cadence of capital deployment cycles, the staggered commissioning of large-scale test facilities, and the periodic recalibration of testing demand as turbine platforms move through prototype, pre-series, and commercial validation phases. By embedding these dynamics into a structured scenario framework, the study enables stakeholders to distinguish between baseline growth, downside risk from supply chain or permitting delays, and upside potential driven by offshore program acceleration or new certification mandates.
It is important to note that the aggregate figures presented here are deliberately high-level. The complete report decomposes the market by region, test rig type, and application vertical, providing the granular revenue splits and growth differentials that procurement leaders and strategy teams require for capacity planning and market entry decisions. Those segmentation details are surfaced within the full intelligence package, where they are cross-referenced with facility utilization trends, lead-time dynamics, and regional certification timelines.
Structural Drivers Shaping 2026 Decision-Making
Several interconnected forces are redefining how testing capacity is specified, justified, and deployed in 2026. The most consequential among them is turbine upscaling. As drivetrain architectures are engineered for higher torque loads and multi-megawatt output classes, test rigs must accommodate expanded motor drive systems, advanced wind load application units, and high-fidelity grid simulation capabilities. The testing envelope is no longer limited to functional verification; it must span endurance validation, extreme load simulation, and electrical certification under grid code conditions.
Regulatory and certification requirements reinforce this technical trajectory. Nacelle test rigs play an integral role in demonstrating compliance with grid code mandates and industry standards such as IEC 61400-21 and FGW TR3. For original equipment manufacturers and independent test houses alike, the ability to generate certified, repeatable test data directly influences time-to-market, warranty exposure, and the credibility of performance guarantees. In an environment where certification delays can cascade into project finance timelines and offshore installation windows, testing infrastructure becomes a strategic asset rather than a back-office function.
A second structural driver is the material and domestic content profile of nacelle assembly. Wind turbine nacelles require substantial steel and cast iron inputs for critical components, and in key markets such as the United States, domestic content for nacelle assembly exceeds 80 percent. This supply chain reality intersects with testing strategy in two ways. First, it heightens the importance of localized validation for components and subsystems intended for regionally assembled turbines. Second, it increases the strategic value of test facilities that can support domestic manufacturing roadmaps, supplier qualification programs, and content compliance documentation.
Finally, the market is being shaped by the growing differentiation between onshore and offshore testing demands. Offshore platforms impose more stringent validation requirements around corrosion environments, grid stability, maintenance access, and system reliability under variable offshore conditions. This divergence is expanding the scope of test rig specifications and encouraging operators to design multi-purpose facilities that can pivot between onshore and offshore validation protocols. The full report examines how these application and type-level dynamics influence capacity allocation, equipment configuration, and long-term utilization forecasts.
Competitive Landscape and Strategic Positioning
The competitive architecture of the nacelle test rig ecosystem is characterized by a mix of specialized system integrators, research-driven test laboratories, and manufacturer-operated validation centers. Market concentration remains moderately high, with the top three players accounting for approximately 58.7 percent of market revenue and the top five expanding that share to roughly 72.4 percent. This concentration reflects the technical complexity of high-capacity test systems, the capital intensity of facility development, and the importance of established certification relationships in winning repeat engagements.
Several organizations illustrate the breadth of strategic positioning within the market. RENK Test Systems, based in Augsburg, Germany, provides nacelle test rigs featuring expandable multi-motor drive systems capable of reaching 35 MW, alongside wind load application units and grid simulators that support development, quality assurance, endurance, and extreme load testing. R&D Test Systems, located in Hinnerup, Denmark, specializes in highly accelerated lifetime testing rigs and has developed one of the largest HALT XL test benches, with a 25 MW drive motor designed for offshore nacelle testing. Fraunhofer IWES, operating in Bremerhaven, Germany, runs the Dynamic Nacelle Testing Laboratory, known as DyNaLab, which enables realistic multi-megawatt nacelle testing and supports electrical certification through HiL-GridCoP capabilities. ZF Wind Power, headquartered in Lommel, Belgium, operates a 30 MW drivetrain and powertrain test rig at its Test and Prototype Center to validate onshore and offshore wind turbine systems. Calspan, based in Buffalo, New York, supplies engine test nacelle equipment including bellmouths, cowlings, and boat tails for aircraft engine testing, with licensed applications across CFM and Rolls-Royce engines.
While these companies differ in scope and end-use orientation, they collectively demonstrate the market’s movement toward higher power classes, broader simulation fidelity, and more integrated certification support. The study goes beyond corporate profiles to evaluate competitive dynamics through a structured lens: technology roadmaps, facility scalability, service attachment rates, and the strategic value of long-term testing partnerships. Understanding how these players differentiate themselves is essential for organizations evaluating vendor selection, co-development opportunities, or the feasibility of in-house test capability versus third-party outsourcing.
Recent Developments and Facility Investment Signals
Recent facility announcements and contract awards provide a real-time read on how the market is deploying capital and expanding testing capacity. In April 2025, ZF Wind Power commissioned a 30 MW drivetrain test rig at its Test and Prototype Centre in Lommel, Belgium, designed to validate full powertrain systems for both onshore and offshore wind turbines. This commissioning reflects the broader industry trend of increasing test capacity in step with turbine platform scaling and the need for integrated drivetrain validation before commercial rollout.
In February 2025, ORE Catapult appointed RENK Test System GmbH to design, manufacture, and install a new drive train test rig at its Blyth facility, initially capable of testing up to 23 MW. This engagement underscores how public-private and research-oriented testing infrastructure is being upgraded to support next-generation drivetrain validation and to provide regional testing access for developers and manufacturers. Taken together, these developments illustrate a market in which test capacity expansion is being aligned with immediate technology needs while also creating headroom for future higher-capacity platforms. The complete report places such events within a wider deployment timeline, allowing readers to assess the cumulative impact of new rigs, retrofits, and facility upgrades on regional testing availability and utilization patterns through 2032.
Report Framework and Operational Contents
The full Nacelle Test Rig Market study is built to support practical, multi-functional decision-making. It combines macro market modeling with operational content that strategy, engineering, procurement, and finance teams can apply directly to planning cycles. The report framework is organized to move from high-level market architecture to actionable detail, ensuring that readers can extract both strategic context and execution-oriented intelligence.
- Macro market sizing and forecast modeling across the historical review window and the 2026 through 2032 forecast period
- Segmentation analysis covering region, test rig type, and application, with qualitative commentary on growth differentials and demand drivers
- Competitive profiling of core participants, including technology capabilities, facility footprints, and strategic positioning within the testing value chain
- Market concentration assessment and implications for vendor negotiation, partnership structuring, and capacity risk management
- Regulatory and standards context, including the role of test rigs in grid code compliance, IEC 61400-21 alignment, and FGW TR3 certification support
- Recent deployments and contract activity that signal near-term capacity expansion and testing demand shifts
- Scenario-based outlooks that help decision-makers stress-test assumptions around turbine scaling, offshore program timing, and certification requirements
This structure is intentionally designed to serve multiple audiences. Executive teams can use the macro framing and competitive assessment to guide investment priorities and partnership strategy. Engineering and testing leaders can draw on the type- and application-level discussion to inform rig specification, validation scope, and facility planning. Procurement and supply chain professionals can leverage the concentration analysis and recent development tracking to benchmark vendor options and anticipate capacity constraints. Across all functions, the report aims to convert market complexity into a usable strategic map.
How to Use This Intelligence in 2026
As wind energy portfolios scale and turbine platforms become more demanding, the cost of testing uncertainty rises. Facilities that cannot accommodate higher power classes, simulate realistic grid and load conditions, or produce certification-grade data risk becoming bottlenecks in product development and project execution. At the same time, organizations that invest in the right testing capabilities or partnerships can accelerate validation cycles, strengthen performance credibility, and improve alignment with regional content and compliance expectations.
Engine Nacelle Market
The strategic value of this research lies in its ability to help leaders separate signal from noise. The market is large enough to offer opportunity and concentrated enough to require careful vendor and facility evaluation. It is growing steadily, yet subject to periodic resequencing as new rigs come online and testing demand shifts across onshore and offshore programs. By combining historical context, forward-looking modeling, competitive profiling, and regulatory grounding, the report provides a decision-ready foundation for capital allocation, vendor selection, and technology planning.
Conclusion
The nacelle test rig market in 2026 is defined by higher technical thresholds, tighter certification expectations, and a competitive field in which a limited number of players command a substantial share of revenue. The sector’s projected growth path supports continued investment in test capacity, but the practical details of segmentation, regional availability, and vendor capability will determine which organizations capture the most value from that expansion. Our full Nacelle Test Rig Market report is intended to provide those details in a structured, executive-ready format. Readers seeking the complete segmentation breakdowns, concentration analysis, and forward-looking scenario framework are encouraged to access the full study for comprehensive market intelligence and strategic guidance.
Nacelle Test Rig Market
For detailed analysis of this topic, please visit the official page: Nacelle Test Rig Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com