

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Stern Drive Boat Propeller Market: Why 6.7% CAGR Reshapes the $3.57B Outlook to 2032

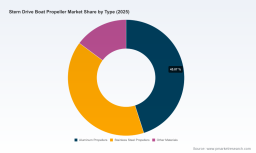
Stern Drive Boat Propeller Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The stern drive boat propeller market has demonstrated resilient expansion over the past half-decade, reaching an estimated valuation of USD 3,567.0 million in 2025. Historical data from 2020 through 2025 indicates a compound annual growth rate of 6.7 percent, positioning the sector on a solid trajectory toward USD 5,616.39 million by 2032. This growth reflects steady demand across recreational and commercial marine segments, alongside incremental technological upgrades that enable vessels to achieve better fuel efficiency and maneuverability. As marine propulsion systems evolve, the propeller component remains a critical interface between engine performance and hydrodynamic efficiency, making it a focal point for manufacturers and buyers alike.
Despite the favorable overarching trajectory, the industry faces several structural challenges that demand strategic attention. First, material cost volatility introduces pronounced uncertainty into pricing and margin forecasting. Raw material markets, particularly nickel-based alloys used in corrosion-resistant propeller designs, have experienced notable price swings between 2024 and 2025. Such fluctuations compress profitability for manufacturers operating on fixed-price contracts while simultaneously pressuring downstream buyers who seek predictable procurement costs. Second, the market exhibits moderate concentration, with the top three firms accounting for approximately 38.5 percent of total revenue and the top five controlling roughly 52.8 percent. This landscape creates both competitive stability and barriers for emerging players, particularly when established incumbents leverage decades of OEM relationships, proprietary hub architectures, and extensive aftermarket distribution networks. Third, the shift toward electrified and hybrid marine propulsion systems is gradually reshaping performance requirements. Traditional stern drive configurations must adapt to new torque curves, weight constraints, and acoustic expectations, compelling propeller designers to reconsider blade geometry, cavitation behavior, and integration standards.
For strategic decision-makers, these dynamics suggest that market participation requires more than scale alone. Success increasingly depends on material sourcing agility, technical differentiation, and the ability to align product portfolios with evolving vessel architectures. Organizations that anticipate these shifts rather than react to them are better positioned to capture share in both OEM channel development and aftermarket replacement cycles.
The intersection of growth momentum and structural complexity defines the current operating environment. Market participants must balance near-term revenue opportunities against longer-term technology transitions, while navigating cost pressures that affect both production economics and end-customer affordability. Understanding these forces is essential for prioritizing capital allocation, partnership strategies, and product roadmaps.
Key Drivers of Market Evolution
Three interconnected forces are shaping the directional path of the stern drive propeller market: material innovation, regulatory and environmental expectations, and shifting demand-side behavior in both recreational and commercial marine segments. Each driver carries distinct implications for product design, supply chain planning, and competitive positioning.
Material Innovation and Performance Optimization
Material selection continues to influence durability, weight, and operational efficiency across stern drive propeller applications. Aluminum and stainless steel formulations remain dominant in the market, with aluminum propellers representing the largest material category by revenue and stainless steel offering enhanced wear resistance for higher-performance applications. Alongside these mainstream materials, advanced nickel-aluminum bronze and specialty alloys retain importance for applications demanding superior corrosion resistance in saltwater environments. The breadth of material options allows manufacturers to tailor offerings to specific duty cycles, vessel weights, and propulsion loads.
Recent product activity underscores the strategic importance of material engineering and blade configuration. Michigan Wheel has reinforced its focus on core North American segments following the strategic divestiture of its United Kingdom operations to Nakashima Propeller, sharpening its attention on aluminum and stainless steel profiles compatible with major sterndrive platforms. This realignment reflects a broader pattern in which manufacturers concentrate resources on markets where OEM integration and aftermarket demand provide the strongest return on engineering investment. Meanwhile, Solas has emphasized renewed product visibility around both outboard and sterndrive propeller lines, signaling continued investment in material-grade differentiation and hub system compatibility such as RUBEX configurations.
From a commercial perspective, material-driven innovation affects more than technical specifications. It influences lead times, inventory planning, and dealer-level service capabilities. Manufacturers that stabilize alloy sourcing while offering clearly differentiated performance tiers can better manage cost volatility and present compelling upgrade paths to boat builders and fleet operators.
Regulatory and Environmental Pressures
Marine environmental standards and emissions expectations are gradually influencing propulsion system design, which in turn affects propeller engineering. While stern drive systems are not subject to the same regulatory intensity as automotive powertrains, broader maritime efficiency goals and local water-quality initiatives contribute to a performance mindset that favors reduced fuel consumption, lower vibration, and improved hydrodynamic behavior. These priorities encourage propeller designs that maximize thrust efficiency without increasing engine strain.
The regulatory environment also interacts with material choices. Corrosion resistance, service life, and recyclability are increasingly considered in procurement decisions for commercial fleets and high-use recreational vessels. Operators seek components that reduce downtime and maintenance exposure, particularly in regions where seasonal usage compresses available operating windows. Consequently, product longevity and reliability have become important selling points alongside raw performance metrics.
Demand-Side Shifts in Recreational and Commercial Segments
Recreational boating remains the largest application segment in the market, reflecting sustained consumer interest in leisure marine activities and aftermarket replacement cycles. Buyer behavior in this segment increasingly favors performance upgrades, easier installation compatibility, and visually distinctive blade profiles that align with customized boat configurations. At the same time, commercial operators prioritize durability, predictable maintenance intervals, and compatibility with existing drive families, especially where fleet standardization reduces training and parts complexity.
Within this demand landscape, product specialization is gaining traction. Sharrow Marine has extended testing and rollout activity for its looped propeller designs, including configurations intended for dual-prop sterndrive setups used with major drive platforms. This approach illustrates a broader trend: rather than competing solely on material grade, some manufacturers are pursuing aerodynamic and hydrodynamic geometry as a source of differentiation. The commercial relevance lies in the potential for improved efficiency and reduced vibration, which can appeal to both performance-oriented recreational buyers and commercial users seeking operational savings over long service intervals.
Supply Chain and Cost Structure Dynamics
Supply chain stability remains a defining concern for propeller manufacturers and downstream buyers. Fluctuations in key input costs, particularly for nickel-bearing alloys, have periodically reshaped pricing strategies and margin planning. Between 2024 and 2025, nickel-related pricing moved within a wide band, creating variable cost conditions for manufacturers producing corrosion-resistant propeller lines. This environment rewards companies with diversified sourcing strategies, forward procurement arrangements, and flexible production scheduling.
Cost structure pressures also influence the balance between standardized and customized offerings. High-volume standardized propeller families support efficient production and broader aftermarket availability, while specialized blade geometries and hub systems require more focused engineering and lower-volume runs. Companies that can maintain efficient core production while selectively introducing differentiated variants are better equipped to serve mixed demand without sacrificing margin integrity.
Competitive Landscape and Leading Strategies
The competitive environment in the stern drive propeller market is characterized by a blend of OEM-aligned suppliers, independent performance specialists, and integrated drive system manufacturers. The presence of both established marine propulsion names and focused propeller innovators creates a multifaceted landscape where differentiation can emerge from material technology, compatibility breadth, brand trust, or structural design innovation.
Strategic Positioning Among Key Players
Michigan Wheel occupies a prominent position through its extensive aluminum and stainless steel portfolio designed for sterndrive applications and its strong compatibility with widely used drive platforms. Its recent strategic decision to divest UK operations reflects a deliberate concentration on core market segments where distribution reach and aftermarket support provide durable advantage. By prioritizing compatibility and breadth of blade options, the company reinforces its role as a practical partner for both OEM integration and replacement demand.
Sharrow Marine differentiates itself through patented looped propeller technology and an emphasis on efficiency-oriented performance. Its continued expansion into dual-prop sterndrive configurations indicates a strategy centered on product architecture rather than commodity material competition. For buyers evaluating efficiency gains and refined handling characteristics, this positioning offers a distinct value proposition that complements traditional product categories.
Solas maintains a broad manufacturing footprint and strong compatibility across multiple sterndrive engine families, supported by hub technologies such as RUBEX systems. Its recent product display activity highlights ongoing attention to both outboard and sterndrive propeller lines, reinforcing its ability to serve multi-platform demand. Volvo Penta and Mercury Marine, as major OEM players, leverage their integrated system expertise to offer propellers that align closely with dedicated drive architectures, including counter-rotating and multiple blade configurations optimized for their respective units. This OEM alignment provides a strong baseline for compatibility trust, particularly among buyers seeking seamless system performance.
Marine Propeller Market
Several independent manufacturers, including Turning Point Propellers, PowerTech Propellers, Konrad Marine, and Hill Marine, add further diversity to the market. Their focus areas range from high-quality aluminum and stainless steel profiles to performance stainless steel designs and heavy-duty commercial applications. This breadth allows buyers to select from a range of price-performance points, while also creating opportunities for specialized distributors and service networks.
Market Structure and Evolution Trends
The market remains moderately consolidated, but it is not static. Consolidation pressures may continue in areas where scale, OEM access, and global distribution confer durable advantages. At the same time, product innovation and niche application focus create room for differentiation even in a concentrated environment. The most notable evolution is the increasing importance of technology-led positioning: companies are competing not only on material and compatibility, but also on blade geometry, vibration reduction, and application-specific tuning.
Another emerging trend is the interplay between OEM channels and independent aftermarket demand. While OEM relationships provide volume stability, aftermarket replacement and performance upgrades can offer higher margin opportunities and faster product iteration cycles. Manufacturers that manage both channels effectively are able to balance predictable volume with selective premium offerings. This dual-channel capability is increasingly important as recreational boat owners seek upgrade paths and commercial operators evaluate lifecycle cost rather than initial purchase price alone.
Geographic dynamics also matter, though competitive advantage is often determined less by regional volume leadership than by proximity to major boat-building clusters, service infrastructure, and drive-platform ecosystems. Firms with strong operational presence in key North American and European marine markets benefit from shorter feedback loops with boat builders and faster response to regional product preferences. Meanwhile, manufacturers with multi-region production and distribution capabilities can better manage supply continuity and currency exposure in a volatile input-cost environment.
PW Consulting Automotive & Machinery Research Center
For commercial strategists, the key question is not simply who holds the largest share today, but which companies can sustain differentiation through product engineering, channel flexibility, and cost control. Competitive success will likely favor organizations that can align proprietary design advantages with reliable supply execution and clear compatibility messaging.
Forward-Looking Trends and Commercial Implications
Looking ahead across the 2026 to 2032 horizon, the stern drive propeller market is likely to be shaped by three broad movements: incremental efficiency-focused product design, more segmented material strategies, and a continued rebalancing between OEM integration and aftermarket specialization. These trends are not independent; each reinforces the others and influences how manufacturers, distributors, and end users allocate resources.
First, efficiency-oriented propeller design is expected to gain further prominence. Buyer sensitivity to fuel consumption, noise, and handling refinement supports continued interest in blade geometry innovations and dual-prop configurations where applicable. As more vessels adopt modern drive platforms and operators seek operational savings, products that deliver measurable performance improvements without compromising compatibility will likely find strong market receptivity. This creates opportunities for companies that can substantiate performance claims with clear testing and application-specific guidance.
Second, material strategies are likely to become more segmented. Broad-based aluminum and stainless steel portfolios will remain important for volume and compatibility, but specialized alloys and corrosion-resistant formulations will continue to matter for demanding environments and longer service life expectations. Cost volatility in key inputs will reward suppliers that can balance efficiency in standard production with selective premium offerings for high-value applications. In practice, this means more deliberate segmentation between mainstream replacement products and performance or commercial-grade lines.
Third, the relationship between propulsion system evolution and propeller design will intensify. Even if full electrification remains a gradual transition in sterndrive applications, hybrid configurations and revised torque characteristics will influence blade loading, hub requirements, and integration tolerances. Manufacturers that invest early in understanding these interaction points will be better prepared to support next-generation drive families and to reduce time-to-market for new compatible propeller lines.
These trends carry commercial opportunity, but they also introduce uncertainty. Material price swings, changing regulatory emphasis, and the pace of propulsion system modernization can all alter the speed and direction of demand. For investors and executives, the practical implication is that long-range planning should account for both baseline growth and scenario variability, especially where product roadmaps depend on input cost stability or specific drive-platform adoption patterns.
Strategic Recommendations for Decision-Makers
For manufacturers, the most effective strategy is to pursue disciplined differentiation rather than undifferentiated volume expansion. Strengthening compatibility with widely used sterndrive platforms, stabilizing material sourcing for corrosion-resistant lines, and developing clear performance narratives around efficiency and durability can help protect margins in a competitive environment. Companies should also evaluate channel balance carefully, ensuring that OEM relationships and aftermarket distribution complement rather than conflict with one another.
For investors, the priority is to identify businesses with defensible technical positions, flexible cost structures, and demonstrated ability to serve both established drive ecosystems and emerging performance niches. In a market where material volatility and product specialization both matter, firms with strong engineering execution and channel resilience are better positioned to sustain earnings through cycles. Due diligence should extend beyond headline revenue trends to include product pipeline relevance, hub and compatibility strategies, and exposure to input-cost sensitivity.
For procurement leaders and fleet operators, the focus should be on total lifecycle value rather than unit price alone. Compatibility assurance, predicted service life, maintenance impact, and supplier responsiveness all influence long-term operating costs. Standardizing on propeller families that align with existing drive platforms can reduce complexity, while selectively adopting higher-efficiency or higher-durability variants can improve performance where usage intensity justifies the investment. Maintaining visibility into supplier roadmaps and material availability will also support more resilient procurement planning.
For stakeholders seeking deeper segment-level data, regional revenue splits, application-level dynamics, and detailed competitive benchmarking, the full PW Consulting report provides a more granular view of market structure and forward scenarios. Detailed segmentation data and tailored strategic guidance can help translate these market-level observations into actionable plans aligned with specific product portfolios, geographies, and operating models.
Airplane Propellers Market
For detailed analysis of this topic, please visit the official page: Stern Drive Boat Propeller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com