

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Vortex Cooler Market Hits $728.5M in 2025, Poised for 5.85% CAGR to 2032

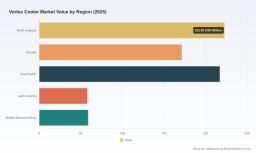
Strategic Intelligence for the Vortex Cooler Market: Navigating Growth Trajectories Through 2032
Industrial cooling technologies have evolved from auxiliary utilities to mission-critical components in modern manufacturing ecosystems. As compressed air infrastructure becomes increasingly optimized and environmental regulations tighten around refrigerant-based systems, the vortex cooler market stands at a strategic inflection point. This article serves as a foundational preview of our comprehensive market research, designed to equip executive decision-makers with the macro-level intelligence required to allocate capital, position product portfolios, and anticipate competitive shifts across the 2026 to 2032 forecast horizon.
Worldwide Immersion Coolers Market
The trajectory of this sector is not merely a function of incremental demand growth. It reflects deeper industrial transformations: the push toward maintenance-free thermal management, the phasing out of synthetic refrigerants in sensitive electrical enclosures, and the geographic redistribution of manufacturing capacity. Our latest publication decodes these structural forces into actionable intelligence, bridging historical performance with forward-looking scenario modeling. The following analysis outlines the strategic architecture of the report, highlights the competitive dynamics shaping market share, and demonstrates why precise segmentation data remains indispensable for calibrated enterprise planning.
Market Architecture and Historical Trajectory
The vortex cooler market has demonstrated consistent expansion over the past half-decade, driven by sustained industrialization, automation scaling, and the operational advantages of compressed-air-based cooling systems. Our baseline analysis establishes a clear historical arc: from a foundational valuation of USD 512.45 million in 2020, the market advanced through successive growth cycles to reach USD 728.5 million by 2025. This progression underscores steady adoption across industrial environments where reliability, simplicity, and absence of moving parts translate directly into reduced downtime and lower maintenance overhead.
Looking forward, the forecast window from 2026 through 2032 projects a compound annual growth rate of 5.85 percent. This rate places the sector on a measured but unambiguous expansion path, culminating in a projected market valuation exceeding the one-billion-dollar threshold by the early 2030s. Such growth is not uniform; it is shaped by regional industrial density, material preference shifts, and application-specific thermal management requirements. Executives evaluating capacity expansion, supply chain localization, or product line diversification must understand how these structural variables interact. Our full report isolates these dynamics without obscuring them behind aggregated averages, ensuring that strategic plans are anchored in regionally and segmentally precise intelligence.
Vortex Cooler Market
Operational Scope of the Market Study
A market research publication is only as valuable as the decision-making clarity it delivers. Our vortex cooler study is structured to move beyond descriptive market sizing and into operational deployment. The report contains a modular assessment framework that covers the following core components:
- Historical baseline reconstruction spanning 2020 through 2025, with validated revenue trajectories and demand driver mapping
- Forward-looking scenario modeling across the 2026 to 2032 period, incorporating base, optimistic, and conservative growth pathways
- Material and engineering segmentation analysis, distinguishing adoption patterns across stainless steel configurations, polycarbonate alternatives, and other structural variants
- Application-level demand mapping that isolates industrial cooling, spot cooling, and electronics cooling as distinct thermal management use cases
- Regional market architecture covering North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, with localized demand intensity and infrastructure dependency indicators
- Regulatory and compliance context analysis, including NEMA enclosure ratings, hazardous location certifications, and refrigerant-free operational mandates
- Supply-side operational parameters, including compressed air pressure thresholds, filtration standards, and durability requirements in corrosive industrial environments
This structure is intentionally designed for cross-functional consumption. Engineering leaders can reference application-specific thermal performance parameters, procurement teams can align material and supply specifications with operational environments, and commercial strategy units can map regional growth intensity against sales territory planning. The full dataset, complete with segmentation values, pricing proxies, and adoption elasticity indicators, is available through the complete report download.
Competitive Landscape and Strategic Positioning
The vortex cooler segment is characterized by a moderately concentrated competitive structure. Current market analysis indicates that the top three participants collectively command approximately 42.8 percent of total market revenue, while the top five firms extend that influence to roughly 58.6 percent. This concentration pattern signals a market where established engineering capability, application-specific certification portfolios, and regional distribution networks create meaningful barriers to entry. At the same time, it leaves substantial addressable space for specialized players, regional distributors, and engineering-focused entrants that can differentiate through material durability, CFM capacity ranges, or enclosure integration design.
Several core enterprises define the competitive baseline. EXAIR Corporation, headquartered in Cincinnati, Ohio, offers stainless steel vortex tubes and spot coolers engineered for industrial applications capable of producing cold air down to negative 50 degrees Fahrenheit without moving parts, supplemented by cabinet cooler systems. ITW Vortec, also based in Cincinnati, pioneered commercial vortex tube technology in 1961 and continues to supply vortex A/C enclosure coolers in NEMA-rated and hazardous location configurations with cooling capacities spanning 400 to 5000 BTU per hour. Nex Flow Air Products Corp., operating from Ontario, Canada, manufactures Frigid-X vortex tubes in stainless steel with welded construction, targeting spot cooling and enclosure cooling applications. Meech International, based in the United Kingdom, provides stainless steel vortex tubes and cabinet coolers for spot cooling, machine cooling, and enclosure temperature control. nVent HOFFMAN, operating from the United States, supplies vortex cooling systems for indoor and outdoor enclosures that rely on compressed air rather than refrigerants. Streamtek Corp., headquartered in Canada, offers vortex tubes in stainless steel or aluminum with multiple CFM capacities for diverse cooling applications. AiRTX, known as Air Research Technology in the United States, specializes in precision stainless steel vortex tubes designed for spot cooling deployments.
Competitive differentiation in this space rarely depends on price alone. It emerges from certification breadth, material durability in corrosive environments, compressed air efficiency, and the ability to integrate cooling modules directly into electrical enclosure architectures. Recent market activity reinforces this pattern. ITW Vortec returned to trade show and exhibition spaces in August 2024, showcasing compressed air cooling products including vortex A/C enclosure coolers, signaling renewed emphasis on live demonstration and direct technical engagement with industrial buyers. Meech International updated its vortex cooling range brochure in April 2025, detailing stainless steel vortex tubes and cabinet coolers with revised performance specifications, reflecting an ongoing focus on specification transparency and application matching. These moves illustrate a sector where technical credibility and product documentation quality directly influence procurement confidence.
Industry Dynamics and Structural Drivers
The operating environment for vortex coolers is shaped by a combination of regulatory frameworks, material engineering realities, and utility infrastructure dependencies. Understanding these dynamics is essential for evaluating both market growth and implementation risk.
Regulatory and Certification Context
Vortex coolers are positioned as refrigerant-free thermal management solutions, which makes them particularly relevant in environments where chemical refrigerants are restricted, undesirable, or impractical. Compliance with NEMA 12, NEMA 4, and NEMA 4X enclosure standards, alongside hazardous location certifications such as ATEX, enables deployment in industrial electrical enclosures where environmental sealing and explosion safety are mandatory. This certification footprint is not incidental; it expands the addressable application base beyond standard factory floors into outdoor industrial sites, washdown environments, and classified hazardous zones. Organizations evaluating thermal management strategies must therefore treat certification readiness as a market access precondition, not a post-purchase consideration.
Material Engineering and Durability
Material selection directly influences lifecycle performance in industrial cooling applications. Vortex tubes are primarily constructed from stainless steel to deliver corrosion resistance and structural durability in demanding industrial environments. This material baseline aligns with the operational requirements of facilities exposed to moisture, chemical splash, particulate contamination, or temperature cycling. Alternatives such as polycarbonate and other materials serve specific cost, weight, or application constraints, but stainless steel remains the engineering default for high-intensity industrial deployments. Procurement and engineering teams evaluating total cost of ownership must weigh initial material cost against maintenance frequency, failure rates, and enclosure compatibility over multi-year deployment horizons.
Compressed Air Infrastructure Dependency
Performance optimization for vortex cooling systems depends on compressed air supply stability. Industry product guidelines indicate that compressed air at 80 to 100 PSIG is required for optimal vortex tube performance, with filtration recommended to 5 microns or better. This operational parameter creates a direct link between vortex cooler adoption and a facility existing compressed air infrastructure. Enterprises planning deployment must assess air quality, pressure consistency, and filtration readiness, because degraded air supply can reduce cooling efficiency and increase wear on internal components. In turn, this dynamic creates an adjacent market for filtration integration, air preparation accessories, and system sizing consultation, expanding the strategic relevance of vortex cooler vendors beyond the tube itself.
Strategic Implications for 2026 Decision-Making
The 2026 planning cycle requires executives to make capital and portfolio decisions against a backdrop of moderate but consistent growth, a competitive field with clear leaders yet meaningful fragmentation, and a technology profile that favors reliability, certification readiness, and infrastructure compatibility over novelty. Several strategic implications follow directly from the macro architecture of this market.
First, growth visibility in the vortex cooler sector is sufficient to justify capacity planning and distribution investment, but it does not eliminate the need for segmentation precision. Aggregate growth rates and total market size establish the ceiling; regional intensity, material preference, and application mix determine where value is actually captured. Companies that operate solely on headline growth figures risk misallocating sales resources, over-indexing on low-intensity territories, or under-serving high-demand application verticals.
Second, the moderately concentrated competitive structure suggests that market share gains will depend on technical differentiation and application-specific trust rather than broad-based discounting. Certification portfolios, enclosure compatibility, CFM range breadth, and material durability are the parameters that industrial buyers evaluate when selecting between established vendors and emerging alternatives. Strategic newcomers and regional players can compete effectively by narrowing their focus to specific enclosure types, hazardous location requirements, or compressed air integration specialties rather than attempting to replicate full-line incumbents from day one.
Third, regulatory and environmental trends continue to reinforce the strategic appeal of refrigerant-free cooling. As industrial facilities navigate compliance complexity, enclosure protection requirements, and maintenance efficiency targets, vortex coolers offer a mechanically simple, chemically benign alternative. This positioning does not guarantee automatic market share expansion, but it does expand the strategic conversation from cost-per-unit to lifecycle reliability and compliance alignment. Decision-makers should therefore evaluate vortex cooler adoption within broader facility thermal management strategies, not as isolated component purchases.
Fourth, compressed air dependency introduces both an adoption requirement and a service integration opportunity. Facilities with mature, well-filtered compressed air systems will extract optimal performance from vortex cooling modules. Facilities with inconsistent pressure delivery or poor filtration will face reduced efficiency and higher maintenance exposure. This reality creates strategic value for vendors and channel partners who bundle air preparation guidance, filtration recommendations, and system sizing support alongside the cooling hardware itself.
Why Complete Intelligence Matters
Strategic planning in a growing but structurally nuanced market requires more than directional confidence. It requires precise regional demand indicators, application-level adoption intensity, material-segment revenue distribution, and competitive share mapping that can be translated directly into territory planning, product roadmap decisions, and procurement forecasting. Aggregated market size and a credible CAGR provide the narrative frame; segmentation detail provides the operational map.
Our full vortex cooler market research delivers that operational map. It expands each macro dimension discussed here into validated figures, scenario parameters, and segment-level comparisons that enable procurement, engineering, sales leadership, and corporate strategy teams to align on the same evidence base. Readers seeking the complete dataset, including regional and application splits, material-segment valuations, concentration analysis, and forward scenario ranges, should access the full report through our source page. The complete publication is designed to support quantifiable investment cases, capacity allocation models, and competitive response planning across the 2026 to 2032 forecast period.
The vortex cooler market is not a high-volatility sector, but it is a strategically dense one. Growth is real, competitive positioning is measurable, and adoption outcomes depend on infrastructure readiness, certification alignment, and material durability. For organizations operating in industrial cooling, enclosure thermal management, or compressed air system integration, the difference between a reactive market posture and a proactive strategic position lies in the depth of intelligence available at the point of decision. Our research is built to provide that depth, and the complete market study remains the most direct path to securing it.
For detailed analysis of this topic, please visit the official page: Vortex Cooler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com