

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: GRIN Lenses Market Hits $1,685.2M in 2025, Projecting 8.15% CAGR to 2032

GRIN Lenses Market Outlook 2026-2032: Strategic Intelligence for Industry Leaders
The gradient index lens ecosystem is entering a phase of decisive structural expansion, driven by converging demands across precision optics, advanced imaging, and high-bandwidth communication infrastructure. For executives navigating technology procurement, R&D allocation, and competitive positioning, understanding the trajectory of this specialized market is no longer optional. This strategic briefing distills the most critical intelligence from the latest GRIN Lenses Market report, framing the 2026-2032 horizon through a lens of actionable insight rather than speculative forecasting.
The Macro Trajectory: Compounding Growth in a Precision Optics Niche
The global gradient index lens market has demonstrated consistent, compounding momentum over the past half-decade. Historical valuation data from 2020 through the 2025 base year reveals a clear upward arc, with revenue scaling from approximately $1,024.5 million to $1,685.2 million. This foundational growth establishes a robust baseline entering the forecast window. Looking ahead, the market is projected to accelerate through 2032, with 2026 valuations anticipated at $1,882.01 million and a terminal forecast value reaching $2,918.2 million by the close of the period.
The compound annual growth rate of 8.15% across the 2026-2032 forecast window signals more than incremental demand. It reflects a structural shift in how gradient index optics are specified, manufactured, and integrated across end-use sectors. Unlike commodity optical components, GRIN lenses deliver compact form factors, reduced aberration, and specialized light-manipulation capabilities that make them indispensable in applications where space, weight, and precision are simultaneously constrained. The sustained expansion rate indicates that adoption curves are maturing, with early-stage experimental deployments transitioning into standardized engineering requirements.
For corporate strategists, this trajectory carries immediate implications. Capital planning cycles that treat GRIN optics as peripheral components risk underinvestment in supply chain resilience and application-specific engineering capabilities. Conversely, organizations that align procurement roadmaps with the 8.15% growth axis can secure first-mover advantages in qualifying alternative suppliers, locking in technical specifications, and developing proprietary integration methodologies before demand intensifies across overlapping verticals.
Beyond the Headline: Where the Real Strategic Leverage Lies
Aggregate market sizing establishes the scale of opportunity, but the operational intelligence that drives competitive advantage resides in the granular segmentation architecture. The report deconstructs the market along three critical axes: geographic distribution, optic typology, and application-driven demand. Each dimension reveals distinct risk-reward profiles that procurement leaders, product managers, and investment committees must evaluate independently.
GRIN Lenses Market
Regional analysis maps the concentration of demand against manufacturing proximity, regulatory environments, and logistics complexity. While North America and Europe maintain established footprints in high-precision optical procurement, the Asia Pacific corridor represents a dynamically expanding demand zone that is reshaping supplier engagement models. Latin America and the Middle East and Africa present emerging deployment contexts where cost-structure optimization and localized technical support are becoming decisive procurement criteria. The geographic breakdown is not merely a demand heatmap; it is a blueprint for supply chain diversification, tariff mitigation, and regional partnership strategy.
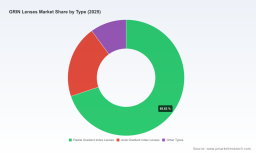
Typological segmentation illuminates how engineering priorities are bifurcating. Radial gradient index lenses continue to command substantial market share, particularly where cylindrical symmetry and self-focusing properties deliver unmatched performance in micro-endoscopy, beam transformation, and compact imaging assemblies. Axial gradient index lenses occupy a specialized but rapidly evolving position, especially in applications requiring planar light propagation control, thermal imaging integration, and defense-related optical architectures. The residual category captures emerging custom configurations that blur traditional boundaries, reflecting the market's drift toward application-specific lens engineering rather than off-the-shelf standardization. Understanding these typological dynamics enables R&D teams to align material selection, ion-exchange process compatibility, and coating strategies with the precise performance envelopes their products require.
Application-driven segmentation translates market demand into functional need states. Optical communication systems leverage GRIN lenses for fiber coupling efficiency, mode-field matching, and collimation stability in high-throughput data transmission environments. Imaging systems depend on gradient index elements to minimize volumetric complexity while preserving resolution and chromatic fidelity. Medical instruments represent a particularly high-stakes segment, where biocompatibility, miniaturization, and repeatability directly influence clinical outcomes and regulatory clearance pathways. Consumer electronics integration continues to pressure suppliers toward cost-optimized scaling without compromising optical throughput. The residual application cluster encompasses industrial metrology, sensing architectures, and specialized research instrumentation, each carrying distinct qualification standards and lifecycle expectations. Mapping demand against these application vectors allows product strategists to prioritize development pipelines and anticipate specification drift before it manifests in procurement bottlenecks.
Competitive Architecture: Navigating a Consolidated yet Differentiated Landscape
The GRIN lens market operates under a moderately concentrated competitive structure, with the top three firms capturing approximately 38.5% of aggregate revenue and the top five extending their collective share to 52.8%. This concentration level indicates a market where incumbent technological leadership, process patents, and established qualification histories confer meaningful barriers to entry. Yet the remaining addressable share distributed across a broader supplier base ensures that niche specialization, regional responsiveness, and custom engineering capabilities remain viable differentiation pathways.
GRINTECH GmbH, headquartered in Jena, Germany, stands as a definitive reference point in the gradient index micro-optics landscape. The company's proprietary non-toxic silver and lithium ion exchange process in glass distinguishes its manufacturing methodology from conventional approaches, enabling rod lenses, objective lenses, and customized micro-optical systems that serve endoscopy, neuroscience, metrology, and industrial inspection applications. Importantly, GRINTECH's manufacturing process has achieved biocompatible certification according to the EN ISO 10993-1 standard, a credential that directly intersects with medical device procurement requirements and regulatory submission pathways. Recent activity reinforces this positioning: in January 2026, the company released an updated GRIN Rod Lenses catalog specifying non-toxic glass lenses across diameters ranging from 0.25 mm to 2.0 mm, followed by active participation at Photonics West 2026 in January, where it showcased its latest micro-optics solutions to a global audience of engineers, researchers, and procurement decision-makers.
Thorlabs Inc., based in Newton, New Jersey, operates as a widely accessible catalog supplier of GRIN lenses tailored for imaging, fiber coupling, and collimation workflows. Its offerings span uncoated and coated variants optimized for confocal microscopy, multiphoton imaging, and laser diode applications, positioning the firm as a reliable source for standardized optical elements that integrate quickly into laboratory and production environments.
Edmund Optics, also headquartered in Barrington, New Jersey, supplies gradient index rod lenses with a specified numerical aperture of 0.55, available across multiple working distances. Its portfolio addresses fiber coupling, laser diode collimation, and focusing applications, serving engineers who require predictable optical performance with straightforward integration parameters.
LightPath Technologies, operating from Orlando, Florida, differentiates through its GRADIUM axial GRIN lens offerings and custom gradient index solutions. The company's emphasis on IR GRIN optics for thermal imaging, defense, and industrial applications highlights a strategic focus on wavelength regimes and environmental conditions where conventional optical materials face performance limitations.
Complementing these established players, regional and portfolio-oriented suppliers such as FemtoTech (Xi'an) Co., Ltd. and Hobbite contribute to a diversified supply ecosystem. FemtoTech appears within photonics directories as a manufacturer of GRIN lenses serving optical application contexts, while Hobbite positions gradient index lenses within a broader optics portfolio, offering procurement teams alternative sourcing vectors for non-critical or cost-sensitive deployments. The presence of such suppliers reinforces the market's multi-tiered competitive structure, where tier-one technology leadership coexists with flexible, application-tailored sourcing options.
Integrating Regulatory Tailwinds and Innovation Signals
Market expansion does not occur in a vacuum. The GRIN lens landscape is being shaped by regulatory frameworks that increasingly intersect with material science, manufacturing safety, and end-use compliance. The documented use of non-toxic silver and lithium ion exchange processes, coupled with EN ISO 10993-1 biocompatibility certification for relevant product lines, represents more than a technical specification. It constitutes a procurement filter. Medical device OEMs, clinical research organizations, and regulated industrial manufacturers are progressively mandating supplier documentation that demonstrably aligns with biocompatibility standards and hazardous substance mitigation. Suppliers that can provide certified process documentation, traceable material provenance, and unambiguous safety data sheets are gaining preferential positioning in qualified vendor lists, while those lacking such compliance infrastructure face elongated evaluation cycles or exclusion from high-value procurement rounds.
Simultaneously, the cadence of industry events and catalog releases functions as an early-warning system for specification evolution. Participation at major photonics forums and the publication of updated lens catalogs signal where manufacturers are directing R&D attention, which diameter ranges and coating configurations are being prioritized, and how quickly catalog availability is expanding to cover emerging use cases. The January 2026 release of an expanded GRIN Rod Lenses catalog by a leading German manufacturer, followed by a prominent trade show presentation at Photonics West, illustrates how product documentation and live technical demonstrations converge to accelerate adoption cycles. Procurement teams monitoring these signals can anticipate specification standardization, identify forthcoming supply availability, and adjust internal qualification timelines accordingly.
What the Full GRIN Lenses Market Report Delivers
The complete market research deliverable extends far beyond aggregated sizing and high-level segmentation summaries. It functions as an operational playbook designed for cross-functional deployment across strategy, engineering, procurement, and investment functions. The report architecture is built around actionable intelligence layers that translate market data into decision-ready frameworks.
At the foundation level, the report provides a rigorously reconstructed historical baseline spanning 2020 through the 2025 base year, establishing verifiable demand trajectories that anchor forward-looking projections. The forecast period extending through 2032 applies scenario-aware modeling that accounts for application adoption curves, supply chain capacity constraints, and technological substitution risks. This temporal architecture enables executives to evaluate near-term procurement commitments against long-range capacity planning without conflating cyclical fluctuations with structural growth.
Optical Lenses Market
The segmentation depth within the full report isolates regional demand clusters, typological performance characteristics, and application-driven specification requirements without diluting analytical precision. Each segmentation layer is accompanied by demand-driver analysis that identifies the engineering, regulatory, and economic variables propelling volume expansion or contraction within that segment. Procurement leaders can use these breakdowns to evaluate supplier geographic exposure, assess logistics and tariff implications, and structure multi-source procurement strategies that balance cost efficiency with qualification reliability.
Competitive profiling in the complete deliverable moves beyond organizational summaries to map strategic postures, process differentiation, certification portfolios, and recent market signaling events. The inclusion of recent developments—such as catalog expansions, trade show presentations, and process certification milestones—provides a timeline-based view of how incumbents and challengers are actively shaping the supply environment. This temporal competitive intelligence allows product managers to benchmark their own development roadmaps against supplier capability trajectories and anticipate when particular lens configurations may shift from specialized availability to broader commercial accessibility.
Furthermore, the report integrates regulatory and standards-based considerations directly into the market dynamics discussion. Rather than treating compliance as a peripheral concern, the analysis positions material safety certifications, biocompatibility documentation, and process transparency as factors that influence supplier qualification velocity, procurement cycle duration, and total cost of ownership. Engineering teams responsible for design-in decisions receive contextualized guidance on which specifications carry regulatory weight in their target end-markets and which parameters remain purely performance-driven.
The deliverable is structured to support both strategic planning and operational execution. Executive summaries provide high-level directional clarity for board-level discussions and capital allocation reviews. Detailed segmentation tables and analytical narratives equip category managers and sourcing specialists with the granularity required to construct request-for-quotation packages, evaluate technical proposals, and negotiate supply agreements with informed confidence. Investment committees and corporate development teams gain access to market concentration metrics, growth axis projections, and competitive positioning assessments that inform M&A screening, partnership evaluation, and capability-investment prioritization.
Strategic Implications for 2026 Decision-Making
The GRIN lens market in 2026 sits at an inflection point where historical momentum, regulatory maturation, and application diversification converge to reshape procurement and engineering priorities. Organizations that treat this landscape as a static component category risk encountering specification bottlenecks, supply concentration exposure, and missed integration opportunities. Those that engage with the market through a structured intelligence framework can convert optical component strategy into competitive differentiation.
Immediate strategic imperatives include aligning internal qualification processes with suppliers that demonstrate certified process transparency and regulatory-aligned documentation, particularly for medical and defense-adjacent applications. Procurement roadmaps should incorporate regional demand shifts and evaluate multi-source architectures that reduce dependency on any single geographic or typological supply corridor. R&D and product engineering teams should monitor catalog expansions and trade show disclosures as leading indicators of specification standardization, using those signals to anticipate when custom configurations may become catalog-available and when legacy designs may require revision to maintain performance parity.
The moderately concentrated competitive structure also warrants deliberate supplier engagement strategies. Tier-one manufacturers with proprietary ion-exchange processes and established certification portfolios offer reliability and technical depth, while secondary suppliers provide flexibility, cost-optionality, and rapid responsiveness for non-critical or volume-sensitive deployments. Constructing a tiered supplier matrix that maps each vendor's process strengths, certification status, diameter ranges, and application fit against internal project requirements enables procurement teams to optimize for both performance assurance and commercial agility.
Access the Complete Strategic Intelligence
The macro trajectory, segmentation architecture, competitive profiles, and regulatory dynamics outlined here represent a strategic preview of the full GRIN Lenses Market research deliverable. The complete report provides the exhaustive dataset, scenario-based forecasts, detailed segmentation breakdowns, and vendor-evaluation frameworks required to translate directional insight into executed strategy. For executives, engineers, and procurement leaders seeking to secure supply resilience, align development roadmaps with market demand vectors, and position their organizations ahead of the 8.15% growth curve through 2032, the full research package offers the depth and operational specificity necessary for confident decision-making.
Detailed market sizing across all forecast years, comprehensive regional and application-level segmentation, proprietary competitive assessment matrices, and actionable procurement playbooks are available in the complete report. Access the full analysis to obtain the granular intelligence required to convert market trajectory into structural advantage.
For detailed analysis of this topic, please visit the official page: GRIN Lenses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com