

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Nacelle Test Rig Market to Reach $908M in 2025, Growing at 6.1% CAGR Through 2032

The Nacelle Test Rig Market in 2026: Strategic Intelligence for Next-Gen Wind Energy Investments
Executive Overview
The nacelle test rig market stands at a critical inflection point in 2026. As wind turbine architectures push toward larger rotor diameters, higher capacity ratings, and increasingly complex drivetrain configurations, the infrastructure required to validate these systems under realistic operational conditions has evolved from a niche engineering requirement to a foundational pillar of global wind energy deployment. Our latest Nacelle Test Rig Market research study is designed to equip executives, project developers, testing facility operators, and equipment manufacturers with the analytical clarity needed to navigate this rapidly maturing landscape.
This article serves as a strategic preview of the full report. It outlines the macro trajectory of the market, highlights the operational and regulatory forces shaping procurement and facility planning, and maps the competitive architecture that defines today’s testing ecosystem. In keeping with a trailer-style approach, we surface the methodological depth and actionable frameworks contained in the study while reserving granular segmentation breakdowns, regional allocation matrices, and company-level revenue benchmarks for the complete publication. Decision-makers who require precise allocation models, scenario-based forecasting, and vendor capability comparisons will find the full report structured to support board-level strategy, capital budgeting, and partnership evaluation.
Market Trajectory and Growth Architecture
The market has demonstrated consistent expansion across the historical review window, with global revenue climbing from approximately $612 million in 2020 to an estimated $908 million by 2025. This growth trajectory reflects a compounding set of tailwinds: accelerated turbine upscaling, tighter certification timelines, and the strategic imperative to de-risk performance before field installation. Looking forward, the forecast period through 2032 projects a compound annual growth rate of 6.1 percent, signaling a market that is not merely expanding in absolute terms but also maturing in its testing methodologies, geographic distribution, and application diversity.
The forward revenue path does not follow a straight line. The forecast model captures the natural cadence of capital deployment cycles, the staggered commissioning of large-scale test facilities, and the periodic recalibration of testing demand as turbine platforms move through prototype, pre-series, and commercial validation phases. By embedding these dynamics into a structured scenario framework, the study enables stakeholders to distinguish between baseline growth, downside risk from supply chain or permitting delays, and upside potential driven by offshore program acceleration or new certification mandates.
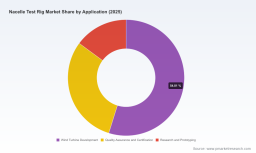
It is important to note that the aggregate figures presented here are deliberately high-level. The complete report decomposes the market by region, test rig type, and application vertical, providing the granular revenue splits and growth differentials that procurement leaders and strategy teams require for capacity planning and market entry decisions. Those segmentation details are surfaced within the full intelligence package, where they are cross-referenced with facility utilization trends, lead-time dynamics, and regional certification timelines.
Structural Drivers Shaping 2026 Decision-Making
Several interconnected forces are redefining how testing capacity is specified, justified, and deployed in 2026. The most consequential among them is turbine upscaling. As drivetrain architectures are engineered for higher torque loads and multi-megawatt output classes, test rigs must accommodate expanded motor drive systems, advanced wind load application units, and high-fidelity grid simulation capabilities. The testing envelope is no longer limited to functional verification; it must span endurance validation, extreme load simulation, and electrical certification under grid code conditions.
Regulatory and certification requirements reinforce this technical trajectory. Nacelle test rigs play an integral role in demonstrating compliance with grid code mandates and industry standards such as IEC 61400-21 and FGW TR3. For original equipment manufacturers and independent test houses alike, the ability to generate certified, repeatable test data directly influences time-to-market, warranty exposure, and the credibility of performance guarantees. In an environment where certification delays can cascade into project finance timelines and offshore installation windows, testing infrastructure becomes a strategic asset rather than a back-office function.
A second structural driver is the material and domestic content profile of nacelle assembly. Wind turbine nacelles require substantial steel and cast iron inputs for critical components, and in key markets such as the United States, domestic content for nacelle assembly exceeds 80 percent. This supply chain reality intersects with testing strategy in two ways. First, it heightens the importance of localized validation for components and subsystems intended for regionally assembled turbines. Second, it increases the strategic value of test facilities that can support domestic manufacturing roadmaps, supplier qualification programs, and content compliance documentation.
Finally, the market is being shaped by the growing differentiation between onshore and offshore testing demands. Offshore platforms impose more stringent validation requirements around corrosion environments, grid stability, maintenance access, and system reliability under variable offshore conditions. This divergence is expanding the scope of test rig specifications and encouraging operators to design multi-purpose facilities that can pivot between onshore and offshore validation protocols. The full report examines how these application and type-level dynamics influence capacity allocation, equipment configuration, and long-term utilization forecasts.
Competitive Landscape and Strategic Positioning
The competitive architecture of the nacelle test rig ecosystem is characterized by a mix of specialized system integrators, research-driven test laboratories, and manufacturer-operated validation centers. Market concentration remains moderately high, with the top three players accounting for approximately 58.7 percent of market revenue and the top five expanding that share to roughly 72.4 percent. This concentration reflects the technical complexity of high-capacity test systems, the capital intensity of facility development, and the importance of established certification relationships in winning repeat engagements.
Several organizations illustrate the breadth of strategic positioning within the market. RENK Test Systems, based in Augsburg, Germany, provides nacelle test rigs featuring expandable multi-motor drive systems capable of reaching 35 MW, alongside wind load application units and grid simulators that support development, quality assurance, endurance, and extreme load testing. R&D Test Systems, located in Hinnerup, Denmark, specializes in highly accelerated lifetime testing rigs and has developed one of the largest HALT XL test benches, with a 25 MW drive motor designed for offshore nacelle testing. Fraunhofer IWES, operating in Bremerhaven, Germany, runs the Dynamic Nacelle Testing Laboratory, known as DyNaLab, which enables realistic multi-megawatt nacelle testing and supports electrical certification through HiL-GridCoP capabilities. ZF Wind Power, headquartered in Lommel, Belgium, operates a 30 MW drivetrain and powertrain test rig at its Test and Prototype Center to validate onshore and offshore wind turbine systems. Calspan, based in Buffalo, New York, supplies engine test nacelle equipment including bellmouths, cowlings, and boat tails for aircraft engine testing, with licensed applications across CFM and Rolls-Royce engines.
While these companies differ in scope and end-use orientation, they collectively demonstrate the market’s movement toward higher power classes, broader simulation fidelity, and more integrated certification support. The study goes beyond corporate profiles to evaluate competitive dynamics through a structured lens: technology roadmaps, facility scalability, service attachment rates, and the strategic value of long-term testing partnerships. Understanding how these players differentiate themselves is essential for organizations evaluating vendor selection, co-development opportunities, or the feasibility of in-house test capability versus third-party outsourcing.
Recent Developments and Facility Investment Signals
Recent facility announcements and contract awards provide a real-time read on how the market is deploying capital and expanding testing capacity. In April 2025, ZF Wind Power commissioned a 30 MW drivetrain test rig at its Test and Prototype Centre in Lommel, Belgium, designed to validate full powertrain systems for both onshore and offshore wind turbines. This commissioning reflects the broader industry trend of increasing test capacity in step with turbine platform scaling and the need for integrated drivetrain validation before commercial rollout.
In February 2025, ORE Catapult appointed RENK Test System GmbH to design, manufacture, and install a new drive train test rig at its Blyth facility, initially capable of testing up to 23 MW. This engagement underscores how public-private and research-oriented testing infrastructure is being upgraded to support next-generation drivetrain validation and to provide regional testing access for developers and manufacturers. Taken together, these developments illustrate a market in which test capacity expansion is being aligned with immediate technology needs while also creating headroom for future higher-capacity platforms. The complete report places such events within a wider deployment timeline, allowing readers to assess the cumulative impact of new rigs, retrofits, and facility upgrades on regional testing availability and utilization patterns through 2032.
Report Framework and Operational Contents
The full Nacelle Test Rig Market study is built to support practical, multi-functional decision-making. It combines macro market modeling with operational content that strategy, engineering, procurement, and finance teams can apply directly to planning cycles. The report framework is organized to move from high-level market architecture to actionable detail, ensuring that readers can extract both strategic context and execution-oriented intelligence.
- Macro market sizing and forecast modeling across the historical review window and the 2026 through 2032 forecast period
- Segmentation analysis covering region, test rig type, and application, with qualitative commentary on growth differentials and demand drivers
- Competitive profiling of core participants, including technology capabilities, facility footprints, and strategic positioning within the testing value chain
- Market concentration assessment and implications for vendor negotiation, partnership structuring, and capacity risk management
- Regulatory and standards context, including the role of test rigs in grid code compliance, IEC 61400-21 alignment, and FGW TR3 certification support
- Recent deployments and contract activity that signal near-term capacity expansion and testing demand shifts
- Scenario-based outlooks that help decision-makers stress-test assumptions around turbine scaling, offshore program timing, and certification requirements
This structure is intentionally designed to serve multiple audiences. Executive teams can use the macro framing and competitive assessment to guide investment priorities and partnership strategy. Engineering and testing leaders can draw on the type- and application-level discussion to inform rig specification, validation scope, and facility planning. Procurement and supply chain professionals can leverage the concentration analysis and recent development tracking to benchmark vendor options and anticipate capacity constraints. Across all functions, the report aims to convert market complexity into a usable strategic map.
How to Use This Intelligence in 2026
As wind energy portfolios scale and turbine platforms become more demanding, the cost of testing uncertainty rises. Facilities that cannot accommodate higher power classes, simulate realistic grid and load conditions, or produce certification-grade data risk becoming bottlenecks in product development and project execution. At the same time, organizations that invest in the right testing capabilities or partnerships can accelerate validation cycles, strengthen performance credibility, and improve alignment with regional content and compliance expectations.
Engine Nacelle Market
The strategic value of this research lies in its ability to help leaders separate signal from noise. The market is large enough to offer opportunity and concentrated enough to require careful vendor and facility evaluation. It is growing steadily, yet subject to periodic resequencing as new rigs come online and testing demand shifts across onshore and offshore programs. By combining historical context, forward-looking modeling, competitive profiling, and regulatory grounding, the report provides a decision-ready foundation for capital allocation, vendor selection, and technology planning.
Conclusion
The nacelle test rig market in 2026 is defined by higher technical thresholds, tighter certification expectations, and a competitive field in which a limited number of players command a substantial share of revenue. The sector’s projected growth path supports continued investment in test capacity, but the practical details of segmentation, regional availability, and vendor capability will determine which organizations capture the most value from that expansion. Our full Nacelle Test Rig Market report is intended to provide those details in a structured, executive-ready format. Readers seeking the complete segmentation breakdowns, concentration analysis, and forward-looking scenario framework are encouraged to access the full study for comprehensive market intelligence and strategic guidance.
Nacelle Test Rig Market
For detailed analysis of this topic, please visit the official page: Nacelle Test Rig Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com