

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Audio Cabinets Market Revenue Hits $1.82B in 2025, Projected 5.85% CAGR Through 2032

Strategic Intelligence for the 2026 Audio Cabinets Market: Navigating Growth, Consolidation, and Material Volatility
The global audio equipment ecosystem is undergoing a structural transformation, and audio cabinets remain at the physical and acoustic core of that evolution. As design philosophies shift toward integrated furniture-grade acoustics, professional touring demands intensify, and regional manufacturing footprints realign, enterprise leaders require more than headline revenue projections. They need a disciplined, decision-grade framework that connects material economics, competitive positioning, application-level demand vectors, and regional growth trajectories into a coherent roadmap for 2026 and beyond. Our newly released Audio Cabinets Market research report delivers exactly that: a comprehensive, data-backed intelligence asset engineered to de-risk capital allocation, product strategy, and supply chain planning.
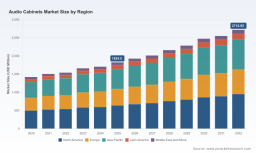
The market has demonstrated resilient expansion across the 2020–2025 historical window, moving from approximately $1,420.45 million to $1,824.50 million. That trajectory reflects more than cyclical recovery; it signals durable demand across consumer, professional, and specialized automotive audio verticals. Looking ahead, the forecast period from 2026 through 2032 maps sustained momentum, with the market projected to reach $1,926.79 million in 2026 and expand to $2,718.95 million by 2032, underpinned by a compound annual growth rate of 5.85%. These figures are not abstract milestones. They represent the growth envelope within which manufacturing capacity, distribution partnerships, and product architectures will be evaluated, contested, and scaled over the next seven years.
For executives, procurement leaders, and strategy teams, the strategic question is no longer whether the market is expanding, but how value will be captured in an environment defined by material cost asymmetry, regional manufacturing realignments, and a moderately concentrated competitive field. This research is purpose-built to convert macro momentum into actionable strategic clarity.
The Strategic Imperative for 2026 Decision-Making
Entering 2026, the audio cabinets sector operates at the intersection of acoustic engineering, material science, and consumer-facing design expectations. The convergence of these forces creates both opportunity and friction. Organizations that rely on legacy cost structures or static product roadmaps will face margin compression, competitive displacement, or both. Conversely, firms that align product development cycles with regional demand patterns, material availability, and application-specific performance requirements will be better positioned to defend share while capturing incremental growth.
The report is structured to surface those alignment opportunities. Rather than treating the market as a single homogeneous category, it decomposes growth drivers by technology architecture, end-use application, and geographic demand centers, enabling decision-makers to identify where strategic focus yields the highest return on investment. The analysis is calibrated for leaders who need to evaluate manufacturing footprint decisions, assess entry or exit viability in specific applications, benchmark competitive positioning, and anticipate how raw material cost differentials will cascade through unit economics over the forecast horizon.
Audio Cabinets Market
Decoding the Research Architecture: What the Report Delivers
The Audio Cabinets Market study is organized as a practical intelligence toolkit rather than an academic survey. Its architecture is designed to support sequential decision-making, from high-level market sizing to granular competitive and operational insights. Key components include:
- Comprehensive historical reconstruction from 2020 through 2025, establishing baseline demand behavior, growth inflection points, and structural shifts that inform forward-looking forecasts.
- An extended forecast model spanning 2026 to 2032, providing a structured view of anticipated revenue expansion, CAGR dynamics, and the progression of market value across the prediction window.
- Segment-level analytical frameworks across product types, application verticals, and regional markets, enabling targeted scenario planning without exposing organizations to one-size-fits-all assumptions.
- Competitive landscape mapping that profiles leading manufacturers, evaluates positioning strategies, and contextualizes market concentration dynamics within the broader industry structure.
- Technology and material considerations, including how enclosure construction choices influence acoustic performance, cost profiles, and sourcing strategy.
- Recent market developments and product launches that signal emerging design directions, partnership models, and category expansion patterns relevant to 2026 planning.
Each section is developed to support operational decision-making. Product managers can use the application and type perspectives to prioritize enclosure designs and driver-integration strategies. Supply chain and procurement leaders can contextualize material selection within cost-performance trade-offs. Executive teams can leverage regional demand insights to anticipate where distribution scale, localization, or partnership structures will matter most. The report is intentionally designed to be referenced across functions, not siloed within a single business unit.
Competitive Landscape: Concentration, Positioning, and Strategic White Space
The competitive structure of the audio cabinets market reflects a moderately consolidated environment, with the top three players collectively representing approximately 38.5% of market share and the top five reaching roughly 52.7%. This concentration pattern suggests that established manufacturers hold meaningful positioning advantages in branding, distribution, and product credibility, while still leaving substantial room for specialized, regional, and application-focused competitors to compete on customization, acoustic tuning, and material execution.
Our competitive profiling examines players across multiple strategic archetypes. In the professional and touring audio segment, organizations such as JBL Professional and Martin Audio anchor demand for high-performance loudspeaker cabinets and enclosures built for live sound and installed systems. In the guitarist and bassist amplifier enclosure space, U.S.-based Avatar Speakers has sustained a factory-direct model centered on premium driver integration since the early 1990s, while U.K.-based Zilla Cabs competes on bespoke, handmade construction aimed at professional musicians seeking tailored tonal and structural characteristics.
On the high-fidelity and furniture-integrated side, the landscape includes premium acoustic furniture specialists and ecosystem-driven hi-fi brands. Spectral Audio Möbel emphasizes acoustic performance and design-led hi-fi cabinet construction for premium systems. Naim Audio integrates speaker enclosures and cabinets within a broader high-fidelity ecosystem, reinforcing system-level coherence rather than standalone component positioning. Quadraspire focuses on performance-oriented audio racks and cabinets engineered to reduce resonance and enhance clarity through material selection and structural design. These players illustrate how cabinet value is increasingly framed not only as acoustic containment, but as part of an integrated listening experience, interior design aesthetic, and system architecture.
The manufacturing dimension adds another strategic layer. Woodsat Audio Technology, operating as an OEM supplier of custom wooden enclosures since 2005, reflects the continued importance of contract manufacturing and white-label capability in serving global audio brands. This OEM dynamic matters because it shapes how quickly brands can scale enclosure programs, manage cost structures, and adapt to design changes without expanding their own fabrication capacity.
Recent 2026 developments reinforce the trend toward integration, customization, and category blending. In March 2026, ADI advanced its portfolio with the launch of more than 120 new Triad amplification, home cinema speaker, and subwoofer solutions, including customizable sound options that underscore demand for configurable audio environments. In April 2026, La-Z-Boy introduced the AudioLuxe premium audio furniture line at High Point Market, integrating Klipsch sound systems into customizable cabinets. These launches are strategically significant because they signal two parallel movements: the expansion of configurable professional and home-cinema audio offerings, and the migration of high-performance audio into furniture-grade, design-conscious enclosures. Both movements influence how cabinet manufacturers and audio brands think about enclosure form factor, finish, acoustic tuning, and channel strategy.
Server Cabinet Market
Material Economics and the Cost-Performance Equation
A critical, often under-modeled dimension of cabinet strategy is raw material economics. Enclosure construction directly affects acoustic behavior, durability, manufacturing complexity, and ultimately unit cost. As of the second quarter of 2025, Baltic birch plywood in 12mm 4x8 sheet format was priced in the range of $89 to $112 across North America and Europe, while standard MDF in 18mm 4x8 sheet format ranged between $42 and $58 in the same markets. That spread is not merely a procurement detail. It is a strategic variable that influences product tiering, margin architecture, and supplier negotiation leverage.
Industry data from early 2026 reinforces why MDF remains the preferred baseline for many speaker cabinet applications. Its consistent density and acoustic damping properties make it attractive for controlled enclosure performance, while its lower material cost, typically 30% to 40% below birch plywood, supports more favorable cost structures at scale. At the same time, premium and design-forward applications continue to justify higher-cost substrate choices when tonal character, furniture-grade aesthetics, or structural rigidity are differentiated value propositions. The strategic implication is clear: material selection is increasingly a portfolio decision rather than a single-specification rule. Companies that map substrate economics to application requirements, target price points, and regional sourcing conditions will have more flexibility to protect margins while meeting performance expectations.
Why This Research Matters for 2026 Planning Cycles
The 2026 planning cycle demands intelligence that can be used, not just read. Market momentum is evident, but momentum alone does not define where to invest, which applications to prioritize, or how to position against concentrated incumbents and agile specialists simultaneously. This report is built to convert growth signals into strategic action by connecting market sizing, segmentation logic, competitive behavior, and material cost dynamics into one coherent analytical environment.
By grounding the narrative in verified historical performance and extending it through a structured 2026–2032 forecast, the research gives leaders a defensible basis for scenario planning. The market’s projected progression from $1,926.79 million in 2026 to $2,718.95 million in 2032 provides a macro frame, while the segmentation, competitive, and material insights provide the executional detail necessary to interpret that frame in operational terms. This is the difference between knowing the market is growing and knowing where the growth is structurally coming from, which players are shaping it, and which cost and design variables will determine whether a company captures value or merely competes in it.
Positioning for informed strategic action
The audio cabinets market is not simply expanding; it is recalibrating around integration, customization, material economics, and application-specific performance demands. In that environment, the organizations that thrive will be those that pair growth awareness with disciplined strategic segmentation, competitive intelligence, and cost-aware design strategy. This research is designed to provide that foundation, giving executives and operational leaders a credible, detailed, and decision-ready view of the market landscape as they plan for 2026 and the years ahead.
To access the full segmentation detail, regional demand analysis, complete competitive profiles, and extended forecasts underpinning this overview, we invite you to explore the complete report on our website. The summary presented here is intended to establish the strategic context and analytical rigor of the study; the full intelligence package provides the comprehensive data architecture required for precise planning, investment evaluation, and competitive positioning across the 2026–2032 forecast period.
For detailed analysis of this topic, please visit the official page: Audio Cabinets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com