

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Machinery & Automotive
Zero-Turn Mowers Market: Why 6.92% CAGR Signals Commercial Landscaping Shift
By pmarketresearch, 2026-09-21
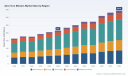
Strategic Trends & Commercial Opportunities in the Zero-Turn Mowers Market
The global zero-turn mowers market has evolved from a specialized commercial tool into a mainstream landscaping solution, driven by labor economics, technological maturation, and shifting regulatory expectations. Over the 2020-2025 period, market revenue expanded from approximately USD 163 million to over USD 215 million, reflecting a compound annual growth rate of 6.92 percent through the 2026-2032 forecast horizon. This trajectory signals a market that is no longer defined by incremental hardware updates but by structural shifts in how turf care is delivered, purchased, and operated. For executives and investors, the opportunity lies not in chasing volume alone but in aligning product strategy, supply chain posture, and commercial models with the forces reshaping the sector.
Market Snapshot & Core Challenges
Zero-turn mowers have consolidated their position as the productivity engine for both commercial landscaping operations and expanding residential user bases. The addressable market spans a wide spectrum of operator profiles, from municipal parks and sports field contractors to homeowners managing larger properties or high-accent turf. Revenue growth has been consistent across cycles, but the pace and composition of demand are increasingly uneven. The market is moving toward higher total value capture, yet that growth is uneven across segments and geographies, reflecting divergent purchasing power, service infrastructure, and regulatory maturity.
Three challenges define the current inflection point. First, talent scarcity is reshaping commercial purchasing behavior. Qualified operators remain difficult to recruit and retain, and the industry’s reliance on skilled labor is becoming a binding constraint on scaling services. Second, emission and noise regulations are no longer regional footnotes; they are becoming design imperatives, particularly in markets where local authorities and large institutional buyers increasingly expect lower-emission equipment fleets. Third, input cost volatility, especially in steel and precision components, is compressing manufacturing margins and forcing companies to reconsider pricing architecture, build-to-order flexibility, and inventory strategies.
These pressures are not isolated. They interact with demand-side expectations for faster cut times, cleaner operation, and lower total cost of ownership. As a result, the market is transitioning from a hardware-centric competition to a system-level contest that includes support networks, operator training, maintenance economics, and compatibility with emerging power sources.
Key Drivers Reshaping the Market
Technology Innovation and Breakthroughs
Product development is increasingly focused on reducing operator fatigue, improving cut consistency, and expanding the applicability of zero-turn platforms beyond traditional turf. Recent model introductions demonstrate a pattern: redesigned cutting decks, suspension and operator-comfort upgrades, and broader width options are being paired with drivetrain refinements that improve maneuverability in tight or irregular sites. These hardware gains are increasingly complemented by options that support autonomous or semi-autonomous operation, particularly in commercial settings where consistent routing and reduced supervision translate into measurable productivity gains.
The significance of this trend goes beyond feature checklists. For commercial users, productivity gains directly offset labor constraints; a machine that reduces mowing time per acre or minimizes rework increases the revenue potential of each operator hour. For residential users, comfort and ease of use influence purchase decisions, especially as ownership replaces rental or service-based models in expanding suburban lots and estate properties. Companies that can translate engineering improvements into demonstrable time savings and lower operating friction are positioned to capture premium demand and reduce price sensitivity.
Policy and Regulatory Environment
Regulatory momentum around small off-road engines is accelerating the shift toward lower-emission and zero-emission platforms. Jurisdictions have moved beyond advisory guidance to enforceable standards, and the implications are cascading through procurement cycles, dealer readiness, and product roadmaps. For manufacturers and commercial fleet operators, compliance is no longer a backward-looking cost center; it is a forward-looking competitive lever that can shape customer preference, service expectations, and site access.
PW Consulting Automotive & Machinery Research Center
At the same time, emission standards are interacting with public-sector and institutional purchasing. Large parks, school campuses, and corporate grounds increasingly align equipment choices with sustainability targets, which makes cleaner-power options commercially relevant even where total acquisition cost remains higher. The result is a bifurcated market dynamic: buyers in regulated or sustainability-sensitive environments are willing to absorb transition costs, while other segments remain highly price-aware. This divergence creates both opportunity and planning risk for suppliers that must manage multiple product pathways without fragmenting their service support.
Automatic Lawn Mower Market
Demand-Side Shifts in Consumer and Business Behavior
Demand is being reshaped by two reinforcing behaviors. On the commercial side, landscape contractors are prioritizing equipment that improves throughput and reduces reliance on large crews. The broader landscape services market’s scale underscores why this matters: mowing remains a high-frequency, labor-intensive activity, and any equipment that increases acres covered per shift directly improves margin potential in a labor-constrained environment. On the residential side, buyers are increasingly treating zero-turn mowers as long-term capital assets rather than discretionary purchases, weighing storage feasibility, maintenance burden, and resale value alongside cutting performance.
Lawn Mower Market
This shifting behavior has strategic implications. Commercial buyers are more willing to invest in higher-upfront equipment if it reduces recurring labor costs and improves scheduling reliability. Residential buyers, meanwhile, are becoming more selective about width, storage footprint, and comfort features, especially where property layouts are irregular or smaller than the widths traditionally favored by commercial setups. The practical takeaway is that “one size fits most” strategies are losing ground to segment-specific value propositions that address time savings, operator experience, and total cost of ownership.
Supply Chain and Cost Structure Dynamics
Input costs remain a persistent source of uncertainty. Steel pricing, in particular, has repeatedly shown up in financial disclosures as a meaningful factor in production expenses, and the sensitivity is heightened because zero-turn mowers incorporate substantial structural steel in decks, frames, and reinforcement points. This cost backdrop is encouraging a more disciplined approach to bill-of-materials design, sourcing diversification, and margin management.
Beyond raw materials, the supply chain conversation is increasingly about responsiveness and modular design. Companies that can offer broader width configurations, interchangeable deck options, and simplified service architectures may reduce fulfillment complexity while improving dealer and operator satisfaction. At the same time, geographic concentration in manufacturing and component sourcing continues to create exposure to logistics disruptions and regional input shocks. For buyers and investors, the key signal is whether suppliers are building cost structures that can absorb volatility without eroding product availability or after-sales support quality.
Competitive Landscape and Leading Strategies
The market is characterized by a mix of broad-portfolio incumbents and specialized commercial manufacturers, each pursuing distinct strategic positions. Deere & Company maintains a comprehensive residential and commercial lineup, emphasizing integrated attachments, hydrostatic drives, and commercial productivity in the ZTrak family. Toro Company has built a strong commercial identity with TimeCutter and Titan series products that prioritize transmission durability, structural reinforcement, and operator comfort features tailored to professional workflows. Husqvarna Group continues to broaden its residential and commercial presence with series focused on comfort upgrades, durability, and consistent cutting performance, reflecting an emphasis on repeatable operator experience across segments.
Honda Power Sports & Products has pushed into battery-powered zero-turn platforms with ProZision models in both manual and autonomous configurations, signaling a strategic emphasis on professional durability combined with cleaner-power options. Exmark Manufacturing Company remains highly focused on commercial zero-turn products, leveraging patented deck designs, suspension systems, and productivity-oriented configurations for professional use. Scag Power Equipment pursues a similar commercial orientation but with an explicit emphasis on dealer-supported service and durability as core differentiators. Cub Cadet targets residential and small commercial applications with wide cutting widths and hydrostatic drives, while Ariens Company balances residential and commercial offerings with an emphasis on comfort and professional-grade durability. Kubota Corporation adds another dimension with commercial zero-turn platforms built around engine and deck systems aimed at professional landscaping and turf applications.
The competitive differentiation is becoming less about brand presence and more about ecosystem fit. Leading players are distinguishing themselves through three overlapping advantages: product architecture that matches segment-specific productivity needs, dealer and service networks that reduce downtime risk, and portfolio breadth that allows customers to standardize across multiple site types. Companies that can deliver consistent performance across varied terrain while maintaining manageable maintenance complexity are gaining trust in commercial procurement cycles, where equipment failure directly affects revenue.
The market structure is evolving along two paths. Consolidation pressure exists where scale, parts commonality, and dealer reach create advantages in cost management and service coverage. At the same time, segmentation is intensifying as manufacturers tailor products to width preferences, power-source choices, and usage intensity. New entrants and technology-forward initiatives are most likely to succeed by targeting specific pain points—autonomous assistance, battery-platform readiness, or specialized commercial deck performance—rather than attempting to compete broadly on price alone. The practical implication is that competitive advantage will increasingly depend on matching product roadmaps to operator economics and purchasing criteria, not simply launching more models.
Future Trends and Commercial Opportunities
Broader Adoption of Lower-Emission and Battery-Ready Platforms
Over the next few years, the share of new zero-turn mowers designed with reduced-emission or battery-compatible architectures is likely to keep rising, particularly in regions with stricter engine standards and among large commercial buyers with sustainability targets. This trend creates opportunities for manufacturers that can offer credible product transitions without sacrificing commercial productivity. Battery-ready platforms, improved energy management, and support infrastructure for charging or battery swap workflows can become differentiators in fleet sales and institutional procurement.
The commercial opportunity lies in designing for transition, not just compliance. Buyers want equipment that can scale with changing site requirements and operator expectations, and suppliers that can offer clear power-option pathways will be better positioned to capture replacement cycles. The risk is that premature standardization or limited charging infrastructure could slow adoption in segments that remain highly sensitive to operating flexibility and runtime.
Productivity-Dominant Purchase Logic
As labor scarcity persists in many service markets, commercial purchasing will increasingly prioritize machines that deliver measurable time savings, simpler operation, and reduced rework. Wider cutting options, improved deck designs, and comfort-focused operator interfaces will be judged against acres covered per shift, fuel or energy efficiency, and ease of maintenance. This productivity-first logic favors suppliers that can quantify operational benefits and support them with training, service, and parts availability.
For investors and manufacturers, the opportunity is to frame product value around site economics. The more clearly a machine reduces total labor dependency per acre or improves scheduling reliability, the more defensible its position in a demand environment where service providers are trying to grow output without proportionally expanding headcount. The uncertainty lies in how quickly autonomous or assisted features will move from niche demonstrations to mainstream commercial workflows, and whether customers will accept the associated training, integration, and liability considerations.
Segmented Width and Platform Strategies
Demand for width options is likely to remain fragmented because site geometry, storage limits, and operator experience vary widely across residential and commercial use. Rather than converging on a single dominant width, the market may continue to support differentiated platforms that target high-productivity commercial layouts on one end and access-sensitive residential or estate properties on the other. Manufacturers that manage width platforms efficiently—through shared components, flexible decking, and modular reinforcement—can reduce complexity while still serving distinct customer needs.
This trend creates an opportunity for portfolio discipline. Companies that can connect multiple width and deck configurations to a common service and parts ecosystem may lower lifecycle costs and improve dealer economics. The risk is overextension: maintaining too many distinct configurations without sufficient volume in each can erode margins and complicate inventory planning, especially when steel and component costs fluctuate.
Actionable Guidance for Decision-Makers
For Manufacturers and Product Strategists
Invest in product architectures that support multiple power options and width configurations without fragmenting service support. The combination of emission momentum, labor constraints, and width diversity makes modularity a strategic asset. Prioritize deck and drivetrain refinements that deliver measurable time savings in commercial use, and ensure that operator-comfort improvements are validated under real service conditions rather than treated as cosmetic enhancements. Pricing and cost strategies should assume continued steel and component volatility, so build flexibility into sourcing, bill-of-materials design, and dealer inventory planning.
For Investors and Corporate Strategists
Focus on companies that combine commercial productivity with credible service and parts ecosystems. In a labor-constrained market, equipment value is increasingly determined by uptime, ease of maintenance, and dealer responsiveness as much as by feature sets. Monitor the pace of battery and lower-emission adoption in commercial fleets, since procurement cycles and replacement timing will shape demand in ways that are not always visible in headline shipments. Be cautious about exposure to suppliers that rely on narrow product mixes or inconsistent after-sales support, as these weaknesses become more apparent when buyers prioritize total cost of ownership.
For Landscaping Operators and Procurement Teams
Evaluate zero-turn mowers against site-specific economics rather than generic feature lists. For commercial operations, prioritize machines that reduce acres-per-labor-hour and simplify maintenance workflows, and assess dealer support as part of the purchase decision because downtime directly affects revenue. For residential and estate use, balance width, storage constraints, and comfort features with long-term ownership costs, including parts availability and servicing complexity. Where emission or sustainability expectations are rising, consider power-option pathways early so equipment choices can align with future procurement requirements without forcing rushed replacements.
Next Steps for Deeper Market Intelligence
The zero-turn mowers market is entering a phase where competitive advantage will be defined by how well companies align product design, service support, and commercial models with labor economics, regulation, and segmentation realities. Broad trends provide direction, but the execution details—width strategy, power-platform timing, cost-structure resilience, and dealer ecosystem strength—determine whether a company captures value or simply participates in growth. Decision-makers who need granular segmentation data, competitive benchmarking, and scenario-based guidance for specific regions or applications will benefit from a fuller market assessment that extends beyond macro trajectory and headline dynamics. A deeper evaluation can help translate these strategic shifts into investment priorities, product roadmaps, and procurement decisions that are calibrated to the market’s next phase of development.
For detailed analysis of this topic, please visit the official page: Zero-Turn Mowers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Satellite Market Viewed Through 6.98% CAGR and 344.8 Million Regional Growth Dynamics
By pmarketresearch, 2026-09-21
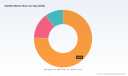
Navigating the Satellite Market: Strategic Trends and Commercial Opportunities Through 2032
The satellite industry has entered a phase of accelerated transformation, where technological maturation, regulatory modernization, and shifting demand patterns are reshaping competitive boundaries. Market valuation has expanded from approximately $163.15 million in 2020 to a projected $215.0 million in 2025, with forward estimates placing the sector at $344.8 million by 2032. This trajectory reflects a compound annual growth rate of 6.98 percent over the 2026–2032 forecast window, signaling sustained expansion rather than cyclical volatility. Such growth is not merely a function of incremental capacity additions; it represents a structural reconfiguration of how space-based infrastructure is designed, deployed, and monetized. For executives and investors, the critical question is no longer whether the market will grow, but which subsegments, geographies, and business models will capture disproportionate value as the ecosystem matures.
Behind the headline figures lies a more complex reality. The industry is navigating several inflection points that will determine competitive outcomes over the next half decade. Manufacturing throughput and component scaling remain pressing constraints, particularly as constellation architectures grow in size and operational complexity. Regulatory frameworks are evolving from prescriptive limits to performance-based models, creating both compliance flexibility and new coordination challenges across operators. Additionally, the economics of space deployment are shifting as launch cadence increases and reusable platforms reduce per-kilogram costs, yet these gains are unevenly distributed across suppliers and mission types. These dynamics are not isolated headwinds; they are interconnected forces that will separate agile, vertically integrated players from those reliant on legacy supply chains or static service models.
Key Drivers Reshaping the Satellite Landscape
Technological Innovation and Mission Architecture Evolution
The shift toward proliferated low Earth orbit architectures is fundamentally altering satellite design philosophy. Rather than relying on a small number of high-value, long-lifecycle platforms, operators are increasingly deploying modular, software-defined constellations that prioritize rapid iteration, in-orbit reconfigurability, and scalable manufacturing. This architectural transition is supported by advances in optical inter-satellite links, autonomous orbital maneuvering, and standardized payload interfaces, which collectively reduce integration lead times and improve network resilience. Recent product introductions illustrate this trajectory: the deployment of direct-to-cell broadband satellites in early 2026 expanded emergency and consumer connectivity capabilities without requiring ground terminal upgrades, demonstrating how payload innovation can unlock adjacent service markets. For manufacturers and system integrators, the opportunity lies in designing platforms that accommodate frequent software updates, cross-constellation interoperability, and rapid payload swaps, rather than optimizing solely for unit cost reduction.
Regulatory Modernization and Spectrum Coordination
Policy frameworks are transitioning from rigid emission limits to performance-based spectrum sharing models, a shift that carries significant implications for network planning and capital allocation. In early 2026, regulators adopted a modernized framework for non-geostationary and geostationary spectrum sharing in key broadband bands, replacing legacy interference thresholds with criteria tied to actual network performance. This approach grants operators greater flexibility in orbital slot utilization and frequency coordination, but it also raises the analytical burden for compliance strategy and interference mitigation. Parallel adjustments, including differentiated licensing structures for small versus large constellations and clarified end-of-life deorbit obligations, are reshaping entry barriers and lifecycle cost assessments. Companies that invest early in spectrum strategy, orbital debris management, and regulatory engagement will secure faster deployment timelines and lower long-term operational risk, while those treating compliance as a afterthought may face costly redesigns or licensing delays.
Demand-Side Shifts Across Commercial and Government Sectors
Demand patterns are diversifying beyond traditional communications and Earth observation use cases. Enterprise connectivity requirements are expanding into maritime, aviation, remote industrial operations, and mobile platforms, driven by the need for resilient backhaul and real-time telemetry in environments where terrestrial infrastructure is impractical. Simultaneously, government and defense procurement is emphasizing rapid delivery, proliferated architectures, and multi-orbit mission flexibility, reflecting a strategic preference for distributed assets over concentrated, high-cost platforms. Contract activity in early 2026 highlighted this dual demand stream: significant delivery milestones for transport-layer satellites supporting government programs coincided with finalized commercial constellation agreements, indicating that public and private capital are converging on similar architectural principles. For service providers and platform suppliers, the strategic implication is clear: product roadmaps must accommodate both high-reliability mission requirements and cost-sensitive commercial scaling, often within the same architectural family.
Supply Chain Dynamics and Manufacturing Scale-Up
The economics of satellite production are being recalibrated as demand volume increases and component standardization gains traction. Industry reporting from mid-2025 noted a 17 percent rise in satellite manufacturing revenue alongside a dominant U.S. market share, underscoring how regional capability concentration and supply chain maturity can accelerate deployment. At the same time, exporters and suppliers are navigating evolving trade controls, with certain spacecraft and servicing items experiencing reduced licensing friction for select partner markets. These shifts create a window for suppliers that can deliver qualified subsystems at scale, maintain stringent quality assurance, and align production schedules with constellation deployment cadence. Cost structure advantages will increasingly accrue to organizations that secure long-term subsystem agreements, invest in automated assembly and test processes, and mitigate single-source dependencies for critical components such as propulsion modules, power systems, and phased-array payloads.
Competitive Landscape and Strategic Positioning
Established Systems Integrators and Platform Leaders
Large aerospace and defense primes continue to anchor the market through comprehensive system integration capabilities, deep mission engineering expertise, and established relationships with government and commercial buyers. Their strategic positioning typically emphasizes end-to-end delivery spanning bus platforms, payloads, ground interfaces, and mission operations, which reduces customer integration risk and supports complex, multi-year programs. Differentiators in this tier include advanced manufacturing scale, secure production environments, and the ability to manage stringent reliability and certification requirements. These companies are increasingly adapting to proliferated architectures by offering standardized platforms, modular payload integration, and faster delivery cycles, while preserving their advantage in high-complexity missions where performance margins and compliance rigor remain paramount.
Specialized Operators and Connectivity Enablers
A distinct tier of operators and subsystem specialists is expanding the commercial surface area of the market by focusing on constellation services, mobile tracking systems, broadband platforms, and end-to-end connectivity solutions. Their competitive edge often stems from vertical service integration, rapid product iteration, and close alignment with specific user segments such as mobile communications, remote enterprise networking, and IoT telemetry. Recent commercial activity illustrates this focus: mobile tracking antenna providers have secured advance orders for LEO and MEO tracking systems, signaling growing demand for vehicle-based and transportable connectivity that can follow dynamic orbital pathways. Similarly, broadband platform operators are extending service reach through direct-to-device capabilities and ecosystem partnerships that reduce reliance on specialized ground hardware. These players are reshaping buyer expectations around deployment speed, service flexibility, and total cost of ownership, forcing traditional suppliers to respond with more agile commercial terms and modular offerings.
TV Market
Market Evolution: Consolidation, Differentiation, and New Entrants
The competitive structure is moving toward a hybrid model in which large integrators, specialized operators, and nimble platform startups coexist, each competing on different axes of value. Consolidation is likely where scale economics, spectrum access, and multi-orbit capability become decisive, particularly for operators seeking to amortize network costs across large user bases. At the same time, differentiation is intensifying around software-defined payloads, rapid manufacturing pipelines, and niche mission solutions that address specific defense, scientific, or commercial requirements. New entrants are gaining traction by leveraging standardized bus architectures, commercial-off-the-shelf component strategies, and focused service propositions that bypass the cost structures of legacy programs. The net effect is a market where incumbents must accelerate product cycle times and expand commercial flexibility, while entrants must prove reliability, supply continuity, and mission-grade performance to secure sustained contracts. Strategic positioning will increasingly depend on how effectively companies balance scale with specialization, and how quickly they can translate technical capability into deployable, revenue-generating service models.
Forward Outlook: Three Defining Trends for the Next Three to Five Years
The first defining trend is the acceleration of multi-orbit, software-defined networks that blend LEO, MEO, and GEO assets into coordinated service layers. As spectrum sharing becomes performance-based and inter-satellite linking matures, operators will be able to route traffic dynamically across orbits, improving latency, coverage, and resilience without proportionally increasing satellite count. This creates commercial opportunities in network orchestration, payload virtualization, and cross-orbit service integration, while challenging suppliers to deliver interoperable interfaces and secure data-handling architectures. The primary risk is coordination complexity: as networks multiply, interference management, orbital slot allocation, and standards alignment will require sustained industry cooperation and proactive regulatory engagement.
LEO Satellite Market
The second trend is the continued pressure on manufacturing throughput and subsystem standardization as constellation programs scale. Buyers will increasingly favor suppliers that can demonstrate repeatable production cycles, qualified component inventories, and transparent lead-time commitments. Companies that invest in automation, modular test flows, and long-term subsystem partnerships will secure margin stability and preferential positioning in large-scale procurements. The uncertainty lies in supply chain concentration and export control variability; shifts in licensing scope or component availability can quickly alter cost assumptions and deployment schedules, making diversification and contingency planning essential.
The third trend is the expansion of service monetization beyond traditional bandwidth leasing into vertical-specific connectivity, mobile tracking, and integrated telemetry solutions. Direct-to-device capabilities, transportable antenna systems, and end-to-end platform offerings are lowering adoption barriers for enterprise, maritime, aviation, and government users who previously faced high terminal costs or limited coverage. This opens addressable market growth for operators and equipment suppliers that can package hardware, software, and service operations into unified solutions. The commercial risk is fragmentation: as more players introduce niche offerings, differentiation may erode unless companies can sustain clear performance advantages, reliable service-level commitments, and scalable support infrastructure.
Strategic Guidance for Decision-Makers
For satellite manufacturers and subsystem suppliers, the priority is to align product roadmaps with proliferated, multi-orbit demand while protecting margin through standardization and supply continuity. Investing in modular platform design, repeatable assembly processes, and qualified component pipelines will reduce integration risk and position suppliers for large-scale constellation awards. Concurrently, proactive engagement on spectrum coordination, end-of-life compliance, and export licensing will shorten deployment timelines and reduce operational uncertainty. Organizations that treat these capabilities as core competitive assets, rather than ancillary compliance tasks, will be better equipped to capture value as procurement cycles accelerate.
For investors and strategic capital allocators, the most resilient opportunities will likely emerge where technical capability, regulatory readiness, and scalable commercial models intersect. Due diligence should prioritize suppliers and operators with demonstrated manufacturing throughput, clear spectrum and licensing strategies, and service architectures that can adapt across orbit regimes and user segments. Allocation decisions should weigh not only unit economics and contract pipelines, but also exposure to supply concentration, compliance evolution, and standards fragmentation. Capital deployed into companies that can harmonize hardware scale with software-defined service delivery is more likely to benefit from the structural expansion projected through the end of the decade.
PW Consulting Automotive & Machinery Research Center
For procurement leaders and enterprise buyers, the immediate objective is to evaluate total cost of ownership across hardware, service, and lifecycle dimensions rather than focusing narrowly on upfront terminal or bandwidth pricing. Engaging suppliers with proven multi-orbit interoperability, mobile and transportable connectivity options, and transparent service-level frameworks will reduce integration risk and improve resilience in remote or mobile operations. Buyers should also monitor regulatory and licensing developments that affect spectrum availability, deorbit obligations, and export eligibility, as these factors can materially influence deployment timing and long-term operating costs.
Detailed segmentation data, competitive benchmarking, and customized scenario modeling can further sharpen these decisions by translating market-level trends into segment-specific priorities and investment thresholds. Access to comprehensive research supporting the trajectory from 2026 through 2032 can help decision-makers validate assumptions, compare supplier positioning, and align procurement or capital strategies with the most probable growth pathways.
For detailed analysis of this topic, please visit the official page: Satellite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Mask Inspection Equipment Market: What 5.9% CAGR Reveals About Asia Pacific Dominance
By pmarketresearch, 2026-09-21
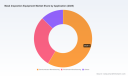
Strategic Trends and Commercial Opportunities in the Mask Inspection Equipment Market
The mask inspection equipment market has entered a phase of steady but structurally significant expansion, with global revenue projected to grow from approximately $3.25 billion in 2025 to nearly $4.79 billion by 2032, reflecting a compound annual growth rate of 5.9 percent over the forecast period. This trajectory is not merely a continuation of historical growth patterns but rather the result of converging technological, regulatory, and manufacturing shifts that are reshaping how photomasks are qualified, inspected, and deployed across advanced semiconductor workflows. While the headline numbers suggest predictable expansion, the underlying dynamics reveal a market where competitive positioning, technology selection, and geographic exposure are being redefined at an accelerated pace.
The baseline growth is anchored in the relentless scaling of semiconductor production and the corresponding need for higher-fidelity mask qualification. As process nodes shrink and design complexity increases, the margin for error in mask defect detection narrows dramatically. Inspection equipment that once served as a quality gate is now embedded deeper into the manufacturing and merchant mask supply chain, influencing throughput, yield learning cycles, and time-to-tape-out. The market has also benefited from broader capital expenditure cycles that prioritize equipment reliability and defect management over incremental cost optimization. Yet this growth is uneven across technology platforms and applications, and participants that treat inspection as a commoditized ancillary step are increasingly exposed to margin compression and displacement risk.
Three interconnected challenges define the current inflection point. First, the transition toward extreme ultraviolet lithography and advanced multi-patterning workflows has raised the bar for defect sensitivity, pattern placement accuracy, and inspection throughput. Equipment must now resolve sub-wavelength anomalies while maintaining cycle times that do not disrupt high-volume production schedules. Second, the regulatory environment has become a material factor in market access and product deployment. Stored program controlled equipment used for mask, reticle, and pellicle inspection has been designated as a restricted item under the Export Control Reform Act, and certain mask inspection equipment will fall under the Direct Product Rule beginning January 2026. These measures affect cross-border technology transfer, service models, and the strategic calculus of companies operating across multiple jurisdictions. Third, the competitive structure remains relatively fragmented at the top, with the top three players accounting for roughly 24.6 percent of revenue and the top five reaching about 26.2 percent. This moderate concentration suggests room for differentiation, but also indicates that scale advantages, technology leadership, and ecosystem integration will determine which firms can defend pricing power and win premium deployments.
Optical and E-Beam Inspection Redefined by Node Scaling and EUV Readiness
Technological innovation remains the most powerful demand catalyst, but its impact is now concentrated in specific inspection modalities that align with advanced node requirements. Optical mask inspection continues to hold the largest revenue share, reflecting its broad applicability across die-to-die and die-to-database workflows, mature node qualification, and high-throughput review processes. However, the strategic value of optical platforms is shifting from general-purpose defect detection toward systems that combine high sensitivity with faster pattern recognition, better database matching, and tighter integration with mask shop data pipelines. E-beam inspection, while smaller in total revenue, is gaining strategic relevance in EUV mask quality control and reticle analysis, where the ability to detect subtle defects and characterize pattern placement at advanced feature sizes is increasingly non-negotiable. The presence of both optical and e-beam platforms in the market underscores a broader truth: the winning architecture is no longer defined by a single technology but by the ability to match inspection modality to node, volume, and defect criticality.
Recent product activity illustrates how vendors are translating technology roadmaps into commercial positioning. In December 2025, Lasertec Corporation introduced the MAGICS Series M9750 and M9751 mask blank inspection and review systems designed for next-generation leading-edge semiconductors and advanced EUV mask blanks. This launch signals a deliberate push into the mask blank and EUV mask quality control segment, where sensitivity, repeatability, and compatibility with actinic inspection requirements are becoming differentiators. Around the same period, HTL Co., Ltd. reported the first acceptance of its DIONE-CIS photomask inspection system in the United States, with the system introduced into mass production at a major merchant mask shop in July 2025. This milestone is notable not only for expanding the geographic footprint of a Japan-based equipment supplier but also for demonstrating that merchant mask operations are increasingly open to newer inspection platforms when they can demonstrate reliability, throughput, and integration into production workflows. Together, these developments reflect a market where innovation is being validated through real production adoption rather than specification benchmarks alone.
Semiconductor Inspection Equipment Market
Regulation as a Market Reshaping Force, Not Just a Compliance Task
Policy and export control developments are no longer peripheral considerations; they are becoming structural inputs into commercial strategy. The Federal Register listing of stored program controlled equipment for mask, reticle, and pellicle inspection as a restricted item under the Export Control Reform Act introduces new considerations for cross-border sales, localization of support, and technology migration paths. More immediately, the Export Administration Regulations placing certain mask inspection equipment under the Direct Product Rule effective January 2026 create a compliance threshold that affects product classification, customer onboarding, and the ability to serve specific end markets without localized solutions or adjusted service models.
For equipment providers, the regulatory shift amplifies the importance of supply chain transparency, documentation readiness, and regional deployment strategies. Companies that rely heavily on cross-border technology flows or centralized service architectures may need to revisit how they structure manufacturing, software delivery, and field support to remain accessible in restricted or controlled contexts. For buyers, especially merchant mask shops and semiconductor manufacturers operating across multiple regions, the changing rules raise questions about equipment sourcing flexibility, long-term service continuity, and the risk of deployment delays if classification or licensing requirements are not addressed early in procurement cycles. The practical implication is that regulatory alignment is increasingly part of the value proposition, not a separate compliance checkbox. Vendors that can offer predictable deployment pathways and buyers that incorporate export control considerations into technology roadmaps will be better positioned to avoid disruption.
Demand Shifts in Semiconductor and Photomask Manufacturing
On the demand side, mask inspection growth is being shaped by how semiconductor manufacturers and photomask producers allocate capital and prioritize defect management. In semiconductor manufacturing, inspection equipment supports yield learning, advanced node qualification, and the operational discipline required to sustain high-volume production with tighter process controls. In photomask manufacturing, demand is driven by the need to supply leading-edge masks to multiple downstream customers, where defect rates, turnaround times, and consistency across mask lots directly influence merchant competitiveness. The application split in the market reflects this dual engine: semiconductor manufacturing represents the largest demand pool, while photomask manufacturing remains a critical downstream segment where inspection capabilities influence both quality and speed of mask supply.
Behavioral changes on the demand side are also evident in how buyers evaluate inspection tools. Decision-makers are increasingly focused on total workflow impact rather than isolated inspection performance. This includes integration with existing review and disposition processes, the ability to reduce false positives, alignment with mask shop throughput targets, and the flexibility to handle mixed technology nodes as product portfolios evolve. At the same time, the broader production environment is encouraging a more risk-aware posture. As manufacturers manage complexity across advanced packaging, multi-patterning, and EUV-related workflows, inspection is being treated as a lever for reducing downstream rework and improving predictability in mask qualification. This shift raises the stakes for equipment suppliers to demonstrate production-grade reliability and clear return on operational investment, rather than relying solely on technical specifications.
Cost Structures, Supply Chains, and the Commercial Logic of Differentiation
Cost and supply chain dynamics are reinforcing the move toward differentiated inspection solutions. Inspection equipment is not only a capital purchase; it is part of a broader operating cost structure that includes maintenance, software updates, service access, and production downtime risk. As buyers confront the need to maintain uptime while meeting higher inspection standards, the relative cost of lower-quality inspection or slower disposition workflows becomes more visible. This environment favors vendors that can reduce total cost of ownership through more efficient inspection cycles, stronger system reliability, and services that minimize operational friction. It also favors equipment strategies that align with the buyer's production mix, since one-size-fits-all platforms often struggle to match the nuances of advanced EUV blank review, high-volume optical inspection, or specialized reticle analysis.
Supply chain resilience is increasingly part of the purchasing calculus. Buyers are attentive not only to product capability but also to the predictability of delivery, the stability of software and service support, and the vendor's ability to operate consistently across regions with differing regulatory conditions. This is particularly relevant as export controls and restricted-item classifications introduce new layers of complexity into equipment deployment. In practice, the market is rewarding combinations of technical performance and commercial reliability. Equipment that can be deployed with fewer integration surprises, supported with clear service pathways, and aligned with local compliance realities is gaining an advantage that is difficult for competitors to replicate purely through specification improvements.
Competitive Positioning and the Evolution of Market Structure
The competitive field in mask inspection equipment is anchored by a mix of established semiconductor metrology leaders, specialized mask inspection providers, and regional players expanding their footprint through targeted product acceptance and production deployments. The landscape is characterized less by sudden disruption than by incremental but meaningful differentiation across technology portfolios, application focus, and geographic execution.
Leading Players and Their Strategic Anchors
KLA Corporation remains a central figure in semiconductor metrology and inspection, anchored by a comprehensive portfolio that spans reticle defect inspection systems for mask shops and EUV reticle quality control. Its positioning reflects breadth and integration, with an emphasis on serving mask shops and semiconductor manufacturers that require end-to-end inspection coverage across multiple technology nodes. Applied Materials continues to leverage its mask inspection systems, including optical and e-beam technologies, to support advanced node mask qualification and defect detection. Its strategic advantage lies in the ability to connect mask inspection with broader process and qualification ecosystems, which is increasingly valuable as mask quality becomes more tightly linked to downstream patterning outcomes.
Lasertec Corporation has carved a specialized position in actinic EUV mask inspection and high-sensitivity DUV mask blank and review systems. Its recent launch of the MAGICS Series M9750 and M9751 systems indicates a focus on next-generation mask blank inspection and EUV readiness, areas where sensitivity and process compatibility matter deeply. Camtek Ltd. contributes automated optical inspection capabilities for photomask defect inspection, including die-to-die and die-to-database applications, reinforcing a flexible optical inspection stance that aligns with mask shop review and qualification requirements. Hitachi High-Tech Corporation supports e-beam inspection and CD-SEM solutions targeted at EUV mask defect detection and reticle analysis, adding depth in electron-beam-based characterization where defect sensitivity and pattern analysis are critical. Onto Innovation delivers optical and e-beam inspection tools that support mask and reticle defect and pattern placement analysis, broadening the field of vendors that combine multiple inspection modalities. HTL Co., Ltd. rounds out the competitive set with automatic optical inspection systems for semiconductor photomask defect inspection, and its recent acceptance of the DIONE-CIS system in a U.S. merchant mask shop highlights the growing role of focused AOI providers in production environments.
Differentiation, Integration, and the Shape of Future Competition
The strategic patterns emerging across these companies point to several differentiation pathways. One is technology specialization, where vendors concentrate on particular inspection modalities or workflow segments, such as actinic EUV inspection, mask blank review, or e-beam reticle analysis. A second is integration and portfolio breadth, where the value lies in offering coverage across optical and e-beam platforms and aligning inspection with broader metrology or qualification workflows. A third is execution in production acceptance, where commercial momentum is built through successful deployment in merchant mask shops and semiconductor manufacturing environments, as illustrated by recent milestones in the United States and in advanced mask blank systems.
PW Consulting Automotive & Machinery Research Center
The market structure is likely to evolve through a combination of consolidation pressure and continued differentiation. Moderate concentration at the top suggests that scale alone is not yet decisive, but it also means that competitive advantages must be sustained through technology leadership, reliable production deployments, and strong service and compliance execution. New entrants and regional specialists can still gain traction by solving specific inspection problems well, especially where merchant mask shops and advanced node manufacturers seek alternatives or complementary capabilities. At the same time, the regulatory environment and the increasing complexity of advanced mask workflows may raise the bar for cross-border expansion and long-term support, making it more difficult to compete on price alone without a credible technology and service foundation.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
The next phase of market development is likely to be defined by tighter alignment between inspection technology, regulatory realities, and production economics. Three trends are particularly important for strategic planning.
Trend 1: Inspection Platforms Will Be Selected by Workflow Fit, Not by Technology Category Alone
As advanced nodes and EUV-related mask workflows become more central, buyers will increasingly choose inspection systems based on how well they fit a specific mask shop workflow or semiconductor qualification process. Optical and e-beam platforms will continue to coexist, but the winning deployments will be those that match defect sensitivity, throughput, database matching, and review integration to the actual production mix. This trend creates opportunities for vendors that can clearly map their systems to node-specific requirements and for buyers that evaluate inspection as part of a broader yield and throughput strategy rather than as a standalone purchase.
Trend 2: Export Controls and Restricted-Item Classification Will Influence Sourcing and Deployment Architecture
The regulatory trajectory points toward more deliberate structuring of equipment sales, service, and software delivery across regions. With stored program controlled mask inspection equipment designated as a restricted item and certain equipment placed under the Direct Product Rule beginning in early 2026, market participants will need to account for classification, documentation, and regional deployment feasibility earlier in the buying process. This trend is likely to benefit vendors with strong compliance readiness and clear regional execution models, while raising the cost of complexity for buyers that depend on highly cross-border, centralized procurement or service structures. Commercial opportunities will emerge for solutions that reduce deployment friction and make long-term support predictable across jurisdictions.
SMT Inspection Equipment Market
Trend 3: Merchant Mask Operations and Advanced Node Qualification Will Drive Differentiated Demand Growth
Demand growth will not be uniform. Merchant mask operations seeking to support multiple downstream customers with consistent quality and faster turnaround are likely to push for inspection systems that can handle high-mix, production-grade workloads. At the same time, advanced node qualification will continue to favor systems that provide superior defect sensitivity and pattern analysis for EUV-related mask quality control and reticle review. This divergence opens space for specialized growth in mask blank inspection, EUV mask review, and automated optical inspection platforms that have proven themselves in real production settings. The commercial opportunity lies in aligning product roadmaps and service models with these distinct demand profiles rather than treating mask inspection as a monolith.
Potential risks remain. The regulatory environment could tighten further or create unexpected deployment constraints for certain product configurations or regions. Technology transitions in lithography and mask workflows may shift inspection requirements faster than equipment roadmaps can adapt, particularly if defect sensitivity thresholds or throughput expectations escalate. In addition, competitive pressure from new product acceptances and expanding regional capabilities could compress margins for vendors that rely on legacy platforms without clear workflow differentiation. Market participants should therefore treat flexibility, compliance readiness, and production validation as strategic assets, not optional enhancements.
Strategic Implications for Decision-Makers
For manufacturers and mask shop operators, the priority is to align inspection capability with production objectives and regulatory realities. Investments should be evaluated against workflow fit, defect sensitivity needs, throughput impact, and the ability to sustain long-term service and software support across relevant regions. Preference should be given to platforms that have demonstrated production acceptance and that can reduce false positives, accelerate disposition, and integrate cleanly with existing review processes. Procurement timing also matters: as export control rules take effect and equipment classification becomes more consequential, early engagement with vendors on deployment structure and compliance readiness can reduce the risk of delays or sourcing constraints.
For investors, the market offers growth supported by 5.9 percent CAGR through 2032, but the most valuable exposure will come from understanding where differentiation is real and defensible. Attention should be paid to companies that are expanding into advanced mask blank inspection, EUV-related reticle control, or high-sensitivity review workflows, as well as to those that have secured meaningful production acceptance outside their home regions. Equally important is to assess how each company is positioned for regulatory complexity, since restricted-item classification and the Direct Product Rule may reshape competitiveness across geographies. The market's moderate concentration suggests that leadership is still contestable, but only for firms that can combine technology-edge, execution credibility, and commercial resilience.
For procurement teams and strategic buyers, the practical task is to treat mask inspection equipment as a long-term operational commitment rather than a specification-driven transaction. Evaluation frameworks should incorporate total cost of ownership, service continuity, software and support stability, and alignment with export control expectations. Buyers should also consider supplier diversification where appropriate, especially when multiple inspection modalities or regional deployment scenarios are involved. The more clearly a procurement strategy accounts for both technical fit and regulatory accessibility, the lower the risk of disruption as the market matures and control requirements become more embedded in equipment deployment.
The structural signals in the mask inspection equipment market are clear enough to warrant deliberate planning, but the details matter. Regional exposure, modality fit, regulatory readiness, and production-validated acceptance are increasingly the variables that separate durable positioning from short-lived momentum. For decision-makers who need granular segmentation data, competitive benchmarking, and tailored scenario analysis, the full research report provides the deeper ingredient set needed to translate these strategic trends into concrete investment, procurement, and technology roadmapping decisions.
For detailed analysis of this topic, please visit the official page: Mask Inspection Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
EVP Market at 7.2% CAGR: Why the $300M Shift to 2032 Changes EV Strategy
By pmarketresearch, 2026-09-21
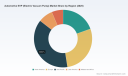
The Strategic Evolution of the Automotive Electric Vacuum Pump Market: Trends and Commercial Opportunities
The automotive electric vacuum pump (EVP) market is undergoing a structural transformation driven by electrification, tightening emissions mandates, and the growing complexity of brake and engine management architectures. As automakers transition from mechanically dependent vacuum sources to electrically actuated systems, the EVP has evolved from a peripheral auxiliary component into a critical node in vehicle safety, efficiency, and emissions compliance. The segment has expanded from approximately $116 million in 2020 to an estimated $186 million in 2025, with forward projections indicating a compound annual growth rate of 7.2 percent through 2032. This trajectory reflects more than steady demand growth; it signals a recalibration of how vehicles generate, manage, and deploy vacuum across braking, emission, and engine control functions.
For executives, investors, and procurement leaders, understanding the EVP market requires looking beyond unit sales and pricing. The segment is shaped by regulatory pressure, platform electrification strategies, supplier differentiation in adaptive control and power efficiency, and cost structures that still challenge widespread adoption. The following analysis examines the market environment, the forces shaping demand, the competitive landscape, and the strategic moves that will define the next three-to-five-year horizon.
Vacuum Pumps Market
Market Landscape and Core Challenges
The EVP market has grown consistently across the 2020 to 2025 period, reflecting steady integration into passenger and commercial vehicle architectures. The growth curve is not uniform, however. It is modulated by regional vehicle mix, electrification adoption rates, and the pace at which legacy vacuum-generating systems are replaced by electric alternatives. Asia Pacific currently represents the largest revenue pool, followed by Europe and North America, with Latin America and the Middle East/Africa contributing smaller but expanding shares. This geographic distribution mirrors broader automotive production and sales patterns, while also highlighting where regulatory pressure and electrification investment are most concentrated.
Segmentation by type reveals a market still anchored by diaphragm-type pumps, which dominate due to their mature design, reliability, and compatibility with hybrid and internal combustion platforms. Swing piston and leaf-type designs occupy meaningful but smaller positioning, often differentiated by specific efficiency, packaging, or durability requirements. Application-wise, brake booster systems remain the primary demand center, as electric vacuum generation is essential for reliable braking assist when engine-driven vacuum is unavailable or insufficient. Emission control systems and engine management systems represent secondary but strategically important application areas, where EVPs support precise vacuum-dependent processes and help reduce parasitic mechanical losses.
Three core challenges define the market’s current inflection point:
- Cost barriers and material constraints. The upfront cost of electric vacuum pumps remains a restraint, driven by raw material costs, precision manufacturing requirements, and the need for integrated control electronics. While economies of scale and design optimization are gradually easing this pressure, cost sensitivity continues to influence procurement decisions, particularly in price-competitive segments and emerging markets.
- Regulatory-driven integration complexity. New emissions and fuel economy standards are pushing EVPs from optional auxiliaries into baseline design requirements. This shift forces suppliers and OEMs to reconcile performance, packaging, thermal management, and system integration at earlier design stages, raising the stakes for supplier readiness and development lead times.
- Platform fragmentation across powertrains. The market must simultaneously serve traditional ICE applications, hybrid architectures, and increasingly electrified platforms. Each powertrain path demands different vacuum profiles, control strategies, and reliability expectations. Suppliers that can deliver adaptable EVP families with consistent performance across these environments are better positioned than those optimized for a single use case.
These challenges are not simply headwinds; they are shaping the criteria by which buyers evaluate suppliers and by which companies allocate R&D resources. The market is moving toward solutions that combine reliability, efficiency, and intelligent on-demand operation, rather than standalone vacuum generation.
Key Demand Drivers
Technology Innovation and Adaptive Control
A central driver of EVP adoption is the shift toward adaptive vacuum control and intelligent operation. Pumps are no longer expected to run continuously; instead, they are increasingly designed to respond to real-time braking demand, engine state, and hybrid/electric mode transitions. This reduces parasitic power consumption, improves brake response, and supports fuel efficiency and emissions targets. Recent product launches illustrate this direction clearly. In May 2025, Bosch introduced a new generation of electric vacuum pumps for hybrid and electric vehicles aimed at enhancing braking performance. Continental unveiled a high-performance EVP for passenger ICE platforms in Europe, emphasizing adaptive vacuum control, power efficiency, and integration with regenerative braking. Rheinmetall’s Pierburg division launched an electric vacuum pump focused on reducing CO2 emissions and enhancing hybrid and brake system performance, highlighting rapid vacuum buildup and intelligent on-demand operation. Denso also introduced a diaphragm-type EVP in the Asia-Pacific region for hybrid and ICE engines, with adaptive control intended to improve braking and fuel efficiency.
These developments point to a broader technological trend: the EVP is becoming part of a controlled, responsive system rather than a fixed-output component. Suppliers that integrate adaptive control algorithms, optimize power draw, and coordinate with brake and powertrain controllers are creating differentiation that goes beyond mechanical design. This matters for OEMs because it allows vacuum management to align with broader vehicle efficiency strategies and electrified brake architectures.
Regulatory and Emissions Mandates
Regulatory pressure is one of the most decisive forces in the EVP market. The European Union’s Euro 7 standards, taking effect in 2026, set fleet average CO2 emissions limits of approximately 49.5 g/km for passenger cars, compelling designs that eliminate parasitic mechanical losses and ensure reliable braking with lower emissions. Similar dynamics are visible in China’s National VI emissions standard and California’s Advanced Clean Cars II regulation, which encourage improved fuel efficiency through auxiliary vacuum system implementation across vehicle portfolios. At a broader level, stringent emission and fuel economy regulations are mandating electric vacuum pump integration to maintain braking reliability and reduce emissions in hybrid and electric vehicles.
These regulations affect the market in two ways. First, they expand the addressable base by making EVP integration a compliance consideration for a wider range of vehicle programs. Second, they raise the technical bar, since compliance often depends on system-level performance rather than pump-level specifications alone. Tier-1 suppliers including Robert Bosch, Denso, and Valeo are scaling compliant EVP solutions in response, reflecting the way regulation is shaping supplier roadmaps and production capacity planning. The implication for decision-makers is that EVP demand is not purely cyclical; it is structurally supported by regulatory timelines that are difficult to defer.
Demand-Side Shifts in Vehicle Architectures and Safety Expectations
On the demand side, vehicle architectures are shifting in ways that increase reliance on electric vacuum generation. As engine-driven vacuum sources become less available or less reliable in hybrid and electric contexts, EVPs provide a controllable alternative for brake boosting, emission system operation, and engine management functions. At the same time, consumer and commercial expectations around braking performance, safety, and efficiency are rising. Brake booster systems remain the dominant application because vacuum assist continues to be central to reliable braking feel and response, especially during transitions between powertrain modes.
This demand shift is not limited to passenger cars. Commercial vehicles and xEV braking systems are also creating additional application space for EVPs, particularly where consistent vacuum delivery and system compatibility are required across OEM and aftermarket use. Suppliers that can deliver consistent vacuum performance across passenger and commercial platforms are building broader portfolios that reduce program risk for buyers. The commercial side of the market often places different weight on durability and cost, so balancing performance with value is a strategic priority.
Supply Chain and Cost Structure Dynamics
The supply side of the EVP market is being shaped by material costs, manufacturing complexity, and the need for tighter integration with electronic control systems. High initial costs remain a restraint, but the same factors are encouraging design consolidation, higher production volumes in key regions, and closer collaboration between pump manufacturers and system integrators. This creates a dual dynamic: cost pressure limits rapid adoption in price-sensitive programs, while scale and integration opportunities reward suppliers that can deliver complete, validated solutions rather than stand-alone pump units.
Regional supply chains are also relevant. South Korean suppliers such as Youngshin Precision and LPR Global illustrate the growing role of cost-effective EVP series for passenger vehicles and the strategic importance of suppliers serving EV, hybrid, and high-performance applications. LPR Global, for example, has positioned itself as a primary supplier for EV and hybrid vacuum pump needs, serving a substantial share of South Korean EV makers and providing components for Kia/Hyundai applications through Valeo. Meanwhile, Advik Hi-Tech’s collaboration with Entecnia S.L.U. shows how cross-border partnerships are being used to develop advanced EVP solutions for passenger cars, commercial vehicles, and xEV braking systems. These supply-side patterns indicate that the market is not solely concentrated in traditional European hubs; regional specialists are expanding capabilities and integrating into global OEM and tier-1 networks.
Automotive Vacuum Pump Market
Competitive Landscape and Leading Strategies
The EVP market remains highly concentrated, with a small group of suppliers accounting for the majority of revenue. This concentration reflects the technical barriers to entry, the importance of validation and system integration, and the long development cycles associated with automotive component qualification. At the same time, the competitive field is not static. Incumbents are expanding their EVP portfolios to address hybrid and electric platforms, while regional specialists are gaining traction through cost efficiency, targeted applications, and partnership-based development.
Bosch continues to occupy a leading position as a manufacturer of modular EVPs for automotive brake boosters, with recent expansion into adaptive control for hybrid and electric vehicles and integration with electronic brake systems. Its strategic advantage lies in scale, system-level integration capability, and the ability to align pump development with broader braking and powertrain strategies. Continental competes on high-performance EVP solutions for passenger ICE vehicles, differentiating through adaptive vacuum control, power efficiency enhancements, and regenerative braking integration. Rheinmetall’s Pierburg division emphasizes single- and dual-stage EVPs optimized for hybrid and brake systems, with a focus on low CO2 emissions, rapid vacuum buildup, and intelligent on-demand operation. Hella develops and supplies EVPs specifically for brake booster applications, prioritizing reliable pneumatic brake boost operation in modern vehicles. These European incumbents share a common strategic theme: they are moving beyond component supply toward system-relevant performance, control, and compliance.
In parallel, regional players are carving out differentiated roles. Youngshin Precision produces cost-effective EVP series for passenger vehicles, delivering consistent vacuum delivery for both OEM and aftermarket applications. LPR Global serves as a primary supplier for EV, hybrid, and high-performance vehicles, with a strong footprint among South Korean EV makers and a role in Kia/Hyundai applications through Valeo. Advik Hi-Tech is advancing EVP production in collaboration with Entecnia S.L.U., targeting passenger cars, commercial vehicles, and xEV braking systems. Valeo functions as a recipient and integrator of EVP components, including SMVP series parts for installation in Kia and Hyundai advanced automobiles. Denso supplies diaphragm-type EVPs for hybrid and ICE engines, emphasizing adaptive vacuum control and fuel efficiency improvements. This mix of large incumbents and specialized suppliers creates a landscape where technical leadership, cost positioning, and regional supply relationships all matter.
Recent developments reinforce the pace of competitive activity. In early 2025, Advik Hi-Tech showcased a new range of automotive components at the Bharat Mobility Global Expo in New Delhi, including advanced EVPs developed with Entecnia S.L.U. for passenger and commercial braking systems. In April 2025, Pierburg launched an electric vacuum pump in Germany focused on CO2 reduction and hybrid/brake system enhancement. May 2025 saw a cluster of launches: Bosch introduced its next-generation EVP for hybrid and electric vehicles; Denso launched a diaphragm-type EVP in Asia-Pacific for hybrid and ICE engines; and Continental unveiled a high-performance EVP for passenger ICE vehicles in Europe with adaptive vacuum control and regenerative braking integration. These moves indicate that product refresh cycles are accelerating, particularly around efficiency, control, and compliance.
Looking ahead, the competitive landscape is likely to evolve along three lines. First, consolidation may continue among suppliers that can offer integrated, compliant EVP systems with validated brake and powertrain compatibility. Second, differentiation will increasingly depend on control software, efficiency, and packaging flexibility rather than mechanical design alone. Third, new entrants and regional specialists will continue to challenge incumbents in specific applications, especially where cost, local supply relationships, or commercial-vehicle specialization provide a credible edge. The market is therefore not a simple two-tier hierarchy; it is a layered ecosystem in which both global scale and application-specific expertise create value.
Future Trends and Commercial Opportunities
Trend 1: Electric Vacuum Pumps as a Compliance and Efficiency Standard
As emissions and fuel economy mandates tighten, EVPs are likely to become a more standard element of vehicle design rather than a retrofit or niche solution. This trend is strongest in regions with aggressive regulatory timelines, but it is also spreading as automakers harmonize platforms across markets. The commercial opportunity lies in suppliers and OEMs that treat EVP integration as a system-level requirement from the outset, aligning pump selection with brake architecture, powertrain mode transitions, and thermal and packaging constraints. Early integration reduces redesign risk and supports compliance without compromising performance.
PW Consulting Automotive & Machinery Research Center
Trend 2: Adaptive, On-Demand Control as the Core Value Driver
The next phase of EVP competition will likely center on intelligent control: pumps that modulate output based on real-time demand, support regenerative braking coordination, and minimize power loss. This creates opportunities for suppliers that can combine hardware and control expertise, as well as for OEMs that can leverage adaptive vacuum management to improve efficiency and braking consistency across hybrid and electric modes. The value proposition is not simply “more vacuum,” but “vacuum delivered more precisely and with less energy cost.” As brake systems become more electrified and more dependent on coordinated control, this precision will increasingly differentiate suppliers.
Trend 3: Regional Specialization and Supply Chain Diversification
The market’s geographic distribution is likely to remain uneven, but regional specialization will become more important. Asia Pacific’s scale, Europe’s regulatory intensity, and North America’s mix of passenger and commercial requirements create distinct demand profiles. At the same time, suppliers that can serve multiple regions with adaptable product families and localized support will be better positioned to manage program risk and cost. Commercial opportunities include partnerships that combine global scale with regional responsiveness, and supplier strategies that balance cost efficiency with compliance readiness. Buyers benefit when they can access both mature, validated solutions and cost-competitive alternatives for less demanding applications.
Potential risks and uncertainties remain. Cost pressures may persist if raw material and manufacturing expenses do not decline as quickly as volume scales. Regulatory timelines can shift, altering the pace at which EVP integration becomes mandatory across additional vehicle categories. Platform fragmentation may also complicate standardization, especially when OEMs pursue diverse hybrid and electric strategies simultaneously. Finally, technological change in brake systems and electrification architectures could reshape the role of vacuum assist over time, making flexibility and monitoring essential for long-term planning.
Strategic Recommendations for Decision-Makers
For manufacturers and suppliers, the priority is to align EVP development with the regulatory and platform shifts that are shaping demand. This means investing in adaptive control, efficiency, and on-demand operation, while building product families that can serve ICE, hybrid, and electrified applications without excessive rework. Equally important is the ability to demonstrate system-level integration value, not just pump specifications. Suppliers that can show how their EVP solutions support braking performance, emissions compliance, and power efficiency in a coordinated architecture are more likely to win program contention in a concentrated market.
For investors, the EVP segment offers growth supported by regulatory tailwinds and electrification-linked demand, but selection matters. The most resilient opportunities are likely to be found in suppliers with credible hybrid/EV integration strategies, demonstrated compliance readiness, and the ability to compete across both premium and cost-sensitive applications. Monitoring product launch cadence, partnership activity, and regional supply relationships can provide early signals about which players are expanding their relevance and which are constrained to narrow niches. Given the market’s concentration and technical barriers, due diligence should focus on validation capability, control software development, and exposure to regulatory-driven demand across key regions.
For procurement and OEM strategy teams, the key is to avoid treating EVPs as interchangeable commodities. Specifications alone do not capture the value of adaptive control, integration compatibility, and compliance support. Procurement strategies should evaluate total system impact, including brake performance, energy consumption, packaging constraints, and lifecycle cost, while maintaining flexibility to source from both established incumbents and regional specialists where appropriate. In a market where cost remains a restraint but compliance and performance are non-negotiable, the best outcomes typically come from balancing proven system reliability with competitive cost structures.
The EVP market is moving from steady expansion to a more strategically nuanced phase, where regulation, electrification, and intelligent control redefine what suppliers must deliver and what buyers should prioritize. For organizations seeking more detailed segmentation data, company-level tracking, and customized assessments tailored to specific program portfolios or investment theses, the full research report provides a deeper dive into the numbers and the strategic implications behind them.
For detailed analysis of this topic, please visit the official page: Automotive EVP (Electric Vacuum Pump) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Personal Radiation Dosimeter Market: Why 7.2% CAGR Reshapes Radiation Safety by 2032
By pmarketresearch, 2026-09-21
The Personal Radiation Dosimeter Market: Strategic Shifts and Commercial Opportunities (2026–2032)
Market Context and Core Challenges
The personal radiation dosimeter market has settled into a phase of steady expansion, with total revenue projected to grow from approximately $181.5 million in 2025 to over $293 million by 2032, representing a compound annual growth rate of 7.2%. This trajectory reflects a market that has moved past the post-pandemic supply disruptions of the early 2020s and is now anchored by consistent demand from regulated occupational environments. Historical movement from $145.8 million in 2020 through $170.97 million in 2024 shows a market that has successfully stabilized, while the forecast period through 2032 points to accelerating adoption in sectors where real-time exposure tracking is becoming a compliance expectation rather than a discretionary upgrade.
Several structural challenges are shaping how operators navigate this growth. First, the industry is experiencing a capability gap between traditional passive monitoring and the real-time, connected devices that hospitals, nuclear operators, and industrial sites increasingly expect. Passive dosimeters remain essential for legal dose records and accredited processing, but procurement teams are under pressure to supplement them with electronic systems that deliver immediate feedback, wireless telemetry, and integration with existing safety workflows. Bridging this gap requires manufacturers to manage dual product strategies, certification pathways, and service models without diluting quality or margin.
Second, regulatory tightening around dosimetry processing and connected device security is raising the compliance floor. Recent standards updates have clarified performance expectations for active personal dosimeters and periodic evaluation of processing services for X and gamma radiation. At the same time, data-protection requirements are extending into dosimetry registries and service platforms, compelling providers to embed cybersecurity controls into systems that were historically treated as standalone hardware. Companies that treat these requirements as afterthoughts face longer qualification cycles and potential exclusion from regulated contracts.
Third, supply chain resilience remains a strategic vulnerability. Semiconductor availability, sensor calibration consistency, and component traceability all influence lead times and total cost of ownership. Procurement organizations are increasingly evaluating vendors on their ability to guarantee service continuity, processing turnaround, and firmware support over multi-year deployment cycles. In a market where downtime or delayed dose reporting can disrupt operations and compliance documentation, reliability has become a differentiator as important as device performance.
Key Drivers Reshaping Demand and Value Creation
Technology Innovation and Connected Monitoring
A central driver of market expansion is the shift from periodic dose reading to continuous, connected exposure monitoring. Electronic personal dosimeters now increasingly combine real-time radiation detection with temperature, humidity, and location context, feeding data into mobile applications and enterprise safety platforms. This evolution is particularly impactful in healthcare and industrial settings where staff rotate across multiple zones and need immediate awareness of exposure trends. Devices that translate raw measurements into actionable alerts reduce reliance on retrospective review and enable proactive workflow adjustments, such as repositioning personnel or adjusting shielding practices during interventional procedures.
PW Consulting Automotive & Machinery Research Center
The commercial significance lies in the bundle of value these systems create. Buyers are no longer purchasing a badge or a handheld unit in isolation; they are adopting a monitoring ecosystem that includes hardware, software integration, data retention, and reporting interfaces. Manufacturers that design for interoperability, archive compatibility, and user-friendly feedback gain an advantage in repeat procurement cycles. Recent product launches in this space illustrate the direction of travel, with wearable connected devices emphasizing Bluetooth integration and real-time visibility for occupational use. Recognition of these solutions in medical imaging innovation awards further signals that end users are beginning to reward functionality that improves day-to-day safety operations, not just compliance checkbox completion.
Dosimetry Equipment Market
Policy and Regulatory Environment
Regulatory momentum is reinforcing demand for higher-performance dosimetry and more rigorous service oversight. Updated performance criteria for active personal radiation dosimeters are raising expectations for response time, dose rate handling, and reliability in real-time monitoring scenarios. Parallel standards for the periodic evaluation of processors of personal dosimeters introduce clearer benchmarks for processing quality, which matters for organizations that rely on accredited services for legal dose records. In practice, this means procurement teams must align device selection with processing accreditation and service-level commitments, rather than evaluating hardware on technical specifications alone.
Cybersecurity and data governance are also becoming integral to dosimetry procurement. New requirements for technical and methodological risk-management measures for TLD name registries and related service providers indicate that radiation monitoring data is increasingly treated within the broader framework of operational data protection. For vendors, this creates an opportunity to differentiate through secure data handling, auditable access controls, and transparent retention policies. For buyers, it adds a due diligence layer that rewards providers with mature information-security practices and clear contractual commitments.
Demand-Side Changes Across End-Use Sectors
Demand is being reshaped by changes in how organizations manage occupational exposure. In healthcare, growing awareness of cumulative exposure during interventional and diagnostic imaging procedures is driving interest in real-time staff monitoring, especially in high-throughput departments where traditional badge programs provide feedback only after the fact. In the nuclear sector, reactor maintenance, life-extension activities, and restart programs are intensifying the need for reliable personal monitoring with specialized detection capabilities, including algorithms tailored for neutron environments. Industrial and manufacturing users continue to require dependable monitoring for non-destructive testing, radiography, and other source-based operations, but they are increasingly selecting devices that integrate with broader safety systems and minimize administrative friction.
This demand shift is changing purchasing behavior. End users are more likely to evaluate total operational impact—training burden, ease of use, data integration, and processing reliability—alongside unit pricing. Organizations that previously standardized on a single passive solution are now layering electronic devices for high-exposure roles or high-turnover environments, creating hybrid monitoring programs. The result is a more nuanced demand profile in which volume, functionality, and service quality are negotiated together rather than treated as separate line items.
Supply Chain and Cost Structure Evolution
Cost dynamics are influenced by both hardware complexity and service economics. Electronic dosimeters with connected features require more sophisticated sensor integration, firmware management, and post-sales support, which can increase upfront costs but also create opportunities for recurring value through software, calibration, and data services. Meanwhile, passive dosimeter programs remain cost-effective for baseline monitoring, yet their value proposition depends heavily on processing turnaround, badge logistics, and the credibility of accredited dose records. As a result, the cost conversation is moving from unit price to total lifecycle cost, including training, replacement cycles, data management, and compliance risk.
Supply chain considerations further shape cost structures. Long-term availability of critical components, consistency in calibration standards, and the ability to maintain service networks across geographies all affect deployment risk. Buyers are increasingly weighing vendor stability and support capacity alongside product features, especially for multi-site operations where standardized equipment and predictable servicing reduce operational complexity. In this environment, manufacturers with disciplined quality systems and transparent supply planning are better positioned to secure long-term contracts and repeat business.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of specialized dosimetry providers, large scientific instrumentation companies, and regional manufacturers with strong positioning in specific detection technologies. Market concentration reflects a moderately consolidated landscape, where leading players compete on technology integration, service accreditation, and vertical-specific functionality rather than price alone. This structure rewards companies that can combine reliable measurement performance with usable data workflows and recognized processing credentials.
Several strategic patterns are evident among leading companies. Landauer maintains a strong position in occupational monitoring through OSL and TLD-based personal dosimeters, with accredited processing that supports legal dose records. Its differentiation lies in the combination of established detection methods and the service infrastructure required for compliant dose reporting, making it relevant for organizations that prioritize accredited dose of record alongside modern device options. Thermo Fisher Scientific has pushed into connected wearable monitoring with real-time radiation, temperature, and humidity capabilities and Bluetooth/app integration, targeting healthcare and industrial users who want immediate exposure visibility. Its recent wearable launch and recognition in medical imaging innovation categories highlight a strategy centered on usability, connectivity, and workflow integration.
Mirion Technologies offers electronic personal dosimeters for real-time X-ray and gamma monitoring, along with wireless systems for occupational dose tracking. Its approach emphasizes real-time awareness and tracking convenience, which appeals to users seeking to supplement passive programs with active alerting and centralized dose visibility. Polimaster continues to build on electronic personal dosimetry for X-ray and gamma detection in personal monitoring applications, with a focus on practical field usability and specialized detection needs. Fuji Electric has strengthened its relevance in nuclear environments by developing electronic personal dosimeters and exposure management systems that incorporate advanced neutron algorithms, and it has reinforced this positioning through partnership agreements to supply large volumes of dosimeters with neutron capabilities for restarting reactors. Unfors RaySafe contributes a real-time radiation dosimeter option for staff dosimetry in X-ray environments, emphasizing immediate visual exposure feedback and archive integration, which supports operational awareness in imaging settings.
The market is evolving along two reinforcing paths. On one hand, differentiation is increasing as vendors tailor solutions to distinct use cases—healthcare staff monitoring, nuclear applications, industrial radiography, and research environments—each with different detection requirements, usability priorities, and data integration needs. On the other hand, consolidation pressure is growing where buyers prefer fewer vendor relationships that can cover both passive and electronic monitoring, processing services, and data management. New entrants typically need a clear edge in sensor performance, connectivity, cost structure, or regional service capability to gain traction, while incumbent players are investing in firmware updates, app ecosystems, cybersecurity alignment, and partnership networks to defend and expand their positions.
Recent company activities illustrate how this competition is playing out. Innovation recognition for real-time occupational monitoring in medical imaging underscores that end users are rewarding products that improve safety operations in high-exposure clinical settings. Partnership contracts tied to nuclear restart programs show how specialized detection capabilities and supply reliability can translate into sizable deployment opportunities. Product launches emphasizing wearable connectivity and real-time monitoring reflect the broader shift toward devices that fit naturally into daily workflows rather than functioning as standalone compliance tools.
Forward-Looking Trends and Commercial Implications
Hybrid Monitoring Models Become the Norm
Over the next three to five years, the market is likely to move toward hybrid monitoring programs that combine passive dosimeters for accredited legal dose records with electronic devices for real-time awareness in higher-risk roles or high-turnover environments. This model allows organizations to preserve compliance continuity while gaining operational visibility where it matters most. For manufacturers, the opportunity lies in designing product portfolios that interoperate cleanly, supported by consistent data formats, unified reporting, and service arrangements that simplify mixed deployments. For buyers, the strategic task is to define where real-time monitoring delivers enough operational value to justify the added complexity and cost, rather than adopting connected devices uniformly across all roles.
One uncertainty in this trend is the pace at which regulatory guidance and internal safety policies formalize expectations for real-time monitoring. If standards and institutional practices continue to emphasize performance and data reliability for active dosimeters, adoption in healthcare and industrial settings may accelerate more quickly than capacity planning currently anticipates. If implementation remains fragmented, hybrid models may persist longer with uneven feature adoption, creating variability in demand across regions and end-use segments.
Data Integration and Cybersecurity as Purchase Criteria
Data handling is increasingly part of the procurement decision. Real-time dosimeters, app-based feedback, and archive integration create new expectations for data security, access control, retention, and interoperability with existing safety or occupational health systems. As regulatory direction strengthens risk-management expectations for dosimetry-related registries and service providers, organizations will likely evaluate vendors more closely on information-security maturity and contractual clarity. Commercially, this creates a path for providers that can demonstrate secure architectures, reliable data archiving, and transparent service commitments. It also raises the barrier for entrants that offer capable hardware but lack the service and data governance infrastructure needed for regulated environments.
A key risk here is the potential for fragmented standards implementation and differing organizational interpretations of cybersecurity obligations. Buyers may face complexity in comparing vendor claims, while vendors must invest in documentation, validation, and ongoing compliance support. Companies that can simplify this evaluation process—through clear security documentation, standardized integration options, and predictable service terms—will be better positioned to convert technical capability into commercial wins.
Specialized Detection and Vertical-Specific Solutions Gain Importance
As nuclear operations, healthcare imaging, and industrial radiography continue to place distinct demands on personal monitoring, vertical-specific solutions are likely to command greater attention. Devices with advanced neutron algorithms, specialized detection ranges, or integration tailored to imaging workflows can justify premium positioning when they reduce operational risk or improve monitoring accuracy in challenging environments. Large-scale partnership opportunities, such as deployments tied to reactor programs, illustrate how specialized capability combined with supply reliability can unlock volume business that generic solutions cannot easily capture.
The commercial implication is that broad commoditization will be limited to baseline monitoring segments, while differentiated solutions retain pricing power and stronger customer loyalty. The risk is that specialization requires sustained R&D investment and close alignment with operating conditions that may change over time. Vendors must therefore balance deep vertical focus with enough platform flexibility to adapt as applications, regulations, and user expectations evolve.
Strategic Actions for Decision Makers
For Manufacturers and Technology Providers
Build portfolios that connect hardware performance with data usability and service credibility. The most defensible positions will come from offering devices that integrate with existing workflows, support secure data handling, and are backed by reliable processing or service arrangements. Prioritize clear differentiation by end use rather than attempting to compete across all segments with a single general-purpose offering. Invest early in cybersecurity documentation, integration compatibility, and firmware support, since these factors are increasingly part of procurement evaluation in regulated environments. Where specialized detection is relevant, align product development with verified operational needs and secure supply commitments that can support larger deployment programs.
Personal Dosimeter Market
For Investors and Strategic Partners
Focus on companies that demonstrate a credible path to recurring value beyond one-time hardware sales. Models that combine connected devices, software-enabled safety workflows, processing services, and strong compliance credentials are better positioned to capture the operational value driving market growth. Assess exposure to regulatory trends that raise performance and data-security expectations, since these trends can expand demand for higher-quality solutions while also raising the bar for market entry. Pay attention to vertical opportunities where specialized detection or large-scale deployment commitments create meaningful differentiation, and evaluate whether target companies have the service infrastructure to retain customers over multi-year cycles.
For Procurement and Safety Leaders
Define monitoring strategies around actual exposure profiles and operational workflows instead of defaulting to uniform device selection. Hybrid approaches can preserve accredited dose recording while adding real-time visibility where staff face higher variability or cumulative exposure risk. Treat cybersecurity, data retention, integration compatibility, and processing turnaround as core evaluation criteria alongside detection performance. This is also the point where detailed segmentation data, regional dynamics, and vendor-specific capability comparisons become valuable for tailoring specification packages and negotiating service terms. A full market report can support that process by providing structured breakdowns and decision frameworks that match your operating context.
Closing Perspective
The personal radiation dosimeter market is moving from steady compliance-driven growth toward a more capability-led landscape, where real-time monitoring, data integration, and service reliability shape purchasing decisions as much as detection performance. Growth to nearly $293 million by 2032 at a 7.2% CAGR reflects a market that is expanding on the back of regulated occupational demand, technological connectivity, and evolving safety expectations. The organizations that capture the most value will be those that convert these trends into practical solutions for specific end uses, while managing the compliance, cybersecurity, and supply continuity requirements that increasingly define procurement success. For decision makers seeking to act on these dynamics with precision, deeper segmentation detail and customized strategic guidance can sharpen specification, investment, and partnership choices well before the next procurement cycle.
For detailed analysis of this topic, please visit the official page: Personal Radiation Dosimeter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Pile Driver Market 2026: The 5.25% CAGR Masks Hydraulic’s 68.88M USD Dominance
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Global Pile Driver Market
The global pile driver market is entering a decisive growth phase, driven by sustained infrastructure investment, evolving environmental regulations, and accelerating technological modernization across foundation construction. Valued at 196.78 million USD in 2025 and projected to reach 282.91 million USD by 2032, the market is expanding at a compound annual growth rate of 5.25 percent over the forecast window. The expansion from 162.34 million USD in 2020 reflects a steady climb punctuated by post-pandemic recovery cycles, followed by a more structured demand environment shaped by large-scale civil works, renewable energy installations, and offshore engineering programs. While the headline trajectory suggests consistent growth, the underlying market dynamics reveal a sector navigating technological transition, regulatory tightening, and shifting application priorities. Understanding these forces is essential for manufacturers, investors, and procurement leaders seeking to align capacity, investment, and sourcing strategies with where value is actually being created.
The current market environment is characterized by moderate growth rather than explosive expansion, with annual revenue progression indicating a maturing demand base that is increasingly selective about equipment specifications, service expectations, and total cost of ownership. Demand is no longer driven solely by volume of construction activity; it is increasingly influenced by project complexity, environmental compliance requirements, and the need for precision installation in congested urban and sensitive offshore environments. In this context, the pile driver market functions less as a commodity equipment segment and more as a technology- and service-intensive foundation solution space. Companies that recognize this shift are repositioning their product lines, service offerings, and regional footprints accordingly, while organizations that treat pile driving equipment as a standalone mechanical category risk misalignment with end-user priorities.
Three structural challenges define the current inflection point for the industry. First, environmental and noise-vibration regulation is becoming a constraining design parameter rather than a peripheral compliance issue. Offshore and urban foundation projects face stricter permitting conditions, which push equipment suppliers toward integrated mitigation systems and quieter installation methods. Second, skilled labor availability and wage pressure are changing the economic equation for construction and foundation contractors. As prevailing wage expectations rise in multiple regions and project schedules tighten, equipment that reduces operator dependency, improves repeatability, and enables remote or semi-automated control gains strategic relevance. Third, the market is experiencing a widening gap between standardized general-purpose machines and highly specialized solutions for solar, offshore wind, and complex infrastructure work. This divergence forces manufacturers to choose between broader product coverage and deeper application focus, while buyers must evaluate whether their project pipeline justifies specialization or favors flexible equipment fleets.
Key Drivers Reshaping Market Trajectory
Technology Innovation and Integrated Precision Systems
The most consequential driver in the pile driver market is the shift toward precision, control, and integration. Modern hydraulic and vibratory systems are increasingly designed with advanced automatic controls, auto-plumb functionality, remote operation, and positioning readiness for laser or GPS-guided installation. These features address a practical need: foundation work in renewable energy farms, transportation corridors, and dense urban sites requires repeatable accuracy and reduced rework. The trend is visible in recent product updates that emphasize wireless remote control and automated alignment features for utility-scale solar applications, reflecting how equipment design is being shaped by the installation rhythm of large-area renewable projects rather than traditional isolated construction jobs. Alongside this, new hydraulic pile driver platforms incorporating kinematic systems for Kelly drilling and sheet pile applications illustrate how manufacturers are expanding the functional scope of a single machine to cover multiple foundation tasks, improving equipment utilization for contractors who prefer multi-role assets.
Innovation is also advancing in the direction of noise and vibration mitigation, particularly where onshore urban work and offshore installation intersect with environmental permitting. The integration of mitigation systems into pile driving equipment is becoming a competitive differentiator, not merely an add-on service. As project owners and regulators demand cleaner installation methods, manufacturers that can offer equipment-ready mitigation capabilities or compatible hammer configurations are better positioned to win bids and maintain access to restricted sites. This dynamic is pushing the market toward more holistic equipment engineering, where hammer performance, control electronics, and environmental compliance are evaluated together rather than as separate purchasing decisions.
Policy, Regulation, and Permitting Pressure
Regulatory conditions are increasingly shaping equipment preferences and project economics. Occupational safety requirements already define operational boundaries for pile driving activity, including provisions that suspend cutting operations under specific proximity conditions unless protective distances are maintained. These rules influence site layout, equipment positioning, and crew procedures, making equipment that supports safer separation and controlled operations more attractive. On the environmental side, noise and vibration mitigation requirements for offshore and urban projects are becoming standard elements of project permitting, often tied to ISO-aligned expectations and local environmental approvals. This regulatory layer raises the bar for equipment selection because contractors must demonstrate that their installation method can satisfy both the engineering objective and the compliance constraint.
Beyond safety and environmental rules, broader infrastructure policy is indirectly accelerating demand for efficient hydraulic pile drivers. Large-scale investments in renewable energy and transportation networks are expanding the pipeline of foundation-intensive projects, and those projects frequently require installation methods that can meet tightening environmental expectations without sacrificing throughput. Policy-driven spending does not automatically translate into equipment sales; rather, it filters through procurement standards, site constraints, and the need for machines that can perform reliably within a regulated environment. The market response has been to favor equipment that can operate efficiently while reducing the compliance burden on contractors and developers.
Demand-Side Shifts and Application Diversification
Demand patterns are shifting as end-use sectors diversify beyond traditional building construction. Infrastructure programs remain a primary demand anchor, but renewable energy installations, offshore engineering, and specialized utility work are increasingly influencing purchasing decisions. Solar utility-scale projects, for example, create a distinct installation profile that rewards repeatability, remote control, and fast setup across large arrays. Offshore wind and coastal infrastructure projects, meanwhile, emphasize robust hydraulic hammers, noise mitigation capability, and reliability under demanding marine conditions. These application differences matter because they shape equipment specifications, service expectations, and even regional demand intensity.
On the buyer side, contractors and developers are increasingly evaluating pile driving equipment through a total project lens. Speed of installation, reduced rework, compliance readiness, and operator efficiency are becoming as important as purchase price. This is especially true where labor premiums and schedule pressure increase the cost of inefficiency. As a result, equipment that helps control labor intensity and installation variability is gaining ground, even if its upfront cost is higher. The broader implication is that demand is moving toward solutions that reduce operational risk and improve predictability, not just machines that deliver impact or vibration in isolation.
Supply Chain, Cost Structure, and Regional Realignment
Cost structures in the pile driver market are being shaped by input price volatility, manufacturing scale, and regional sourcing strategies. Equipment makers must balance durable construction, hydraulic performance, control-system complexity, and serviceability against the pressure to remain competitively priced in a market where buyers are increasingly cost-conscious but unwilling to sacrifice compliance or reliability. In parallel, regional demand patterns are reinforcing different competitive approaches. Markets with strong infrastructure pipelines and mature contracting ecosystems reward established product lines, service networks, and proven reliability. Regions with rapidly expanding renewable and civil works programs create room for technology-forward equipment and targeted application offerings, but also demand close attention to local permitting, labor conditions, and contractor preferences.
Labor cost dynamics further influence equipment economics. In certain construction labor markets, prevailing wage structures and premium pay for non-standard hours raise the financial impact of inefficient installation. That creates a stronger incentive for equipment that reduces cycle time, supports fewer-operator workflows, and lowers the likelihood of rework or compliance interruptions. When labor cost pressure rises, the business case for automation-enabled control, remote operation, and precise positioning strengthens, even if the purchase decision remains constrained by capital budgeting cycles.
Marine Engineering Hydraulic Piling Hammer Market
Competitive Landscape and Leading Strategies
The competitive field in the pile driver market is fragmented but increasingly stratified by application expertise, geographic reach, and technology integration. The market remains moderately concentrated, with the largest players commanding a meaningful share of revenue while still leaving substantial room for regional specialists and application-focused manufacturers. This structure creates a competitive environment where scale, product breadth, and service capability matter, but so does the ability to align equipment with specific project types and compliance conditions.
North American manufacturers have carved out a strong position in foundation construction equipment, with some firms serving as the largest regional producers of pile driving and drilling equipment and offering a broad mix of vibratory drivers, impact hammers, power units, and drilling rigs. Their advantage often lies in product range, local service familiarity, and close alignment with domestic foundation contractors. Other leading players focus on foundation equipment at a global scale, producing some of the largest pile drivers in the market and covering vibratory drivers, diesel hammers, hydraulic impact hammers, and power units. Their strategic positioning is rooted in scale, engineering breadth, and the ability to serve demanding heavy civil and large-diameter piling applications.
In the utility-scale and solar segment, manufacturers have gained attention by designing pile drivers around precise installation, auto-plumb, remote control, and laser or GPS-ready positioning. This application-led approach differentiates equipment not by raw power alone, but by how effectively it supports repeatable deployment across large project footprints. European manufacturers bring long-standing expertise in diesel hammers and impact solutions for construction and infrastructure, often leveraging decades of product heritage and specialized hammer engineering. Others in the European space specialize in hydraulic pile hammers, noise mitigation systems, and offshore pile driving equipment for wind, coastal, and oil and gas projects, making them particularly relevant where environmental constraints and marine operating conditions dominate.
PW Consulting Automotive & Machinery Research Center
Broader construction and civil machinery companies also participate in the market through hydraulic hammers and pile driving equipment designed for heavy civil and infrastructure work. Their relevance often comes from integrating pile driving capability into wider equipment portfolios and service networks, which can be attractive to contractors seeking consistency across machine types. Specialty manufacturers add further differentiation with side-grip vibratory pile drivers, hydraulic piling hammers, and advanced automatic controls, while some Chinese manufacturers emphasize technology integration for foundation engineering in renewable energy and infrastructure, and others supply diesel and hydraulic impact hammers for state-owned enterprises and offshore or bridge projects.
Recent industry developments illustrate how this competitive landscape is evolving. Product launches have introduced new hydraulic pile driver platforms with expanded kinematic capability for Kelly drilling and sheet pile work, signaling a push toward multi-function equipment. Prototype announcements for vertical and inclined pole driving point to continued experimentation with installation geometry and specialized use cases. Expansion of U.S. sales presence by press-in piling equipment providers reflects growing interest in alternative installation methods and direct mechanical displacement solutions. At the same time, product catalog updates emphasizing wireless remote control and auto-plumb features for solar utility-scale projects show how established models are being refined to match application-specific operating needs. These moves suggest a market where competition is increasingly about precision, versatility, and compliance-ready design rather than equipment category alone.
Market evolution is likely to follow a dual path. Consolidation will remain attractive for manufacturers seeking broader geographic coverage, stronger service networks, and more complete product lines, especially where contractors prefer fewer supplier relationships and more predictable support. At the same time, differentiation will continue to fragment the market by application, with specialized solutions for offshore, solar, urban noise-sensitive, and complex infrastructure projects creating niches that reward focused engineering and targeted sales strategies. New entrants and expanding regional players can gain traction by addressing underserved application requirements, offering alternative installation methods, or providing equipment configurations that align with local labor, regulatory, and project conditions. The strategic implication is that neither pure scale nor pure specialization guarantees advantage; success depends on aligning product strategy with the demand profile of the projects that actually dominate a company’s target pipeline.
Future Trends and Commercial Opportunities (2026–2032)
Over the next several years, the pile driver market is likely to be defined by three reinforcing trends. The first is the continued integration of automation-ready controls and positioning technologies into mainstream pile driving equipment. As installation accuracy, remote operation, and reduced operator dependence become more important to contractors managing labor pressure and schedule risk, machines that offer semi-automated alignment, remote control, and guidance-system compatibility will become increasingly standard rather than premium. The commercial opportunity here lies in equipment and service packages that improve installation repeatability, reduce rework, and support faster crew training across multiple project types.
The second trend is the deepening alignment between equipment design and environmental compliance. Noise and vibration mitigation will move from project-specific workaround to baseline expectation in offshore, urban, and sensitive onshore environments. Manufacturers and service providers that can deliver mitigation-compatible hammers, integrated mitigation systems, and installation methods suited to permitting requirements will be better positioned to access restricted projects and support contractor bidding credibility. The opportunity is not simply in selling more equipment, but in helping end users navigate the regulatory dimension of foundation installation with fewer interruptions and clearer compliance pathways.
The third trend is the widening relevance of application-specific equipment strategies. Renewable energy build-out, transportation infrastructure, offshore engineering, and specialized utility work will continue to pull demand in different directions, making one-size-fits-all product portfolios less effective over time. Contractors and developers will increasingly favor equipment that matches the installation rhythm of their most important project types, whether that means fast setup and remote control for large solar farms, robust hydraulic performance for heavy civil works, or marine-ready systems with mitigation capability for offshore tasks. The commercial opportunity lies in mapping equipment offerings to the highest-value application clusters, then building configuration, service, and support around those clusters rather than spreading effort evenly across all possible use cases.
These trends carry risk and uncertainty. Regulatory expectations can change faster than equipment development cycles, particularly where local permitting, environmental review, and safety enforcement differ by jurisdiction. Labor market conditions may shift the balance between capital investment in advanced equipment and reliance on skilled crews, making demand for automation-enabled features more or less urgent depending on region and project timing. Competitive intensity may also increase as manufacturers broaden multi-function platforms and alternative installation methods gain traction, potentially compressing margins in segments where differentiation is difficult. Finally, project pipelines tied to infrastructure and renewable energy spending are subject to procurement delays, funding timing, and policy adjustments, meaning demand growth may arrive in waves rather than as a smooth upward curve.
Actionable Guidance for Decision-Makers
For Manufacturers and Equipment Suppliers
Product strategy should be anchored to application realities rather than broad category coverage. Prioritize control integration, remote operation, and positioning compatibility as core selling points, especially where labor efficiency and installation accuracy directly influence project economics. Develop mitigation-compatible configurations and clearly communicate how equipment supports compliance in noise-sensitive and offshore settings. Evaluate whether the strongest returns will come from expanding multi-function platforms or from deeper specialization in a few high-value segments such as solar utility-scale work, heavy civil infrastructure, or offshore foundation installation. Service, training, and spare-parts availability should be treated as part of the product proposition because contractor decisions increasingly account for total operating risk, not just purchase price.
For Investors and Capital Allocators
Focus on businesses that demonstrate a credible link between equipment capability and shifting demand drivers: precision installation, environmental compliance, labor efficiency, and application-focused differentiation. Companies that can serve high-growth project types while maintaining strong service and support networks are better positioned than those competing primarily on baseline mechanical function. Pay attention to regional demand mix, because infrastructure-intensive markets and renewable energy build-out zones may offer faster growth but also different competitive dynamics and regulatory constraints. Assess whether a company’s product roadmap reflects the likely trajectory of automation, mitigation, and application specialization, since those factors will shape both revenue quality and competitive defensibility through the end of the decade.
For Procurement Leaders and Contractors
Evaluate pile driving equipment against the actual operating conditions of the projects in your pipeline. If labor premiums, schedule pressure, and compliance requirements are significant, prioritize machines that reduce operator dependency, improve alignment accuracy, and support safer site workflows. For larger renewable or infrastructure programs, examine whether multi-role equipment or application-focused machines better match your installation profile and crew structure. Include noise and vibration mitigation compatibility in the procurement decision where permitting conditions make it relevant, and ensure that supplier support, training, and replacement-part availability are assessed alongside technical specifications. The most cost-effective equipment is not always the least expensive upfront; it is the solution that minimizes rework, site interruptions, and labor inefficiency across the projects you actually intend to execute.
Hydraulic Hammer Market
The strategic picture is clear: the pile driver market is expanding, but the most valuable opportunities are concentrated in precision, compliance readiness, application alignment, and operational efficiency. Organizations that treat these as central purchasing and product priorities will navigate the next phase of market growth more effectively than those reacting only to headline demand. For decision-makers who need more granular segmentation, regional nuance, and tailored scenario planning, detailed research coverage can provide the deeper data and structured recommendations required to move from directional insight to executable strategy.
For detailed analysis of this topic, please visit the official page: Pile Driver Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Panoramic Sunroof Market 2026: 7.8% CAGR Trajectory and Regional Shifts
By pmarketresearch, 2026-09-21
Panoramic Sunroof Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Overview: A Sector in Structural Expansion
The panoramic sunroof market has transitioned from a premium comfort upgrade to a core architectural feature in modern vehicle design. From 2020 to 2025, the market expanded steadily, growing from approximately 2.0 billion USD to 2.75 billion USD in 2025. The trajectory is projected to accelerate through the forecast horizon, with the market expected to reach 4.75 billion USD by 2032. This expansion reflects a compound annual growth rate of 7.8 percent, driven by a combination of vehicle platform redesigns, electrification trends, and evolving consumer expectations around cabin experience.
Automotive Sunroof Market
The growth is not uniform across all categories. Multi-panel configurations currently command the largest share of revenue, indicating a sustained preference for flexible light and ventilation solutions over single fixed panels. Application-wise, sedans and hatchbacks continue to represent the dominant volume, though SUV integration remains a significant and growing contributor. Geographically, the Asia Pacific region accounts for the largest revenue pool, followed by Europe and North America, with Latin America and the Mideast and Africa regions representing smaller but increasingly relevant demand centers.
Structural Challenges and Inflection Points
The sector is navigating several simultaneous pressures that are reshaping investment priorities and product roadmaps.
One of the most pressing challenges is the tension between aesthetic and experiential demands and physical constraints. Panoramic roof systems are expected to deliver larger glazed areas, lighter weight, improved thermal insulation, and higher structural integrity, all while meeting increasingly stringent safety requirements. Engineers are being asked to deliver more glass without adding mass, and to integrate switchable glazing, ambient lighting, and electronic actuators without compromising sealing performance or crash behavior. This pushes manufacturers toward material innovation and tighter system integration rather than incremental design changes.
A second inflection point comes from regulatory and certification complexity. Panoramic roofs must satisfy safety glazing standards and new requirements related to pedestrian protection in roof zones. At the same time, electronic actuator and control systems must align with functional safety expectations for automotive applications. These requirements raise the bar for validation, change the cost structure of product development, and make compliance capability a meaningful competitive differentiator.
A third challenge lies in the changing vehicle mix and the specific demands of electric platforms. Electrification affects roof architecture in multiple ways. Battery packaging, body stiffness targets, and drag coefficient management all influence how panoramic systems are specified and integrated. Consumer preference is moving toward openable panoramic configurations in EVs and SUVs, motivated by perceived improvements in interior space and air circulation. That shift creates opportunities, but also forces suppliers to adapt to different assembly sequences, thermal requirements, and volume patterns compared with traditional internal combustion platforms.
Core Growth Drivers
Technological Innovation and Material Evolution
The market is being shaped by a steady push toward lighter, smarter, and more integrated roof systems. Glass specification is a major focus area. Recent technical guidance in the sector notes that PVB interlayer films used in panoramic roof glass are moving toward reduced layers and gradient applications. This approach aims to lower weight and simplify installation in fixed panoramic modules, while preserving optical quality and structural performance. The same trajectory supports broader industry efforts to reduce component mass without sacrificing safety or durability.
Beyond glazing, actuator technology and electronic integration are becoming central to product differentiation. Openable panoramic systems increasingly combine smooth operation, low noise, and higher reliability with embedded controls that support diagnostic and safety functions. Suppliers that can package these features into compact, robust modules are better positioned to win on next-generation platforms where roof assembly space is tightly constrained.
Policy, Regulation, and Certification Dynamics
Regulatory frameworks are not merely compliance hurdles; they are actively influencing product architecture and supplier selection. Vehicle roofs are subject to safety glazing requirements and newer pedestrian protection considerations that affect how panoramic systems are designed and tested. For electronic components, functional safety expectations are now a baseline requirement for actuators and control modules. These standards raise the cost of entry for casual participants and reward suppliers with established validation infrastructure and documented engineering processes.
At the same time, broader vehicle regulation and testing protocols are indirectly increasing the strategic value of panoramic roofs. Emission-related standards and testing cycles place greater emphasis on aerodynamic efficiency and perceived vehicle drag reduction. In that context, a well-integrated roof system can contribute to packaging efficiency and overall design coherence, even if its direct emissions impact is indirect. The result is a market where regulatory alignment and engineering maturity reinforce each other.
Demand-Side Shifts in Passenger Vehicle Expectations
Buyers and OEMs are increasingly treating the roof as part of the lifestyle and cabin experience rather than a purely structural element. The preference for openable panoramic sunroofs in EVs and SUVs underscores a desire for improved headspace and fresh air circulation, along with the visual and experiential benefits of larger glazed areas. For manufacturers, these features can support vehicle positioning, especially in segments where cabin ambiance and perceived premium quality influence purchase decisions.
This demand shift is also pushing attention toward ambient lighting, switchable glazing, and other features that blur the line between roof and interior environment. As these elements become more common, the roof assembly becomes a more complex subsystem, and suppliers with broader integration capabilities gain leverage in the value chain.
Supply Chain and Cost Structure Pressures
Cost and weight targets remain persistent drivers of engineering decisions. Lightweighting goals are especially important as manufacturers balance safety, packaging, and efficiency requirements. At the same time, the integration of advanced glazing, electronics, and sealing technology changes the cost profile of panoramic systems. Suppliers are responding by designing modules that consolidate functions, reduce assembly complexity, and support more efficient installation on production lines.
Supply chain resilience is also increasingly relevant. Roof systems require coordinated inputs from glass manufacturers, polymer and interlayer suppliers, actuator producers, and module integrators. Any disruption in specialized materials or component availability can affect program timing and cost. Companies that can manage multi-tier sourcing, standardize designs across platforms, and maintain disciplined quality controls are better placed to withstand volatility and protect margins.
Competitive Landscape and Strategic Positioning
The market is moderately concentrated, with the top three players capturing a significant share and the top five firms accounting for a majority of revenue. This structure suggests that scale, platform relationships, and engineering breadth matter, but it also leaves room for specialists who can win on specific attributes such as lightweight construction, glazing quality, or system integration.
Webasto SE remains a prominent reference point in openable panoramic roof systems, with a positioning that emphasizes market-leading glass, ambient lighting, and switchable glazing for passenger cars and SUVs. Its recent Infinity Roof panoramic roof system launch for Mahindra Electric Origin SUVs illustrates how suppliers are aligning product portfolios with electrification and premium cabin features. The launch highlights the growing relevance of lighting-integrated and experience-led roof designs in electrified SUVs.
Inalfa Roof Systems competes as a specialist in panoramic and openable modules, with an emphasis on lightweight designs and system integration. Its value proposition fits naturally into platforms where weight reduction and assembly efficiency are priorities. Magna International brings a broader module and sealing technology perspective, offering customizable panoramic sunroof modules and roof system solutions that can be tailored across multiple vehicle architectures.
CIE Automotive contributes through lightweight and composite panoramic sunroof components and full roof systems, reinforcing the importance of material choice in cost-and-weight-sensitive programs. Aisin Seiki and Yachiyo Industry represent established manufacturing depth in premium panoramic systems and sunroof mechanisms, with Aisin focused on OEM-facing integrated roof components and Yachiyo on specialized sunroof and related system production. Inteva Products and Johnan America, Inc. add further breadth in engineered roof systems and sunroof mechanisms, including subsidiary-linked Japanese manufacturing capability. Saint-Gobain Sekurit and Bosch GmbH extend the competitive picture into critical subcomponents, with Saint-Gobain Sekurit focused on advanced glazing systems for panoramic glass panels and Bosch producing panoramic sunroof actuators and full roof module systems.
Risks, Uncertainties, and Strategic Implications
The outlook remains favorable, but several uncertainties could alter the pace or shape of growth. Regulatory requirements will continue to evolve, and changes in safety glazing, pedestrian protection, or functional safety expectations could increase development costs or force redesigns on active programs. Macroeconomic conditions affecting vehicle production volumes, especially in price-sensitive segments, can influence component demand and pricing power. Material availability and the cost of specialized glass, interlayers, and electronic subsystems may create margin variability, particularly for suppliers with less diversified sourcing or limited scale.
There is also the risk that consumer preferences shift toward fixed panoramic designs in some applications if cost, durability, or reliability concerns outweigh the appeal of openable systems. In parallel, platform consolidation and OEM sourcing strategies could concentrate volume among a smaller set of suppliers, making it harder for smaller or less established players to maintain program wins. The strategic implication is clear: competitive advantage will increasingly depend on engineering versatility, compliance readiness, and the ability to deliver lighter, smarter systems that fit tightly constrained vehicle architectures.
Strategic Takeaways for Decision-Makers
For Manufacturers and Suppliers
Prioritize integration and weight reduction as core product development themes. Designs that consolidate sealing, actuation, and glazing functions while reducing mass are likely to align well with OEM priorities on efficiency and assembly practicality. Build explicit capability around regulatory and functional safety requirements, since these are becoming gate checks for program qualification rather than optional add-ons. Expand platform leverage where possible by standardizing core modules across multiple vehicle programs, which can improve cost position and reduce launch risk.
In parallel, monitor electric vehicle and SUV platforms closely. These segments are shaping demand for openable panoramic systems and experience-led features such as ambient lighting and switchable glazing. Suppliers that can demonstrate reliable integration in electrified architectures will be better positioned to capture the next wave of volume.
For Investors and Strategic Planners
Assess exposure to the full value chain, not just final assembly. Glazing, interlayer materials, actuators, and sealing technologies each carry different growth profiles and risk characteristics. Companies with diversified capabilities across multiple subcomponents may offer more resilient positioning than pure single-function players. Pay attention to the balance between consolidation and specialization: while the market is moderately concentrated, niche differentiation in lightweight materials or advanced glazing can still create competitive advantage.
Track program timing, platform cycles, and OEM sourcing shifts as leading indicators. Volume growth will be uneven across regions and vehicle types, and the mix between fixed and openable configurations will influence which supplier profiles benefit most.
For Procurement and OEM Strategy Teams
Treat panoramic roof sourcing as a system integration decision rather than a commodity purchase. Evaluate suppliers on total system performance, including sealing reliability, weight, electronic safety alignment, and support for future feature integration such as switchable glazing or ambient lighting. Where possible, clarify long-term platform requirements early to enable suppliers to optimize designs for cost, weight, and assembly efficiency.
Roof Windows Market
Balance cost objectives with resilience. Resilient multi-tier sourcing and clear quality expectations can reduce the risk of launch delays or compliance issues, particularly when specialized materials and electronic components are involved. A disciplined sourcing strategy can also create room to negotiate better total cost positions without sacrificing performance.
Looking Ahead
The panoramic sunroof market is entering a phase where growth is increasingly tied to engineering depth, regulatory readiness, and alignment with electrification and SUV trends. The sector is expanding toward the 4.75 billion USD range by 2032, but the value will be captured by companies that can deliver lighter, smarter, and more integrated roof systems while meeting rising safety and functional safety expectations. The combination of material innovation, experience-led features, and tighter integration points toward a market that rewards capability rather than scale alone.
For organizations operating in or around this space, the most valuable next step is to map the specific platform, regulatory, and sourcing implications that will shape individual programs and regional demand. Detailed segmentation, regional nuance, and company-level scenario analysis can sharpen execution plans and reveal where the most durable opportunities are forming. The full research report provides that deeper breakdown, including detailed segmentation data, regional dynamics, and tailored recommendations for procurement, product development, and investment planning.
PW Consulting Automotive & Machinery Research Center
For detailed analysis of this topic, please visit the official page: Panoramic Sunroof Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Trailer Hitch Market 2026: Why 6.5% CAGR and North America's $96M Share Redefine Growth
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Global Trailer Hitch Market
The trailer hitch market has matured into a critical infrastructure component for vehicle towing ecosystems, linking consumer recreation, commercial logistics, and specialty transport applications. As of the 2025 baseline, the industry has reached a scale where incremental growth requires deliberate positioning rather than broad participation. Historical momentum from 2020 through 2025 reflects steady expansion, followed by a forecast trajectory through 2032 that points to continued, though uneven, advancement. The trajectory is supported by a compound annual growth rate of approximately 6.5 percent, with total market revenue measured in USD millions across all segments. This scaling is not merely a function of more vehicles on the road; it reflects structural shifts in how goods, leisure assets, and specialized equipment are moved across short and medium distances.
At the macro level, the market is characterized by concentrated leadership, with the top three players accounting for roughly 65 percent of revenue and the top five expanding that share to around 80 percent. Such concentration signals a landscape where incumbents have built durable advantages in distribution, engineering know-how, and brand trust. Yet concentration does not imply stagnation. The forecast window through 2032 suggests that pockets of rapid growth persist in specific applications and geographies, while the overall curve is tempered by cost pressures, regulatory scrutiny, and shifting vehicle architectures. For decision-makers, the central question is no longer whether the market is expanding, but where value will accrue when growth becomes more selective and when compliance costs rise alongside performance expectations.
Market Snapshot and Structural Pressures
The revenue trajectory from 2020 to 2025 established a foundation that the 2026 to 2032 forecast builds upon, with the 2025 baseline serving as a pivot point for both planning and competitive investment. Growth has been broad-based enough to reward scale players, but not so uniform that every segment shares the same economics. Receiver hitches continue to anchor a large share of total revenue, reflecting their ubiquity across light and medium-duty towing. Alongside them, gooseneck, fifth wheel, weight distribution, and pintle configurations each command distinct niches tied to vehicle type, load profile, and regional towing culture. The application mix spans recreational towing, marine transport, equipment hauling, agricultural use, and other commercial activities, creating demand that is simultaneous but not homogeneous. This heterogeneity is a defining feature of the market: one product family must satisfy very different engineering tolerances, end-user expectations, and procurement cycles.
Three challenges now shape the industry’s near-term path. First, regulatory and safety scrutiny is intensifying, particularly around load security and component integrity. A notable example is the recall of more than 145,000 trailer hitch locks in 2025 due to a loose component that could allow loads to detach from towing vehicles, as documented in the NHTSA official recall notice from January 2025. Such events elevate customer sensitivity to failure modes and push manufacturers to tighten quality assurance, traceability, and design validation. Second, vehicle platform evolution is altering attachment points, electrical architectures, and clearance constraints, making vehicle-specific fit increasingly complex even as consumers and fleets expect seamless integration. Third, input cost volatility and supply chain dependencies continue to pressure margins, especially for stamped steel, castings, coatings, and electronic kits, while customers resist price increases that outpace perceived value. These forces are not independent; they interact to raise the bar on engineering rigor, process control, and go-to-market discipline.
Trailer Axle Market
Key Demand Drivers Reshaping the Market
Technology Innovation and Performance Benchmarks
Engineering differentiation has moved beyond basic load ratings to encompass integration, adjustability, corrosion resistance, and ease of installation. Manufacturers are investing in designs that reduce tongue weight transfer issues, improve maneuverability under load, and simplify accessory changes such as ball mounts and sway control. Hidden and low-profile hitch configurations, once niche considerations, are gaining relevance among passengers and commercial users who prioritize aesthetics and packaging without sacrificing functional capacity. Electrical integration, including lighting and sensing kits in OEM-quality grades, is becoming a meaningful point of value creation, especially where trailer detection, braking coordination, and vehicle electronics must work in concert. These advances do more than raise performance; they create defensible product lines that can command premium positioning and reduce substitution risk when installed correctly and supported by clear documentation.
The practical implication is that performance claims require substantiation. Products that deliver measurable improvements in towing stability, installation time, or long-term durability are better positioned to win in channels where technicians and knowledgeable buyers compare alternatives directly. Conversely, commoditized SKUs face greater pressure to compete on price alone, which can erode margins and brand equity over time. Innovation that reduces field failures and simplifies the fit process tends to generate the strongest combination of customer satisfaction and repeat demand.
Policy, Regulation, and Safety Expectations
Regulatory attention is raising the cost of nonconformance and the value of preemptive quality systems. The 2025 lock recall illustrates how a single component vulnerability can ripple through distribution networks, service channels, and consumer confidence. Beyond recalls, manufacturers must navigate evolving standards for load ratings, labeling, towing safety communications, and electrical compatibility. In Europe, OEM-quality expectations and homologation requirements often shape product specifications at the design stage, while North American channels emphasize vehicle-specific fit, installation support, and dealer education. In both contexts, compliance is shifting from a back-office function to a front-line competitive factor.
For strategy, this means quality planning and design validation are no longer optional cost centers. Companies that embed traceability, durability testing, and field monitoring into product development reduce the probability of costly corrective actions and build trust with downstream partners. Clear communication about specifications, installation requirements, and load limits also protects brand reputation and reduces misuse-related claims. In markets where safety perception influences purchasing, a track record of reliable components can support premium pricing and improve channel willingness to stock and promote a product line.
Demand-Side Behavior and Use-Case Expansion
Demand patterns are shaped by recreational towing, marine transport, equipment hauling, agricultural work, and other commercial applications, each with distinct purchasing triggers. Recreational towing drives volume through seasonal purchasing, accessory add-ons, and upgrades tied to vehicle changes. Marine and equipment transport prioritize reliability and quick attachment, often under time pressure and in demanding environments. Agricultural and specialty commercial use tends to value durability, serviceability, and compatibility with existing equipment more than appearance or low profile. These divergent priorities mean that a single product architecture rarely satisfies all segments equally, and successful portfolios are those that align features with real use-case constraints.
Behavioral shifts also matter. Buyers increasingly expect vehicle-specific solutions, clear installation guidance, and accessories that reduce friction during setup. As towing becomes more connected to broader vehicle electronics and active safety features, end users and commercial operators look for components that integrate cleanly rather than simply bolt on. In this environment, education and support become part of the product experience, influencing both initial purchase and long-term loyalty. Companies that provide precise fit information, installation clarity, and accessory ecosystems tend to convert interest into sales more efficiently than those relying on broad compatibility claims alone.
Supply Chain and Cost Structure Dynamics
Cost structure is being reshaped by material inputs, manufacturing footprints, and logistics dependencies. Steel pricing, coatings, casting capacity, and electronic content all influence the cost base for hitch assemblies and associated kits. At the same time, regional sourcing decisions affect lead times, tariff exposure, and responsiveness to local demand patterns. The result is a market where efficient operations and disciplined inventory management can create meaningful margin advantages, while brittle supply chains expose producers to stock-outs and price instability.
The commercial opportunity lies in designing for manufacturability and serviceability without sacrificing performance. Standardizing high-volume components where possible, coordinating material procurement with rolling demand plans, and reducing assembly complexity can improve throughput and lower unit cost. Equally important is aligning production location decisions with channel realities, since regional preferences for OEM-quality content, dealer support, and after-sales service can differ substantially. Companies that balance scale with flexibility tend to navigate cost volatility more effectively than those locked into rigid cost structures.
Competitive Landscape and Evolving Positioning
Incumbent Strengths and Differentiation Vectors
The market features a mix of established North American manufacturers and European suppliers with strong OEM relationships and engineering heritage. CURT Manufacturing operates with a focus on USA-made, vehicle-specific fit for both OEM and aftermarket contexts, spanning receiver, fifth wheel, and gooseneck offerings alongside a full towing product set. Draw-Tite emphasizes custom designs and hidden hitch options distributed through dealer networks, a model that rewards channel relationships and installation readiness. Reese Products is known for heavy-duty receiver and towing systems that span light to heavy applications, appealing to users who prioritize capacity and ruggedness. B&W Trailer Hitches brings American-made engineering to gooseneck and fifth wheel categories, with attention to ball mount adjustability and weight distribution systems. Blue Ox addresses towing solutions such as tow bars, baseplates, sway control, and fifth wheel hitches, aligning closely with specialty towing requirements.
European suppliers add a distinct dimension. MVG focuses on towbars and electrical kits delivered in OEM-quality grades, which supports integration into vehicle platforms where fit and finish are tightly controlled. ACPS Automotive, operating under the ORIS name, produces disappearing hitches for passenger cars, SUVs, and vans, targeting end users who value aesthetics and integrated packaging. Bosch contributes towbars and hitch components, leveraging broader automotive component credibility and engineering scale. On the consolidation side, Horizon Global Corporation manages multiple brands including Draw-Tite, REESE, Bulldog, and Fulton, enabling portfolio breadth and cross-brand distribution leverage. RANDYS Worldwide offers adjustable hitch products and continues to expand its towing solution set, including a 2025 acquisition of BulletProof Hitches aimed at broadening accessories and towing capabilities.
Integration, Differentiation, and Channel Dynamics
The competitive landscape is evolving through a blend of consolidation, portfolio extension, and niche specialization. Larger multi-brand operators can use shared engineering, procurement, and distribution to capture efficiencies while maintaining distinct brand identities for different customer segments. This structure allows them to address a wide range of vehicle types and use cases without forcing every product into a single brand narrative. At the same time, specialist manufacturers maintain advantage by deepening vehicle-specific fit, heavy-duty capacity, or OEM-quality integration, which can be difficult for broader portfolios to replicate at equal fidelity.
Channel strategy remains decisive. Dealer networks, specialty retailers, and online distribution each impose different expectations for packaging, fit information, inventory depth, and support materials. In dealer-led channels, installation readiness and technician trust often determine repeat business. In direct and e-commerce channels, clear specifications, compatibility tools, and accessory bundles influence conversion. Companies that align product design with channel realities, rather than forcing the same offering through every route, tend to achieve stronger sell-through and fewer returns. The market also rewards brands that can communicate load ratings, compatibility, and safety guidance with precision, since uncertainty at point of purchase frequently becomes friction in the sales process.
A practical development to monitor is the ongoing M&A activity that broadens accessory and towing solution portfolios. RANDYS Worldwide’s acquisition of BulletProof Hitches in April 2025 signals a continued push to assemble more complete towing ecosystems rather than competing on the hitch assembly alone. This trend suggests that future competition will increasingly be evaluated across the full set of accessories, mounting hardware, electrical kits, and support content that surround the primary hitch, making ecosystem completeness a strategic asset.
Forward-Looking Trends and Linked Opportunities
Trend One: Integration as a Baseline Expectation
Over the next three to five years, hitch products are likely to be judged not only by load capacity but by how cleanly they integrate with vehicle architecture, electrical systems, and accessory ecosystems. This trend favors designs that simplify installation, reduce ambiguity in fitment, and support compatible lighting, braking, and sensing components. The commercial opportunity is in building product lines where the hitch is the anchor for a coherent solution rather than an isolated component. Manufacturers that invest in compatibility tooling, installer guidance, and accessory coordination can capture higher ensemble value and reduce substitution risk. The risk is that integration expectations rise faster than product development cycles can accommodate, especially as vehicle platforms change and electrical architectures become more complex. Companies that treat integration as a continuous capability, supported by close coordination with vehicle data and field feedback, will be better positioned to stay current.
Trend Two: Safety and Compliance as Competitive Levers
Safety scrutiny is expected to persist as a defining influence on product design, marketing claims, and distribution standards. Recalls and field failures draw attention to load security, component integrity, and installation correctness, which in turn raises the value of robust testing, clear labeling, and traceable manufacturing. The opportunity is to convert compliance discipline into a market advantage by offering products with verifiable durability, straightforward installation, and transparent specifications. Buyers and channel partners increasingly prefer brands that reduce uncertainty, and that preference can translate into stickier relationships and more resilient pricing. The uncertainty lies in the possibility of more stringent requirements or enforcement actions that raise the cost of conformity across the sector, compressing margins for players without efficient quality systems. Firms that build quality into the process rather than inspecting it at the end will absorb regulatory shifts more effectively.
Trend Three: Portfolio Breadth and Ecosystem Completion
A third trend is the movement toward broader towing and accessory portfolios that address the full task of towing rather than a single hardware item. This is visible in acquisitions and multi-brand structures that assemble receiver solutions, weight distribution systems, gooseneck and fifth wheel options, hidden designs, and electrical kits under coordinated strategies. The opportunity is to capture more wallet share by offering compatible accessories, replacement parts, and service content that accompany the primary hitch. Complete ecosystems also support installation confidence and reduce the likelihood of mismatched components, which improves customer outcomes and reduces returns. The risk is complexity: broader portfolios require disciplined product rationalization, consistent quality across brands, and clear positioning so that customers can navigate choices without confusion. Organizations that scale portfolios while preserving clarity in fit, function, and support are more likely to convert breadth into durable advantage.
PW Consulting Automotive & Machinery Research Center
Strategic Implications for Decision-Makers
For Manufacturers
Product differentiation should be anchored in fit precision, integration quality, and verified durability rather than in broad claims of capacity. Prioritize engineering that reduces installation ambiguity and supports accessory compatibility, since these factors directly influence field performance and channel confidence. Invest in the quality systems and traceability needed to manage safety scrutiny, because recalls and field issues can quickly erode brand trust and create costly corrective cycles. Where scale allows, pursue portfolio breadth with disciplined rationalization, ensuring that each addition serves a clear use case and does not dilute positioning. Align manufacturing and sourcing decisions with channel and regional expectations, since OEM-quality content, dealer support, and service models differ meaningfully across markets.
Hitch Lock Market
For Investors
Evaluate exposure not just by top-line growth but by the defensibility of product architecture, channel relationships, and quality track record. Companies with vehicle-specific fit capabilities, strong integration content, and credible safety performance are better positioned to sustain margins as scrutiny rises. Consolidation that expands accessory and solution breadth can create value if it improves ecosystem completeness without introducing quality or brand confusion. Monitor regulatory signals closely, since changes in recall dynamics, labeling expectations, or towing safety standards can alter cost structures and competitive positioning. In portfolio construction, favor businesses that combine scale in high-volume categories with specialization where performance demands justify premium positioning.
For Procurement and Channel Partners
Source decisions should weigh total cost of reliable installation and support, not price alone. Verify vehicle-specific compatibility, load rating clarity, and accessory compatibility before committing to volume, since mismatched components create service friction and end-user dissatisfaction. Prefer suppliers that provide clear installation guidance, consistent specification communication, and responsive support, because these factors reduce returns and improve sell-through. Balance breadth and depth in inventory by focusing on high-velocity fitments and safety-critical components, while keeping access to specialized configurations for commercial and specialty applications. Where possible, request documentation that supports traceability and quality assurance, especially for components that influence load security.
Closing Perspective
The trailer hitch market is moving from broad expansion to a more selective phase where value accrues to those who combine engineering rigor, integration capability, and disciplined execution. The market’s scale and concentration indicate that leadership positions are durable, but they are not immune to reassessment when safety expectations rise, vehicle architectures change, and cost pressures intensify. The forward opportunity lies in aligning product design with real use cases, building ecosystems that reduce installation and compatibility friction, and treating quality and traceability as strategic assets rather than overhead.
For organizations seeking to act on these dynamics with finer granularity, the most useful next step is to examine detailed segmentation, regional demand patterns, and company-specific profiles that sit beyond the overview picture. A complete research report can provide the segmented data and context needed to shape product roadmaps, channel plans, and investment theses with greater precision. The strategic direction is clear: in a market where safety, fit, and integration increasingly define competitive standing, timely intelligence is not optional for decision-makers who want to move with confidence.
For detailed analysis of this topic, please visit the official page: Trailer Hitch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Semiconductor Lasers Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The semiconductor lasers market has evolved from a specialized component niche into a foundational enabler across multiple high-growth industries. With the total market valuation reaching approximately $9.5 billion in 2025 and projected to expand toward $17.2 billion by 2032, the sector is tracking a compound annual growth rate of 8.8 percent. This trajectory reflects sustained demand from communications infrastructure, industrial processing, consumer electronics, and emerging applications in automotive sensing and medical technologies. The revenue progression from the early 2020s through the mid-2020s demonstrates consistent upward momentum, with incremental acceleration as downstream industries scale their adoption of laser-based solutions.
Despite this growth narrative, the market operates within a complex environment shaped by several structural tensions. Understanding these challenges is essential for executives evaluating entry points, expansion strategies, or capital allocation decisions.
Supply Chain Vulnerability and Geopolitical Realignment
The semiconductor lasers supply chain is deeply intertwined with broader semiconductor manufacturing ecosystems. Recent regulatory initiatives, including proposed restrictions under the Federal Acquisition Regulation Council targeting federal procurement of electronic products reliant on semiconductors, have introduced compliance complexity for component suppliers. Concurrently, NIST has launched initiatives to address measurement gaps in semiconductor supply chain visibility, with direct implications for optical frequency-related devices and laser components. These regulatory movements, combined with SEMI's ongoing efforts to benchmark supply chain resilience metrics, signal a structural shift toward greater scrutiny of component provenance, manufacturing location, and technology transfer pathways.
For laser manufacturers and their customers, this environment creates a dual pressure: maintaining production efficiency while navigating an increasingly fragmented regulatory landscape. Companies with concentrated supply chains or single-source dependencies face heightened exposure to disruption.
Technology Convergence and Application Fragmentation
The market is experiencing simultaneous convergence and fragmentation. On one hand, advances in complementary technologies such as high-precision optics, advanced packaging, and photonic integration are expanding the technical boundaries of what semiconductor lasers can achieve. On the other hand, end-use applications are diversifying rapidly, with communications, industrial processing, medical procedures, consumer electronics, and automotive sensing each imposing distinct performance requirements, reliability standards, and cost constraints.
This fragmentation challenges manufacturers to balance breadth of portfolio against depth of specialization. Companies that spread resources too thinly across incompatible application segments risk diluted competitive positioning, while those that over-index on a single vertical may miss cross-sector technology transfer opportunities.
Concentration Dynamics and Competitive Pressure
Market concentration remains notable, with the top three participants accounting for approximately 48.5 percent of revenue and the top five representing roughly 67.2 percent. This level of concentration reflects the technical barriers to entry, capital intensity of manufacturing, and the value of established customer relationships in precision applications. However, it also masks underlying shifts, including the emergence of specialized players targeting niche wavelengths, packaging formats, and application-specific configurations.
The presence of both large diversified photonics companies and focused specialists creates a dynamic competitive environment where differentiation increasingly depends on application expertise, supply chain agility, and the ability to co-develop solutions with end customers rather than competing solely on component specifications.
Key Drivers Analysis
The growth trajectory of the semiconductor lasers market is not accidental; it is being pulled by interconnected forces across technology, policy, demand behavior, and supply chain economics. Examining these drivers reveals where momentum is strongest and where strategic positioning will matter most.
Technology Innovation and Wavelength Expansion
Technological progress in semiconductor lasers continues to center on three dimensions: wavelength diversification, power scaling, and form-factor optimization. Recent developments illustrate this trajectory clearly. In early 2026, IPG Photonics introduced new high-power laser platforms on a rack-integrated architecture and demonstrated Deep UV at 266 nm alongside green laser sources targeted at precision micro-machining in semiconductor manufacturing. This expansion into shorter wavelengths and integrated packaging reflects a broader industry push toward laser solutions capable of finer feature resolution and more complex material processing.
Simultaneously, Nuvoton Technology has moved aggressively into high-power violet and UV laser diodes. The company commenced mass production of a 402 nm, 4.5 W violet laser diode in a TO-9 package for advanced semiconductor packaging and lithography systems, followed by the introduction of a 379 nm, 1.0 W UV device in a compact 9.0 mm CAN package for maskless lithography. These product milestones underscore a growing emphasis on UV and violet wavelengths for semiconductor packaging applications, where finer patterning, improved edge quality, and reduced thermal impact are driving adoption.
Beyond wavelength expansion, innovation in packaging and integration is enabling new deployment models. Compact packages, higher wall-plug efficiency, and improved thermal management are making semiconductor lasers more viable in space-constrained or thermally sensitive environments, including automotive sensing modules and portable medical devices.
Policy and Regulatory Environment
Policy developments are shaping both the cost structure and the strategic calculus for semiconductor laser participants. The CHIPS-related R&D initiatives and supply chain visibility programs introduced by NIST are creating new frameworks for measurement, standardization, and documentation that affect optical frequency devices and laser components. While these programs aim to strengthen overall ecosystem resilience, they also impose additional compliance and documentation requirements that can raise the cost of participation, particularly for smaller manufacturers.
At the same time, federal procurement restrictions proposed by the FAR Council are influencing purchasing behavior among government-dependent customers and their downstream suppliers. Companies that serve segments with significant government exposure must factor compliance requirements into product design, supply chain configuration, and customer engagement strategies. The broader implication is that regulatory alignment is becoming a competitive consideration, not merely a legal obligation.
Geopolitical dynamics are also filtering into the market. Germany-based TRUMPF Group, a key supplier of advanced laser technology components used in EUV lithography systems, faces potential collateral exposure from US semiconductor supply chain controls affecting complex manufacturing ecosystems. This illustrates how policies directed at broader semiconductor trade can have cascading effects on specialized laser and photonic component producers, even when those producers are not the direct target of restrictions.
Demand-Side Shifts Across End-Use Segments
Demand for semiconductor lasers is being reshaped by evolving requirements in several key segments. In communications, the expansion of optical networking capacity and the deployment of higher-density datacom infrastructure are driving continued reliance on laser diodes for signal transmission. Coherent's demonstration of a broad range of InP technology innovations, including semiconductor lasers for datacom and optical networking at OFC 2026, highlights how material platform advancements are aligning with the performance demands of next-generation networking architectures.
In industrial applications, the push toward finer feature sizes, higher throughput, and more versatile material processing is expanding the role of semiconductor lasers in cutting, welding, marking, and micro-machining. The trend toward automation and precision manufacturing in sectors ranging from electronics assembly to advanced materials processing is reinforcing demand for laser sources that combine high power with tight beam control and repeatability.
Consumer electronics and automotive sensing represent additional demand vectors. The proliferation of sensing functions in vehicles, including LiDAR and advanced driver assistance systems, is creating sustained interest in laser diodes optimized for ranging and environmental perception. In consumer electronics, applications spanning AR/VR display technologies, facial recognition, and haptic feedback are contributing to demand for compact, wavelength-specific laser solutions. Medical applications, including surgical procedures, diagnostic imaging, and therapeutic devices, continue to expand as laser reliability, safety, and cost profiles improve.
Supply Chain and Cost Structure Dynamics
The economics of semiconductor laser production are being influenced by shifts in raw material availability, manufacturing localization, and the cost of compliance. As regulatory frameworks increasingly emphasize supply chain visibility and resilience, companies are re-evaluating the tradeoffs between efficiency and redundancy. Some manufacturers are diversifying sourcing strategies, qualifying alternative suppliers, or investing in more transparent documentation processes to reduce vulnerability to disruption.
Worldwide Semiconductor Military Laser Market
At the same time, the cost of achieving performance targets in specialized wavelengths and packaging formats is rising for certain segments, particularly where materials, epitaxial growth, or precision packaging require specialized capabilities. This cost pressure is reinforcing the advantage of players with established process expertise and integrated manufacturing capabilities, while also creating opportunities for companies that can deliver application-specific solutions with lower total cost of ownership through improved reliability, reduced integration complexity, or longer service life.
PW Consulting Automotive & Machinery Research Center
Competitive Landscape and Leading Strategies
The competitive environment in the semiconductor lasers market is characterized by a mix of large diversified photonics companies, focused specialists, and regional champions. Understanding the strategic positioning of these players provides insight into where differentiation is being created and how the competitive frontier is shifting.
Diversified Leaders and Systems-Level Positioning
Companies such as IPG Photonics, Coherent, TRUMPF Group, and nLIGHT occupy positions that emphasize scale, application breadth, and systems-level integration. IPG Photonics manufactures high-power fiber lasers, diode laser systems, and ultrafast laser sources for industrial semiconductor processing, material cutting, and welding. Its recent platform introductions and demonstration of Deep UV and green lasers for micro-machining reflect a strategy centered on expanding wavelength coverage and integrating laser sources into more complete solutions for precision manufacturing.
Coherent develops and supplies laser diodes, VCSELs, and semiconductor laser systems spanning datacom, industrial precision manufacturing, semiconductor capital equipment, and LiDAR applications. The company's demonstration of InP technology innovations at OFC 2026 illustrates a focus on material platform advancement and alignment with high-growth communications and networking markets. Coherent's breadth across multiple application verticals positions it to capture technology transfer opportunities and cross-sell into adjacent segments.
nLIGHT develops high-power semiconductor fiber lasers and diode laser systems for defense, advanced manufacturing, and industrial processing. Its emphasis on high-power semiconductor fiber lasers reflects a strategy of combining semiconductor efficiency with fiber delivery benefits for demanding industrial and defense applications. TRUMPF Group offers semiconductor laser systems and solutions for industrial material processing, laser welding, and cutting, leveraging its broader reputation in industrial laser systems to reinforce customer relationships and integrate laser sources into complete processing setups.
Specialists and Application-Focused Players
A second tier of competitors competes through depth in specific wavelengths, package formats, or application domains. ams-OSRAM provides edge-emitting laser diodes, VCSELs, and semiconductor laser solutions for automotive LiDAR, advanced driver assistance systems, and high-performance sensing. Its positioning reflects a focus on sensing applications where reliability, wavelength stability, and integration compatibility with automotive-grade systems are critical.
Nichia offers high-power laser diodes and semiconductor laser products for industrial, automotive, and consumer applications including AR/VR and material processing. The company's presence across both industrial and consumer segments highlights the value of wavelength expertise and manufacturing scale in serving diverse end markets. Furukawa Electric manufactures high-output DFB laser diodes and semiconductor laser chips for signal light sources and optical communications, emphasizing performance in communications applications where wavelength precision and signal integrity are paramount.
Nuvoton's recent moves into high-power violet and UV laser diodes for semiconductor packaging and lithography illustrate a strategy of targeting specific application gaps with tailored wavelength and package solutions. By introducing devices in compact CAN and TO-9 packages optimized for packaging and lithography systems, Nuvoton is building a position in an application segment where wavelength, power, and form factor must align closely with equipment design requirements.
Sheaumann Laser designs and manufactures single-mode and multimode continuous-wave diode lasers and modules for medical, industrial, defense, and space applications. Excelitas Technologies manufactures pulsed laser diodes and arrays for industrial, medical, and defense illumination and sensing applications. RPMC Lasers supplies laser diodes, pulsed lasers, and semiconductor laser modules for medical, defense, research, and industrial OEM applications. These companies illustrate how focused portfolios can create defensible positions in applications where performance consistency, qualification history, and customer support are valued as highly as raw component specifications.
Sacher Lasertechnik provides narrow-linewidth and tunable semiconductor laser systems for scientific, industrial, and quantum applications, representing a niche oriented toward precision and flexibility in demanding research and specialized industrial contexts. Hamamatsu Photonics supplies laser diodes, VCSELs, and semiconductor laser modules for scientific, industrial, and medical applications, leveraging its broader photonics expertise to serve segments that require tightly integrated component and module solutions.
Strategic Positioning and Differentiation
Across this landscape, several differentiation themes are emerging. One is wavelength and package specialization, where companies build advantage by optimizing for specific performance envelopes rather than competing broadly. A second is application co-development, where manufacturers engage closely with equipment makers and end users to shape laser specifications around real-world processing, sensing, or transmission requirements. A third is vertical integration and supply chain control, where companies reduce dependency on external suppliers for critical materials, epitaxial growth, or packaging to improve quality consistency and mitigate disruption risk.
The competitive frontier is also shaped by the tension between consolidation and specialization. Larger players may pursue acquisitions or partnerships to fill wavelength gaps, expand into adjacent application segments, or strengthen regional supply chain presence. At the same time, specialized entrants continue to find opportunities in underserved niches, particularly where emerging applications create demand for wavelengths, package formats, or reliability profiles that are not the primary focus of mainstream suppliers.
Future Trends and Commercial Implications
Looking ahead to the next three to five years, several trends are likely to shape the trajectory of the semiconductor lasers market and create distinct commercial opportunities for participants that align their strategies with these dynamics.
Trend One: Expansion of UV and Violet Wavelength Applications
The progression of high-power violet and UV laser diodes into semiconductor packaging, maskless lithography, and precision micro-machining points to a broader trend of shorter-wavelength adoption in manufacturing and processing applications. As feature sizes continue to shrink and process requirements demand finer control, reduced thermal 영향, and improved edge quality, UV and violet sources are likely to see increased penetration in packaging, lithography, and micro-machining workflows. This trend creates opportunities for manufacturers that can deliver reliable high-power devices in compact packages, as well as for equipment makers that integrate these sources into optimized processing platforms.
A related implication is that wavelength-specific expertise will become more valuable. Companies that can combine epitaxial growth, packaging, and application engineering for UV and violet wavelengths may capture premium positioning relative to generalist suppliers.
Trend Two: Integration and Co-Development as Competitive Levers
The increasing complexity of end-use applications is elevating the importance of integration and co-development. Semiconductor lasers are increasingly deployed not as isolated components but as part of systems that combine laser sources, beam delivery, control electronics, and application-specific optics. This shift favors manufacturers that can engage early in customer design cycles, offer reference architectures, and provide support for qualification and reliability testing. It also favors equipment and system makers that can differentiate through optimized integration rather than competing solely on individual component specifications.
For commercial players, this trend suggests that value capture is moving toward solution-level positioning. Companies that can reduce integration complexity, improve system-level reliability, or accelerate time-to-qualification may gain advantage even if component-level margins face pressure.
Trend Three: Supply Chain Reconfiguration and Regionalization
Regulatory developments, geopolitical tensions, and resilience benchmarking initiatives are likely to continue driving supply chain reconfiguration. Companies may increasingly evaluate manufacturing location, supplier diversification, and documentation transparency as strategic variables rather than purely operational decisions. This trend could create opportunities for regional suppliers that can offer localized production, faster responsiveness, and alignment with customer compliance requirements.
At the same time, the cost of managing a more complex supply chain environment may increase, particularly for smaller players with limited compliance and qualification resources. This dynamic could contribute to selective consolidation or partnership activity, as companies seek to share the burden of regulatory alignment and supply chain visibility.
Risks and Uncertainties
Several uncertainties could alter the trajectory of these trends. Regulatory scope and enforcement intensity remain variable, and the full impact of procurement restrictions and supply chain visibility requirements on component pricing and market access is still unfolding. Technology substitution risk persists, particularly if alternative light sources, integrated photonic approaches, or competing wavelength strategies gain traction in key applications. Demand momentum in specific segments, such as automotive sensing or consumer electronics, may fluctuate with product cycles, economic conditions, or changes in end-user adoption patterns. Finally, concentration in certain parts of the supply chain creates exposure to disruption if key materials, processes, or manufacturing nodes encounter constraints.
Strategic Recommendations for Decision Makers
For executives navigating this market, the priority is to align strategy with the forces that are most likely to shape value creation over the next several years. The following recommendations are intended to provide a starting point for more detailed planning.
UV Lasers Market
For Manufacturers and Component Suppliers
Focus on depth in high-growth wavelength and application segments where performance requirements are tightening and differentiation is achievable. Evaluate whether your portfolio balances breadth with enough specialization to command premium positioning in priority verticals. Invest in integration support, reference designs, and co-development capabilities that reduce the friction for customers adopting your laser sources in system-level applications. Review supply chain configuration with an eye toward resilience and compliance readiness, particularly if your customer base includes segments exposed to government procurement requirements or complex qualification processes.
For Investors and Strategic Allocators
Assess opportunities based on the alignment of technology positioning with demand momentum in communications, industrial processing, sensing, and packaging applications. Differentiated wavelength expertise, application-specific packaging, and integration capabilities are likely to be more durable sources of value than commodity positioning in crowded segments. Pay attention to regulatory exposure and supply chain resilience as factors that can affect long-term viability, particularly for companies serving government-adjacent markets or reliant on concentrated sourcing. Monitor the pace of specialization versus consolidation, as both pathways can create attractive entry or exit points depending on the segment and the player's strategic posture.
For Procurement and Sourcing Leaders
Prioritize suppliers that can demonstrate not only component specifications but also application support, qualification documentation, and supply chain transparency. In an environment where regulatory alignment and resilience are increasingly scrutinized, the total cost of ownership may depend as much on integration risk, qualification speed, and continuity assurance as on unit price. Engage early with laser suppliers during equipment or system design to optimize wavelength, package, and performance tradeoffs rather than specifying components in isolation. Build multi-source strategies where feasible, particularly for mission-critical or high-volume applications, to reduce exposure to single-supplier disruption.
Closing Perspective
The semiconductor lasers market is entering a phase where growth is being reinforced by technology diversification, application expansion, and a reconfiguration of supply chain and regulatory expectations. The companies that capture the most value will be those that can combine wavelength and application expertise with integration capability, supply chain resilience, and the agility to respond to shifting regulatory and geopolitical conditions. For decision makers seeking a more granular understanding of segment-level dynamics, regional nuances, competitive benchmarks, and customized strategic pathways, a deeper examination of the full research report can provide the detailed data and structured analysis needed to inform precise action.
For detailed analysis of this topic, please visit the official page: Semiconductor Lasers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Lifeboat Market 4.5% CAGR Outlook: How Concentration and Regional Dynamics Reshape Growth to 2032
By pmarketresearch, 2026-09-21
The Lifeboat Market: Strategic Shifts and Commercial Opportunities in a Maturing Industry
The global lifeboat market has evolved from a compliance-driven segment into a strategically significant component of marine safety infrastructure. After growing from approximately USD 170.0 million in 2020 to an estimated USD 220.0 million in 2025, the market is projected to expand at a compound annual growth rate of 4.5 percent through 2032. While the growth trajectory is steady, the real story lies in the structural shifts reshaping how lifeboats are designed, regulated, serviced, and integrated into broader vessel safety systems. For executives, investors, and operations leaders, understanding these dynamics is no longer optional; it is a prerequisite for making informed capital allocation, procurement, and product development decisions.
At a high level, the market is characterized by concentrated demand, increasingly stringent safety standards, and a growing emphasis on reliability over nominal compliance. The revenue base is anchored by lifeboat equipment itself, with passenger transportation representing the dominant end-use context. Regionally, demand is distributed across established maritime hubs and emerging safety-conscious markets, reflecting both regulatory maturity and varying fleet modernization cycles. What matters most, however, is not the headline figures alone, but the way these figures are being reshaped by technology, regulation, and operational expectations.
Core Challenges at the Current Inflection Point
The industry is navigating a set of overlapping pressures that are redefining competitive advantage and operational risk.
- Regulatory tightening around safety performance. Recent amendments to release mechanism standards and operational speed requirements are forcing manufacturers and operators to revalidate existing designs. Compliance is no longer a checkbox exercise; it is becoming a continuous validation challenge that affects design architecture, service protocols, and liability exposure.
- Performance validation under real-world conditions. Independent testing has raised concerns about stability and flooding risks in certain configurations when lifeboats are not fully loaded or are occupied under specific seating arrangements. This creates a broader market implication: design claims must be supported by reproducible testing, and procurement teams are increasingly scrutinizing evidence beyond baseline certification.
- Service and maintenance complexity. Guidance emphasizing manufacturer-certified personnel for the examination and operational testing of launching appliances and release gear is raising the bar for after-sales support. The market is shifting toward controlled service ecosystems, which affects cost structures, supplier relationships, and the economics of fleet maintenance over a vessel’s lifecycle.
Together, these challenges point to a market that is maturing rapidly. The winners will be those who can translate regulatory and performance pressure into product reliability, service competence, and transparent engineering evidence.
Key Drivers Reshaping the Lifeboat Market
The market’s direction is being shaped by four interconnected drivers. Each one carries implications for product strategy, procurement planning, and investment timing.
Technology Innovation and Design Evolution
Engineering improvements are steadily raising the bar for launch reliability, Structural resilience, and operator control. Advances in release mechanisms, hull configurations, and integration with davit systems are reducing failure modes that historically complicated launch operations. Equally important, the industry is seeing a stronger focus on designs that perform consistently across load conditions rather than only meeting minimum test scenarios. This matters because lifeboat performance is increasingly judged on operational reliability, not just certification compliance.
Regulatory and Standards Environment
Regulatory momentum is accelerating. New requirements addressing release mechanisms and lowering operational speeds are prompting redesigns and re-verification campaigns. In parallel, stronger expectations around maintenance and servicing are formalizing who can inspect and test launching appliances and release gear, and under what conditions. These changes are raising the importance of traceable service records, manufacturer-aligned maintenance pathways, and documented component integrity. The regulatory environment is effectively tightening both the design and service sides of the market.
Demand-Side Behavior and Fleet Expectations
Operators are increasingly treating lifeboats as part of an integrated safety system rather than isolated equipment. This is driven by a broader mindset in which passenger transport operators, offshore operators, and naval customers want assurance that evacuation assets will perform under stress, with predictable handling and reduced risk of flooding or instability. Procurement decisions are therefore placing greater weight on demonstrated performance, support coverage, and the ability to align lifeboat selection with vessel-specific operating profiles. The result is a more discerning buyer environment in which reputation for reliability and evidence of testing can influence selection as much as price.
Cost Structure and Service Economics
Lifecycle economics are becoming more important as service requirements become more specialized. When maintenance and testing must be performed by certified personnel or through authorized service pathways, operators face stronger incentives to plan for total cost of ownership rather than purchase price alone. For manufacturers, this creates opportunities to build value around service contracts, parts availability, and predictable maintenance schedules, while also increasing the importance of supply chain reliability for critical components. Cost structures are shifting from a one-time equipment transaction toward a longer-term service relationship.
Competitive Landscape and Leading Strategies
The market remains heavily concentrated, with a small group of established players holding a substantial share of revenue and technical influence. This concentration reflects the high barriers associated with certification, engineering expertise, service networks, and long-standing customer relationships in maritime and naval segments.
Strategic Positioning of Key Players
- VIKING Life-Saving Equipment A/S has built a strong reputation around integrated survival solutions, including free-fall lifeboats, fast rescue boats, and davit systems suited to merchant and offshore vessels. Its positioning emphasizes engineered reliability and the ability to deliver coordinated equipment packages rather than standalone products.
- Survitec Group Limited brings breadth across survival craft technology, including lifeboats, liferafts, and evacuation systems. Its strategic value lies in offering a wider safety ecosystem, which can simplify procurement and support for customers seeking multiple evacuation assets from a coordinated supplier base.
- Fassmer GmbH & Co. KG is recognized for lifeboats, rescue boats, and life-saving equipment tailored to cruise, ferry, and offshore applications. Its approach often centers on application-specific engineering and long-cycle project execution, with recent activity reinforcing its role in specialized training and operational boat programs.
- Zodiac Nautic Group contributes expertise in inflatable and rigid-inflatable boats alongside life rafts and safety equipment. Its competitive advantage is rooted in adaptable hull technologies and a strong association with versatile watercraft platforms that can support different operational needs.
- Ningbo New Marine Lifesaving Equipment Co., Ltd. participates through fast rescue boats, lifeboats, davits, and launching appliances, reflecting the growing presence of capable manufacturers in the broader marine safety supply chain. Its relevance lies in expanding manufacturing capacity and offering competitive equipment solutions across launch and support components.
Market Evolution and Strategic Trends
Several patterns are becoming visible in how the competitive landscape is evolving.
- Consolidation of service value. As maintenance and testing expectations tighten, suppliers that can offer credible, manufacturer-aligned service coverage are gaining strategic importance. The market is increasingly rewarding integrated product-and-service propositions over fragmented equipment sales.
- Differentiation through evidence and engineering. In an environment where performance questions are being raised through testing and regulatory scrutiny, transparency in design rationale, validation data, and service qualifications becomes a competitive asset.Providers that can demonstrate robust engineering support are better positioned to win demanding contracts.
- Selective new entry and regional expansion. While the top tier remains concentrated, broader manufacturing capacity and regional supply options are expanding. Newer or regional participants can compete by addressing specific cost, lead-time, or application needs, but they must also meet rising expectations for certification, service competence, and long-term support reliability.
- Project-driven cycles and institutional demand. Award activity in specialized segments, such as training boat programs, illustrates how institutional demand can create targeted growth opportunities. These projects often require strong execution credibility and can reinforce a supplier’s standing in demanding markets.
For buyers and investors, the practical implication is that competitive advantage is shifting from product presence alone to a broader combination of engineering credibility, service readiness, and the ability to reduce operational risk across the equipment lifecycle.
Future Trends and Commercial Implications for 2026–2032
Looking ahead, the market is likely to be shaped by a small number of high-impact trends. Each trend carries both opportunity and uncertainty.
Trend 1: Performance Standards Will Drive Redesign and Revalidation Activity
Regulatory amendments focused on release mechanisms and operational speed, combined with testing findings related to stability and flooding risk in certain conditions, are likely to sustain a wave of design refinement and verification work. This creates near-term demand for engineering support, testing coordination, and product updates, while also encouraging longer-term investment in more robust launch and stability characteristics. Commercially, this favors organizations that can respond quickly with credible engineering changes and clear documentation.
Trend 2: Service and Maintenance Will Become a Central Commercial Battleground
As servicing expectations increasingly emphasize certified personnel and manufacturer-aligned examination and testing, the after-sales segment will grow in strategic importance. Operators will look for predictable maintenance pathways, component availability, and support coverage that reduces downtime and compliance risk. For manufacturers and service providers, this means revenue and customer loyalty will depend more on lifecycle support quality than on initial equipment sales alone.
Worldwide Wafer Boat Market
Trend 3: Procurement Will Shift Toward Integrated Safety Assurance
Buyers are expected to place greater value on coordinated solutions that combine lifeboats, launching appliances, and related evacuation elements with consistent support standards. The trend is toward fewer, more trusted procurement relationships for safety-critical assets, especially where operators seek to simplify accountability and reduce integration risk. This benefits suppliers that can offer end-to-end assurance and penalizes those that are seen as strong on product but weaker on systemic support.
Floating Dock Market
Risks and Uncertainties
Despite the constructive outlook, several uncertainties deserve attention.
- Regulatory interpretation and enforcement may vary by region and flag state, creating uneven compliance timelines and different speed of adoption across markets.
- Testing-related scrutiny could accelerate redesign costs for certain product lines and create short-term margin pressure while validation cycles are completed.
- Service qualification requirements may constrain the supply base if certified capacity does not expand in step with demand, potentially increasing turnaround times and support costs.
- Demand cyclicality in shipping, offshore, and naval programs can influence the pace of new equipment orders, even as retrofit and service demand remains more resilient.
Actionable Guidance for Decision-Makers
The market’s next phase will reward organizations that align strategy with the direction of regulation, performance expectations, and service economics. The following priorities are most relevant for different stakeholder groups.
PW Consulting Automotive & Machinery Research Center
For Manufacturers and Equipment Suppliers
- Strengthen engineering evidence packages that address stability, release behavior, and performance across load conditions. Transparent validation support is becoming a differentiator in competitive procurements.
- Invest in certified service capacity and clear maintenance pathways. Lifecycle support is increasingly a commercial prerequisite, not an optional add-on.
- Prepare for redesign and revalidation workloads triggered by updated release mechanism and speed requirements. Early readiness can convert regulatory pressure into share gains.
For Investors and Capital Allocators
- Focus on companies with credible service ecosystems and strong engineering reputations, since lifecycle support and compliance readiness are becoming central to long-term value creation.
- Monitor project-driven demand signals, especially in specialized training and institutional programs, as indicators of execution capability and market access.
- Assess exposure to redesign costs and certification cycles, which can affect short-term margins even when medium-term demand remains healthy.
For Procurement Teams and Vessel Operators
- Evaluate total cost of ownership with greater weight on service coverage, testing qualifications, and parts availability rather than purchase price alone.
- Request evidence of performance validation under conditions relevant to your operating profile, particularly where stability and flooding risk have become points of scrutiny.
- Simplify accountability by favoring suppliers that can support integrated evacuation systems and provide consistent maintenance standards across equipment types.
Effective decisions in this market require more than headline market size or broad growth estimates. Segmentation behavior, regional demand patterns, pricing dynamics, service economics, and company-level execution all influence who captures value as the market matures. Detailed breakdowns of these variables can help translate the strategic directions outlined here into procurement planning, product roadmap choices, and investment screening with greater precision. For decision-makers seeking a sharper view of market segments, competitive positioning, and forward demand scenarios, the full research report offers a more granular basis for action.
For detailed analysis of this topic, please visit the official page: Lifeboat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com