

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Satellite Market Viewed Through 6.98% CAGR and 344.8 Million Regional Growth Dynamics

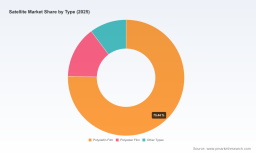
Navigating the Satellite Market: Strategic Trends and Commercial Opportunities Through 2032
The satellite industry has entered a phase of accelerated transformation, where technological maturation, regulatory modernization, and shifting demand patterns are reshaping competitive boundaries. Market valuation has expanded from approximately $163.15 million in 2020 to a projected $215.0 million in 2025, with forward estimates placing the sector at $344.8 million by 2032. This trajectory reflects a compound annual growth rate of 6.98 percent over the 2026–2032 forecast window, signaling sustained expansion rather than cyclical volatility. Such growth is not merely a function of incremental capacity additions; it represents a structural reconfiguration of how space-based infrastructure is designed, deployed, and monetized. For executives and investors, the critical question is no longer whether the market will grow, but which subsegments, geographies, and business models will capture disproportionate value as the ecosystem matures.
Behind the headline figures lies a more complex reality. The industry is navigating several inflection points that will determine competitive outcomes over the next half decade. Manufacturing throughput and component scaling remain pressing constraints, particularly as constellation architectures grow in size and operational complexity. Regulatory frameworks are evolving from prescriptive limits to performance-based models, creating both compliance flexibility and new coordination challenges across operators. Additionally, the economics of space deployment are shifting as launch cadence increases and reusable platforms reduce per-kilogram costs, yet these gains are unevenly distributed across suppliers and mission types. These dynamics are not isolated headwinds; they are interconnected forces that will separate agile, vertically integrated players from those reliant on legacy supply chains or static service models.
Key Drivers Reshaping the Satellite Landscape
Technological Innovation and Mission Architecture Evolution
The shift toward proliferated low Earth orbit architectures is fundamentally altering satellite design philosophy. Rather than relying on a small number of high-value, long-lifecycle platforms, operators are increasingly deploying modular, software-defined constellations that prioritize rapid iteration, in-orbit reconfigurability, and scalable manufacturing. This architectural transition is supported by advances in optical inter-satellite links, autonomous orbital maneuvering, and standardized payload interfaces, which collectively reduce integration lead times and improve network resilience. Recent product introductions illustrate this trajectory: the deployment of direct-to-cell broadband satellites in early 2026 expanded emergency and consumer connectivity capabilities without requiring ground terminal upgrades, demonstrating how payload innovation can unlock adjacent service markets. For manufacturers and system integrators, the opportunity lies in designing platforms that accommodate frequent software updates, cross-constellation interoperability, and rapid payload swaps, rather than optimizing solely for unit cost reduction.
Regulatory Modernization and Spectrum Coordination
Policy frameworks are transitioning from rigid emission limits to performance-based spectrum sharing models, a shift that carries significant implications for network planning and capital allocation. In early 2026, regulators adopted a modernized framework for non-geostationary and geostationary spectrum sharing in key broadband bands, replacing legacy interference thresholds with criteria tied to actual network performance. This approach grants operators greater flexibility in orbital slot utilization and frequency coordination, but it also raises the analytical burden for compliance strategy and interference mitigation. Parallel adjustments, including differentiated licensing structures for small versus large constellations and clarified end-of-life deorbit obligations, are reshaping entry barriers and lifecycle cost assessments. Companies that invest early in spectrum strategy, orbital debris management, and regulatory engagement will secure faster deployment timelines and lower long-term operational risk, while those treating compliance as a afterthought may face costly redesigns or licensing delays.
Demand-Side Shifts Across Commercial and Government Sectors
Demand patterns are diversifying beyond traditional communications and Earth observation use cases. Enterprise connectivity requirements are expanding into maritime, aviation, remote industrial operations, and mobile platforms, driven by the need for resilient backhaul and real-time telemetry in environments where terrestrial infrastructure is impractical. Simultaneously, government and defense procurement is emphasizing rapid delivery, proliferated architectures, and multi-orbit mission flexibility, reflecting a strategic preference for distributed assets over concentrated, high-cost platforms. Contract activity in early 2026 highlighted this dual demand stream: significant delivery milestones for transport-layer satellites supporting government programs coincided with finalized commercial constellation agreements, indicating that public and private capital are converging on similar architectural principles. For service providers and platform suppliers, the strategic implication is clear: product roadmaps must accommodate both high-reliability mission requirements and cost-sensitive commercial scaling, often within the same architectural family.
Supply Chain Dynamics and Manufacturing Scale-Up
The economics of satellite production are being recalibrated as demand volume increases and component standardization gains traction. Industry reporting from mid-2025 noted a 17 percent rise in satellite manufacturing revenue alongside a dominant U.S. market share, underscoring how regional capability concentration and supply chain maturity can accelerate deployment. At the same time, exporters and suppliers are navigating evolving trade controls, with certain spacecraft and servicing items experiencing reduced licensing friction for select partner markets. These shifts create a window for suppliers that can deliver qualified subsystems at scale, maintain stringent quality assurance, and align production schedules with constellation deployment cadence. Cost structure advantages will increasingly accrue to organizations that secure long-term subsystem agreements, invest in automated assembly and test processes, and mitigate single-source dependencies for critical components such as propulsion modules, power systems, and phased-array payloads.
Competitive Landscape and Strategic Positioning
Established Systems Integrators and Platform Leaders
Large aerospace and defense primes continue to anchor the market through comprehensive system integration capabilities, deep mission engineering expertise, and established relationships with government and commercial buyers. Their strategic positioning typically emphasizes end-to-end delivery spanning bus platforms, payloads, ground interfaces, and mission operations, which reduces customer integration risk and supports complex, multi-year programs. Differentiators in this tier include advanced manufacturing scale, secure production environments, and the ability to manage stringent reliability and certification requirements. These companies are increasingly adapting to proliferated architectures by offering standardized platforms, modular payload integration, and faster delivery cycles, while preserving their advantage in high-complexity missions where performance margins and compliance rigor remain paramount.
Specialized Operators and Connectivity Enablers
A distinct tier of operators and subsystem specialists is expanding the commercial surface area of the market by focusing on constellation services, mobile tracking systems, broadband platforms, and end-to-end connectivity solutions. Their competitive edge often stems from vertical service integration, rapid product iteration, and close alignment with specific user segments such as mobile communications, remote enterprise networking, and IoT telemetry. Recent commercial activity illustrates this focus: mobile tracking antenna providers have secured advance orders for LEO and MEO tracking systems, signaling growing demand for vehicle-based and transportable connectivity that can follow dynamic orbital pathways. Similarly, broadband platform operators are extending service reach through direct-to-device capabilities and ecosystem partnerships that reduce reliance on specialized ground hardware. These players are reshaping buyer expectations around deployment speed, service flexibility, and total cost of ownership, forcing traditional suppliers to respond with more agile commercial terms and modular offerings.
TV Market
Market Evolution: Consolidation, Differentiation, and New Entrants
The competitive structure is moving toward a hybrid model in which large integrators, specialized operators, and nimble platform startups coexist, each competing on different axes of value. Consolidation is likely where scale economics, spectrum access, and multi-orbit capability become decisive, particularly for operators seeking to amortize network costs across large user bases. At the same time, differentiation is intensifying around software-defined payloads, rapid manufacturing pipelines, and niche mission solutions that address specific defense, scientific, or commercial requirements. New entrants are gaining traction by leveraging standardized bus architectures, commercial-off-the-shelf component strategies, and focused service propositions that bypass the cost structures of legacy programs. The net effect is a market where incumbents must accelerate product cycle times and expand commercial flexibility, while entrants must prove reliability, supply continuity, and mission-grade performance to secure sustained contracts. Strategic positioning will increasingly depend on how effectively companies balance scale with specialization, and how quickly they can translate technical capability into deployable, revenue-generating service models.
Forward Outlook: Three Defining Trends for the Next Three to Five Years
The first defining trend is the acceleration of multi-orbit, software-defined networks that blend LEO, MEO, and GEO assets into coordinated service layers. As spectrum sharing becomes performance-based and inter-satellite linking matures, operators will be able to route traffic dynamically across orbits, improving latency, coverage, and resilience without proportionally increasing satellite count. This creates commercial opportunities in network orchestration, payload virtualization, and cross-orbit service integration, while challenging suppliers to deliver interoperable interfaces and secure data-handling architectures. The primary risk is coordination complexity: as networks multiply, interference management, orbital slot allocation, and standards alignment will require sustained industry cooperation and proactive regulatory engagement.
LEO Satellite Market
The second trend is the continued pressure on manufacturing throughput and subsystem standardization as constellation programs scale. Buyers will increasingly favor suppliers that can demonstrate repeatable production cycles, qualified component inventories, and transparent lead-time commitments. Companies that invest in automation, modular test flows, and long-term subsystem partnerships will secure margin stability and preferential positioning in large-scale procurements. The uncertainty lies in supply chain concentration and export control variability; shifts in licensing scope or component availability can quickly alter cost assumptions and deployment schedules, making diversification and contingency planning essential.
The third trend is the expansion of service monetization beyond traditional bandwidth leasing into vertical-specific connectivity, mobile tracking, and integrated telemetry solutions. Direct-to-device capabilities, transportable antenna systems, and end-to-end platform offerings are lowering adoption barriers for enterprise, maritime, aviation, and government users who previously faced high terminal costs or limited coverage. This opens addressable market growth for operators and equipment suppliers that can package hardware, software, and service operations into unified solutions. The commercial risk is fragmentation: as more players introduce niche offerings, differentiation may erode unless companies can sustain clear performance advantages, reliable service-level commitments, and scalable support infrastructure.
Strategic Guidance for Decision-Makers
For satellite manufacturers and subsystem suppliers, the priority is to align product roadmaps with proliferated, multi-orbit demand while protecting margin through standardization and supply continuity. Investing in modular platform design, repeatable assembly processes, and qualified component pipelines will reduce integration risk and position suppliers for large-scale constellation awards. Concurrently, proactive engagement on spectrum coordination, end-of-life compliance, and export licensing will shorten deployment timelines and reduce operational uncertainty. Organizations that treat these capabilities as core competitive assets, rather than ancillary compliance tasks, will be better equipped to capture value as procurement cycles accelerate.
For investors and strategic capital allocators, the most resilient opportunities will likely emerge where technical capability, regulatory readiness, and scalable commercial models intersect. Due diligence should prioritize suppliers and operators with demonstrated manufacturing throughput, clear spectrum and licensing strategies, and service architectures that can adapt across orbit regimes and user segments. Allocation decisions should weigh not only unit economics and contract pipelines, but also exposure to supply concentration, compliance evolution, and standards fragmentation. Capital deployed into companies that can harmonize hardware scale with software-defined service delivery is more likely to benefit from the structural expansion projected through the end of the decade.
PW Consulting Automotive & Machinery Research Center
For procurement leaders and enterprise buyers, the immediate objective is to evaluate total cost of ownership across hardware, service, and lifecycle dimensions rather than focusing narrowly on upfront terminal or bandwidth pricing. Engaging suppliers with proven multi-orbit interoperability, mobile and transportable connectivity options, and transparent service-level frameworks will reduce integration risk and improve resilience in remote or mobile operations. Buyers should also monitor regulatory and licensing developments that affect spectrum availability, deorbit obligations, and export eligibility, as these factors can materially influence deployment timing and long-term operating costs.
Detailed segmentation data, competitive benchmarking, and customized scenario modeling can further sharpen these decisions by translating market-level trends into segment-specific priorities and investment thresholds. Access to comprehensive research supporting the trajectory from 2026 through 2032 can help decision-makers validate assumptions, compare supplier positioning, and align procurement or capital strategies with the most probable growth pathways.
For detailed analysis of this topic, please visit the official page: Satellite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com