

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
EVP Market at 7.2% CAGR: Why the $300M Shift to 2032 Changes EV Strategy

The Strategic Evolution of the Automotive Electric Vacuum Pump Market: Trends and Commercial Opportunities
The automotive electric vacuum pump (EVP) market is undergoing a structural transformation driven by electrification, tightening emissions mandates, and the growing complexity of brake and engine management architectures. As automakers transition from mechanically dependent vacuum sources to electrically actuated systems, the EVP has evolved from a peripheral auxiliary component into a critical node in vehicle safety, efficiency, and emissions compliance. The segment has expanded from approximately $116 million in 2020 to an estimated $186 million in 2025, with forward projections indicating a compound annual growth rate of 7.2 percent through 2032. This trajectory reflects more than steady demand growth; it signals a recalibration of how vehicles generate, manage, and deploy vacuum across braking, emission, and engine control functions.
For executives, investors, and procurement leaders, understanding the EVP market requires looking beyond unit sales and pricing. The segment is shaped by regulatory pressure, platform electrification strategies, supplier differentiation in adaptive control and power efficiency, and cost structures that still challenge widespread adoption. The following analysis examines the market environment, the forces shaping demand, the competitive landscape, and the strategic moves that will define the next three-to-five-year horizon.
Vacuum Pumps Market
Market Landscape and Core Challenges
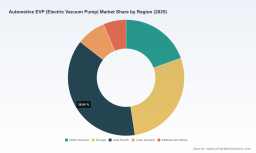
The EVP market has grown consistently across the 2020 to 2025 period, reflecting steady integration into passenger and commercial vehicle architectures. The growth curve is not uniform, however. It is modulated by regional vehicle mix, electrification adoption rates, and the pace at which legacy vacuum-generating systems are replaced by electric alternatives. Asia Pacific currently represents the largest revenue pool, followed by Europe and North America, with Latin America and the Middle East/Africa contributing smaller but expanding shares. This geographic distribution mirrors broader automotive production and sales patterns, while also highlighting where regulatory pressure and electrification investment are most concentrated.
Segmentation by type reveals a market still anchored by diaphragm-type pumps, which dominate due to their mature design, reliability, and compatibility with hybrid and internal combustion platforms. Swing piston and leaf-type designs occupy meaningful but smaller positioning, often differentiated by specific efficiency, packaging, or durability requirements. Application-wise, brake booster systems remain the primary demand center, as electric vacuum generation is essential for reliable braking assist when engine-driven vacuum is unavailable or insufficient. Emission control systems and engine management systems represent secondary but strategically important application areas, where EVPs support precise vacuum-dependent processes and help reduce parasitic mechanical losses.
Three core challenges define the market’s current inflection point:
- Cost barriers and material constraints. The upfront cost of electric vacuum pumps remains a restraint, driven by raw material costs, precision manufacturing requirements, and the need for integrated control electronics. While economies of scale and design optimization are gradually easing this pressure, cost sensitivity continues to influence procurement decisions, particularly in price-competitive segments and emerging markets.
- Regulatory-driven integration complexity. New emissions and fuel economy standards are pushing EVPs from optional auxiliaries into baseline design requirements. This shift forces suppliers and OEMs to reconcile performance, packaging, thermal management, and system integration at earlier design stages, raising the stakes for supplier readiness and development lead times.
- Platform fragmentation across powertrains. The market must simultaneously serve traditional ICE applications, hybrid architectures, and increasingly electrified platforms. Each powertrain path demands different vacuum profiles, control strategies, and reliability expectations. Suppliers that can deliver adaptable EVP families with consistent performance across these environments are better positioned than those optimized for a single use case.
These challenges are not simply headwinds; they are shaping the criteria by which buyers evaluate suppliers and by which companies allocate R&D resources. The market is moving toward solutions that combine reliability, efficiency, and intelligent on-demand operation, rather than standalone vacuum generation.
Key Demand Drivers
Technology Innovation and Adaptive Control
A central driver of EVP adoption is the shift toward adaptive vacuum control and intelligent operation. Pumps are no longer expected to run continuously; instead, they are increasingly designed to respond to real-time braking demand, engine state, and hybrid/electric mode transitions. This reduces parasitic power consumption, improves brake response, and supports fuel efficiency and emissions targets. Recent product launches illustrate this direction clearly. In May 2025, Bosch introduced a new generation of electric vacuum pumps for hybrid and electric vehicles aimed at enhancing braking performance. Continental unveiled a high-performance EVP for passenger ICE platforms in Europe, emphasizing adaptive vacuum control, power efficiency, and integration with regenerative braking. Rheinmetall’s Pierburg division launched an electric vacuum pump focused on reducing CO2 emissions and enhancing hybrid and brake system performance, highlighting rapid vacuum buildup and intelligent on-demand operation. Denso also introduced a diaphragm-type EVP in the Asia-Pacific region for hybrid and ICE engines, with adaptive control intended to improve braking and fuel efficiency.
These developments point to a broader technological trend: the EVP is becoming part of a controlled, responsive system rather than a fixed-output component. Suppliers that integrate adaptive control algorithms, optimize power draw, and coordinate with brake and powertrain controllers are creating differentiation that goes beyond mechanical design. This matters for OEMs because it allows vacuum management to align with broader vehicle efficiency strategies and electrified brake architectures.
Regulatory and Emissions Mandates
Regulatory pressure is one of the most decisive forces in the EVP market. The European Union’s Euro 7 standards, taking effect in 2026, set fleet average CO2 emissions limits of approximately 49.5 g/km for passenger cars, compelling designs that eliminate parasitic mechanical losses and ensure reliable braking with lower emissions. Similar dynamics are visible in China’s National VI emissions standard and California’s Advanced Clean Cars II regulation, which encourage improved fuel efficiency through auxiliary vacuum system implementation across vehicle portfolios. At a broader level, stringent emission and fuel economy regulations are mandating electric vacuum pump integration to maintain braking reliability and reduce emissions in hybrid and electric vehicles.
These regulations affect the market in two ways. First, they expand the addressable base by making EVP integration a compliance consideration for a wider range of vehicle programs. Second, they raise the technical bar, since compliance often depends on system-level performance rather than pump-level specifications alone. Tier-1 suppliers including Robert Bosch, Denso, and Valeo are scaling compliant EVP solutions in response, reflecting the way regulation is shaping supplier roadmaps and production capacity planning. The implication for decision-makers is that EVP demand is not purely cyclical; it is structurally supported by regulatory timelines that are difficult to defer.
Demand-Side Shifts in Vehicle Architectures and Safety Expectations
On the demand side, vehicle architectures are shifting in ways that increase reliance on electric vacuum generation. As engine-driven vacuum sources become less available or less reliable in hybrid and electric contexts, EVPs provide a controllable alternative for brake boosting, emission system operation, and engine management functions. At the same time, consumer and commercial expectations around braking performance, safety, and efficiency are rising. Brake booster systems remain the dominant application because vacuum assist continues to be central to reliable braking feel and response, especially during transitions between powertrain modes.
This demand shift is not limited to passenger cars. Commercial vehicles and xEV braking systems are also creating additional application space for EVPs, particularly where consistent vacuum delivery and system compatibility are required across OEM and aftermarket use. Suppliers that can deliver consistent vacuum performance across passenger and commercial platforms are building broader portfolios that reduce program risk for buyers. The commercial side of the market often places different weight on durability and cost, so balancing performance with value is a strategic priority.
Supply Chain and Cost Structure Dynamics
The supply side of the EVP market is being shaped by material costs, manufacturing complexity, and the need for tighter integration with electronic control systems. High initial costs remain a restraint, but the same factors are encouraging design consolidation, higher production volumes in key regions, and closer collaboration between pump manufacturers and system integrators. This creates a dual dynamic: cost pressure limits rapid adoption in price-sensitive programs, while scale and integration opportunities reward suppliers that can deliver complete, validated solutions rather than stand-alone pump units.
Regional supply chains are also relevant. South Korean suppliers such as Youngshin Precision and LPR Global illustrate the growing role of cost-effective EVP series for passenger vehicles and the strategic importance of suppliers serving EV, hybrid, and high-performance applications. LPR Global, for example, has positioned itself as a primary supplier for EV and hybrid vacuum pump needs, serving a substantial share of South Korean EV makers and providing components for Kia/Hyundai applications through Valeo. Meanwhile, Advik Hi-Tech’s collaboration with Entecnia S.L.U. shows how cross-border partnerships are being used to develop advanced EVP solutions for passenger cars, commercial vehicles, and xEV braking systems. These supply-side patterns indicate that the market is not solely concentrated in traditional European hubs; regional specialists are expanding capabilities and integrating into global OEM and tier-1 networks.
Automotive Vacuum Pump Market
Competitive Landscape and Leading Strategies
The EVP market remains highly concentrated, with a small group of suppliers accounting for the majority of revenue. This concentration reflects the technical barriers to entry, the importance of validation and system integration, and the long development cycles associated with automotive component qualification. At the same time, the competitive field is not static. Incumbents are expanding their EVP portfolios to address hybrid and electric platforms, while regional specialists are gaining traction through cost efficiency, targeted applications, and partnership-based development.
Bosch continues to occupy a leading position as a manufacturer of modular EVPs for automotive brake boosters, with recent expansion into adaptive control for hybrid and electric vehicles and integration with electronic brake systems. Its strategic advantage lies in scale, system-level integration capability, and the ability to align pump development with broader braking and powertrain strategies. Continental competes on high-performance EVP solutions for passenger ICE vehicles, differentiating through adaptive vacuum control, power efficiency enhancements, and regenerative braking integration. Rheinmetall’s Pierburg division emphasizes single- and dual-stage EVPs optimized for hybrid and brake systems, with a focus on low CO2 emissions, rapid vacuum buildup, and intelligent on-demand operation. Hella develops and supplies EVPs specifically for brake booster applications, prioritizing reliable pneumatic brake boost operation in modern vehicles. These European incumbents share a common strategic theme: they are moving beyond component supply toward system-relevant performance, control, and compliance.
In parallel, regional players are carving out differentiated roles. Youngshin Precision produces cost-effective EVP series for passenger vehicles, delivering consistent vacuum delivery for both OEM and aftermarket applications. LPR Global serves as a primary supplier for EV, hybrid, and high-performance vehicles, with a strong footprint among South Korean EV makers and a role in Kia/Hyundai applications through Valeo. Advik Hi-Tech is advancing EVP production in collaboration with Entecnia S.L.U., targeting passenger cars, commercial vehicles, and xEV braking systems. Valeo functions as a recipient and integrator of EVP components, including SMVP series parts for installation in Kia and Hyundai advanced automobiles. Denso supplies diaphragm-type EVPs for hybrid and ICE engines, emphasizing adaptive vacuum control and fuel efficiency improvements. This mix of large incumbents and specialized suppliers creates a landscape where technical leadership, cost positioning, and regional supply relationships all matter.
Recent developments reinforce the pace of competitive activity. In early 2025, Advik Hi-Tech showcased a new range of automotive components at the Bharat Mobility Global Expo in New Delhi, including advanced EVPs developed with Entecnia S.L.U. for passenger and commercial braking systems. In April 2025, Pierburg launched an electric vacuum pump in Germany focused on CO2 reduction and hybrid/brake system enhancement. May 2025 saw a cluster of launches: Bosch introduced its next-generation EVP for hybrid and electric vehicles; Denso launched a diaphragm-type EVP in Asia-Pacific for hybrid and ICE engines; and Continental unveiled a high-performance EVP for passenger ICE vehicles in Europe with adaptive vacuum control and regenerative braking integration. These moves indicate that product refresh cycles are accelerating, particularly around efficiency, control, and compliance.
Looking ahead, the competitive landscape is likely to evolve along three lines. First, consolidation may continue among suppliers that can offer integrated, compliant EVP systems with validated brake and powertrain compatibility. Second, differentiation will increasingly depend on control software, efficiency, and packaging flexibility rather than mechanical design alone. Third, new entrants and regional specialists will continue to challenge incumbents in specific applications, especially where cost, local supply relationships, or commercial-vehicle specialization provide a credible edge. The market is therefore not a simple two-tier hierarchy; it is a layered ecosystem in which both global scale and application-specific expertise create value.
Future Trends and Commercial Opportunities
Trend 1: Electric Vacuum Pumps as a Compliance and Efficiency Standard
As emissions and fuel economy mandates tighten, EVPs are likely to become a more standard element of vehicle design rather than a retrofit or niche solution. This trend is strongest in regions with aggressive regulatory timelines, but it is also spreading as automakers harmonize platforms across markets. The commercial opportunity lies in suppliers and OEMs that treat EVP integration as a system-level requirement from the outset, aligning pump selection with brake architecture, powertrain mode transitions, and thermal and packaging constraints. Early integration reduces redesign risk and supports compliance without compromising performance.
PW Consulting Automotive & Machinery Research Center
Trend 2: Adaptive, On-Demand Control as the Core Value Driver
The next phase of EVP competition will likely center on intelligent control: pumps that modulate output based on real-time demand, support regenerative braking coordination, and minimize power loss. This creates opportunities for suppliers that can combine hardware and control expertise, as well as for OEMs that can leverage adaptive vacuum management to improve efficiency and braking consistency across hybrid and electric modes. The value proposition is not simply “more vacuum,” but “vacuum delivered more precisely and with less energy cost.” As brake systems become more electrified and more dependent on coordinated control, this precision will increasingly differentiate suppliers.
Trend 3: Regional Specialization and Supply Chain Diversification
The market’s geographic distribution is likely to remain uneven, but regional specialization will become more important. Asia Pacific’s scale, Europe’s regulatory intensity, and North America’s mix of passenger and commercial requirements create distinct demand profiles. At the same time, suppliers that can serve multiple regions with adaptable product families and localized support will be better positioned to manage program risk and cost. Commercial opportunities include partnerships that combine global scale with regional responsiveness, and supplier strategies that balance cost efficiency with compliance readiness. Buyers benefit when they can access both mature, validated solutions and cost-competitive alternatives for less demanding applications.
Potential risks and uncertainties remain. Cost pressures may persist if raw material and manufacturing expenses do not decline as quickly as volume scales. Regulatory timelines can shift, altering the pace at which EVP integration becomes mandatory across additional vehicle categories. Platform fragmentation may also complicate standardization, especially when OEMs pursue diverse hybrid and electric strategies simultaneously. Finally, technological change in brake systems and electrification architectures could reshape the role of vacuum assist over time, making flexibility and monitoring essential for long-term planning.
Strategic Recommendations for Decision-Makers
For manufacturers and suppliers, the priority is to align EVP development with the regulatory and platform shifts that are shaping demand. This means investing in adaptive control, efficiency, and on-demand operation, while building product families that can serve ICE, hybrid, and electrified applications without excessive rework. Equally important is the ability to demonstrate system-level integration value, not just pump specifications. Suppliers that can show how their EVP solutions support braking performance, emissions compliance, and power efficiency in a coordinated architecture are more likely to win program contention in a concentrated market.
For investors, the EVP segment offers growth supported by regulatory tailwinds and electrification-linked demand, but selection matters. The most resilient opportunities are likely to be found in suppliers with credible hybrid/EV integration strategies, demonstrated compliance readiness, and the ability to compete across both premium and cost-sensitive applications. Monitoring product launch cadence, partnership activity, and regional supply relationships can provide early signals about which players are expanding their relevance and which are constrained to narrow niches. Given the market’s concentration and technical barriers, due diligence should focus on validation capability, control software development, and exposure to regulatory-driven demand across key regions.
For procurement and OEM strategy teams, the key is to avoid treating EVPs as interchangeable commodities. Specifications alone do not capture the value of adaptive control, integration compatibility, and compliance support. Procurement strategies should evaluate total system impact, including brake performance, energy consumption, packaging constraints, and lifecycle cost, while maintaining flexibility to source from both established incumbents and regional specialists where appropriate. In a market where cost remains a restraint but compliance and performance are non-negotiable, the best outcomes typically come from balancing proven system reliability with competitive cost structures.
The EVP market is moving from steady expansion to a more strategically nuanced phase, where regulation, electrification, and intelligent control redefine what suppliers must deliver and what buyers should prioritize. For organizations seeking more detailed segmentation data, company-level tracking, and customized assessments tailored to specific program portfolios or investment theses, the full research report provides a deeper dive into the numbers and the strategic implications behind them.
For detailed analysis of this topic, please visit the official page: Automotive EVP (Electric Vacuum Pump) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com