

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Pile Driver Market 2026: The 5.25% CAGR Masks Hydraulic’s 68.88M USD Dominance

Strategic Trends and Commercial Opportunities in the Global Pile Driver Market
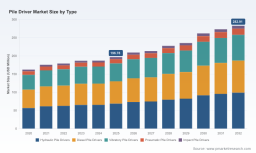
The global pile driver market is entering a decisive growth phase, driven by sustained infrastructure investment, evolving environmental regulations, and accelerating technological modernization across foundation construction. Valued at 196.78 million USD in 2025 and projected to reach 282.91 million USD by 2032, the market is expanding at a compound annual growth rate of 5.25 percent over the forecast window. The expansion from 162.34 million USD in 2020 reflects a steady climb punctuated by post-pandemic recovery cycles, followed by a more structured demand environment shaped by large-scale civil works, renewable energy installations, and offshore engineering programs. While the headline trajectory suggests consistent growth, the underlying market dynamics reveal a sector navigating technological transition, regulatory tightening, and shifting application priorities. Understanding these forces is essential for manufacturers, investors, and procurement leaders seeking to align capacity, investment, and sourcing strategies with where value is actually being created.
The current market environment is characterized by moderate growth rather than explosive expansion, with annual revenue progression indicating a maturing demand base that is increasingly selective about equipment specifications, service expectations, and total cost of ownership. Demand is no longer driven solely by volume of construction activity; it is increasingly influenced by project complexity, environmental compliance requirements, and the need for precision installation in congested urban and sensitive offshore environments. In this context, the pile driver market functions less as a commodity equipment segment and more as a technology- and service-intensive foundation solution space. Companies that recognize this shift are repositioning their product lines, service offerings, and regional footprints accordingly, while organizations that treat pile driving equipment as a standalone mechanical category risk misalignment with end-user priorities.
Three structural challenges define the current inflection point for the industry. First, environmental and noise-vibration regulation is becoming a constraining design parameter rather than a peripheral compliance issue. Offshore and urban foundation projects face stricter permitting conditions, which push equipment suppliers toward integrated mitigation systems and quieter installation methods. Second, skilled labor availability and wage pressure are changing the economic equation for construction and foundation contractors. As prevailing wage expectations rise in multiple regions and project schedules tighten, equipment that reduces operator dependency, improves repeatability, and enables remote or semi-automated control gains strategic relevance. Third, the market is experiencing a widening gap between standardized general-purpose machines and highly specialized solutions for solar, offshore wind, and complex infrastructure work. This divergence forces manufacturers to choose between broader product coverage and deeper application focus, while buyers must evaluate whether their project pipeline justifies specialization or favors flexible equipment fleets.
Key Drivers Reshaping Market Trajectory
Technology Innovation and Integrated Precision Systems
The most consequential driver in the pile driver market is the shift toward precision, control, and integration. Modern hydraulic and vibratory systems are increasingly designed with advanced automatic controls, auto-plumb functionality, remote operation, and positioning readiness for laser or GPS-guided installation. These features address a practical need: foundation work in renewable energy farms, transportation corridors, and dense urban sites requires repeatable accuracy and reduced rework. The trend is visible in recent product updates that emphasize wireless remote control and automated alignment features for utility-scale solar applications, reflecting how equipment design is being shaped by the installation rhythm of large-area renewable projects rather than traditional isolated construction jobs. Alongside this, new hydraulic pile driver platforms incorporating kinematic systems for Kelly drilling and sheet pile applications illustrate how manufacturers are expanding the functional scope of a single machine to cover multiple foundation tasks, improving equipment utilization for contractors who prefer multi-role assets.
Innovation is also advancing in the direction of noise and vibration mitigation, particularly where onshore urban work and offshore installation intersect with environmental permitting. The integration of mitigation systems into pile driving equipment is becoming a competitive differentiator, not merely an add-on service. As project owners and regulators demand cleaner installation methods, manufacturers that can offer equipment-ready mitigation capabilities or compatible hammer configurations are better positioned to win bids and maintain access to restricted sites. This dynamic is pushing the market toward more holistic equipment engineering, where hammer performance, control electronics, and environmental compliance are evaluated together rather than as separate purchasing decisions.
Policy, Regulation, and Permitting Pressure
Regulatory conditions are increasingly shaping equipment preferences and project economics. Occupational safety requirements already define operational boundaries for pile driving activity, including provisions that suspend cutting operations under specific proximity conditions unless protective distances are maintained. These rules influence site layout, equipment positioning, and crew procedures, making equipment that supports safer separation and controlled operations more attractive. On the environmental side, noise and vibration mitigation requirements for offshore and urban projects are becoming standard elements of project permitting, often tied to ISO-aligned expectations and local environmental approvals. This regulatory layer raises the bar for equipment selection because contractors must demonstrate that their installation method can satisfy both the engineering objective and the compliance constraint.
Beyond safety and environmental rules, broader infrastructure policy is indirectly accelerating demand for efficient hydraulic pile drivers. Large-scale investments in renewable energy and transportation networks are expanding the pipeline of foundation-intensive projects, and those projects frequently require installation methods that can meet tightening environmental expectations without sacrificing throughput. Policy-driven spending does not automatically translate into equipment sales; rather, it filters through procurement standards, site constraints, and the need for machines that can perform reliably within a regulated environment. The market response has been to favor equipment that can operate efficiently while reducing the compliance burden on contractors and developers.
Demand-Side Shifts and Application Diversification
Demand patterns are shifting as end-use sectors diversify beyond traditional building construction. Infrastructure programs remain a primary demand anchor, but renewable energy installations, offshore engineering, and specialized utility work are increasingly influencing purchasing decisions. Solar utility-scale projects, for example, create a distinct installation profile that rewards repeatability, remote control, and fast setup across large arrays. Offshore wind and coastal infrastructure projects, meanwhile, emphasize robust hydraulic hammers, noise mitigation capability, and reliability under demanding marine conditions. These application differences matter because they shape equipment specifications, service expectations, and even regional demand intensity.
On the buyer side, contractors and developers are increasingly evaluating pile driving equipment through a total project lens. Speed of installation, reduced rework, compliance readiness, and operator efficiency are becoming as important as purchase price. This is especially true where labor premiums and schedule pressure increase the cost of inefficiency. As a result, equipment that helps control labor intensity and installation variability is gaining ground, even if its upfront cost is higher. The broader implication is that demand is moving toward solutions that reduce operational risk and improve predictability, not just machines that deliver impact or vibration in isolation.
Supply Chain, Cost Structure, and Regional Realignment
Cost structures in the pile driver market are being shaped by input price volatility, manufacturing scale, and regional sourcing strategies. Equipment makers must balance durable construction, hydraulic performance, control-system complexity, and serviceability against the pressure to remain competitively priced in a market where buyers are increasingly cost-conscious but unwilling to sacrifice compliance or reliability. In parallel, regional demand patterns are reinforcing different competitive approaches. Markets with strong infrastructure pipelines and mature contracting ecosystems reward established product lines, service networks, and proven reliability. Regions with rapidly expanding renewable and civil works programs create room for technology-forward equipment and targeted application offerings, but also demand close attention to local permitting, labor conditions, and contractor preferences.
Labor cost dynamics further influence equipment economics. In certain construction labor markets, prevailing wage structures and premium pay for non-standard hours raise the financial impact of inefficient installation. That creates a stronger incentive for equipment that reduces cycle time, supports fewer-operator workflows, and lowers the likelihood of rework or compliance interruptions. When labor cost pressure rises, the business case for automation-enabled control, remote operation, and precise positioning strengthens, even if the purchase decision remains constrained by capital budgeting cycles.
Marine Engineering Hydraulic Piling Hammer Market
Competitive Landscape and Leading Strategies
The competitive field in the pile driver market is fragmented but increasingly stratified by application expertise, geographic reach, and technology integration. The market remains moderately concentrated, with the largest players commanding a meaningful share of revenue while still leaving substantial room for regional specialists and application-focused manufacturers. This structure creates a competitive environment where scale, product breadth, and service capability matter, but so does the ability to align equipment with specific project types and compliance conditions.
North American manufacturers have carved out a strong position in foundation construction equipment, with some firms serving as the largest regional producers of pile driving and drilling equipment and offering a broad mix of vibratory drivers, impact hammers, power units, and drilling rigs. Their advantage often lies in product range, local service familiarity, and close alignment with domestic foundation contractors. Other leading players focus on foundation equipment at a global scale, producing some of the largest pile drivers in the market and covering vibratory drivers, diesel hammers, hydraulic impact hammers, and power units. Their strategic positioning is rooted in scale, engineering breadth, and the ability to serve demanding heavy civil and large-diameter piling applications.
In the utility-scale and solar segment, manufacturers have gained attention by designing pile drivers around precise installation, auto-plumb, remote control, and laser or GPS-ready positioning. This application-led approach differentiates equipment not by raw power alone, but by how effectively it supports repeatable deployment across large project footprints. European manufacturers bring long-standing expertise in diesel hammers and impact solutions for construction and infrastructure, often leveraging decades of product heritage and specialized hammer engineering. Others in the European space specialize in hydraulic pile hammers, noise mitigation systems, and offshore pile driving equipment for wind, coastal, and oil and gas projects, making them particularly relevant where environmental constraints and marine operating conditions dominate.
PW Consulting Automotive & Machinery Research Center
Broader construction and civil machinery companies also participate in the market through hydraulic hammers and pile driving equipment designed for heavy civil and infrastructure work. Their relevance often comes from integrating pile driving capability into wider equipment portfolios and service networks, which can be attractive to contractors seeking consistency across machine types. Specialty manufacturers add further differentiation with side-grip vibratory pile drivers, hydraulic piling hammers, and advanced automatic controls, while some Chinese manufacturers emphasize technology integration for foundation engineering in renewable energy and infrastructure, and others supply diesel and hydraulic impact hammers for state-owned enterprises and offshore or bridge projects.
Recent industry developments illustrate how this competitive landscape is evolving. Product launches have introduced new hydraulic pile driver platforms with expanded kinematic capability for Kelly drilling and sheet pile work, signaling a push toward multi-function equipment. Prototype announcements for vertical and inclined pole driving point to continued experimentation with installation geometry and specialized use cases. Expansion of U.S. sales presence by press-in piling equipment providers reflects growing interest in alternative installation methods and direct mechanical displacement solutions. At the same time, product catalog updates emphasizing wireless remote control and auto-plumb features for solar utility-scale projects show how established models are being refined to match application-specific operating needs. These moves suggest a market where competition is increasingly about precision, versatility, and compliance-ready design rather than equipment category alone.
Market evolution is likely to follow a dual path. Consolidation will remain attractive for manufacturers seeking broader geographic coverage, stronger service networks, and more complete product lines, especially where contractors prefer fewer supplier relationships and more predictable support. At the same time, differentiation will continue to fragment the market by application, with specialized solutions for offshore, solar, urban noise-sensitive, and complex infrastructure projects creating niches that reward focused engineering and targeted sales strategies. New entrants and expanding regional players can gain traction by addressing underserved application requirements, offering alternative installation methods, or providing equipment configurations that align with local labor, regulatory, and project conditions. The strategic implication is that neither pure scale nor pure specialization guarantees advantage; success depends on aligning product strategy with the demand profile of the projects that actually dominate a company’s target pipeline.
Future Trends and Commercial Opportunities (2026–2032)
Over the next several years, the pile driver market is likely to be defined by three reinforcing trends. The first is the continued integration of automation-ready controls and positioning technologies into mainstream pile driving equipment. As installation accuracy, remote operation, and reduced operator dependence become more important to contractors managing labor pressure and schedule risk, machines that offer semi-automated alignment, remote control, and guidance-system compatibility will become increasingly standard rather than premium. The commercial opportunity here lies in equipment and service packages that improve installation repeatability, reduce rework, and support faster crew training across multiple project types.
The second trend is the deepening alignment between equipment design and environmental compliance. Noise and vibration mitigation will move from project-specific workaround to baseline expectation in offshore, urban, and sensitive onshore environments. Manufacturers and service providers that can deliver mitigation-compatible hammers, integrated mitigation systems, and installation methods suited to permitting requirements will be better positioned to access restricted projects and support contractor bidding credibility. The opportunity is not simply in selling more equipment, but in helping end users navigate the regulatory dimension of foundation installation with fewer interruptions and clearer compliance pathways.
The third trend is the widening relevance of application-specific equipment strategies. Renewable energy build-out, transportation infrastructure, offshore engineering, and specialized utility work will continue to pull demand in different directions, making one-size-fits-all product portfolios less effective over time. Contractors and developers will increasingly favor equipment that matches the installation rhythm of their most important project types, whether that means fast setup and remote control for large solar farms, robust hydraulic performance for heavy civil works, or marine-ready systems with mitigation capability for offshore tasks. The commercial opportunity lies in mapping equipment offerings to the highest-value application clusters, then building configuration, service, and support around those clusters rather than spreading effort evenly across all possible use cases.
These trends carry risk and uncertainty. Regulatory expectations can change faster than equipment development cycles, particularly where local permitting, environmental review, and safety enforcement differ by jurisdiction. Labor market conditions may shift the balance between capital investment in advanced equipment and reliance on skilled crews, making demand for automation-enabled features more or less urgent depending on region and project timing. Competitive intensity may also increase as manufacturers broaden multi-function platforms and alternative installation methods gain traction, potentially compressing margins in segments where differentiation is difficult. Finally, project pipelines tied to infrastructure and renewable energy spending are subject to procurement delays, funding timing, and policy adjustments, meaning demand growth may arrive in waves rather than as a smooth upward curve.
Actionable Guidance for Decision-Makers
For Manufacturers and Equipment Suppliers
Product strategy should be anchored to application realities rather than broad category coverage. Prioritize control integration, remote operation, and positioning compatibility as core selling points, especially where labor efficiency and installation accuracy directly influence project economics. Develop mitigation-compatible configurations and clearly communicate how equipment supports compliance in noise-sensitive and offshore settings. Evaluate whether the strongest returns will come from expanding multi-function platforms or from deeper specialization in a few high-value segments such as solar utility-scale work, heavy civil infrastructure, or offshore foundation installation. Service, training, and spare-parts availability should be treated as part of the product proposition because contractor decisions increasingly account for total operating risk, not just purchase price.
For Investors and Capital Allocators
Focus on businesses that demonstrate a credible link between equipment capability and shifting demand drivers: precision installation, environmental compliance, labor efficiency, and application-focused differentiation. Companies that can serve high-growth project types while maintaining strong service and support networks are better positioned than those competing primarily on baseline mechanical function. Pay attention to regional demand mix, because infrastructure-intensive markets and renewable energy build-out zones may offer faster growth but also different competitive dynamics and regulatory constraints. Assess whether a company’s product roadmap reflects the likely trajectory of automation, mitigation, and application specialization, since those factors will shape both revenue quality and competitive defensibility through the end of the decade.
For Procurement Leaders and Contractors
Evaluate pile driving equipment against the actual operating conditions of the projects in your pipeline. If labor premiums, schedule pressure, and compliance requirements are significant, prioritize machines that reduce operator dependency, improve alignment accuracy, and support safer site workflows. For larger renewable or infrastructure programs, examine whether multi-role equipment or application-focused machines better match your installation profile and crew structure. Include noise and vibration mitigation compatibility in the procurement decision where permitting conditions make it relevant, and ensure that supplier support, training, and replacement-part availability are assessed alongside technical specifications. The most cost-effective equipment is not always the least expensive upfront; it is the solution that minimizes rework, site interruptions, and labor inefficiency across the projects you actually intend to execute.
Hydraulic Hammer Market
The strategic picture is clear: the pile driver market is expanding, but the most valuable opportunities are concentrated in precision, compliance readiness, application alignment, and operational efficiency. Organizations that treat these as central purchasing and product priorities will navigate the next phase of market growth more effectively than those reacting only to headline demand. For decision-makers who need more granular segmentation, regional nuance, and tailored scenario planning, detailed research coverage can provide the deeper data and structured recommendations required to move from directional insight to executable strategy.
For detailed analysis of this topic, please visit the official page: Pile Driver Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com