

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Mask Inspection Equipment Market: What 5.9% CAGR Reveals About Asia Pacific Dominance

Strategic Trends and Commercial Opportunities in the Mask Inspection Equipment Market
The mask inspection equipment market has entered a phase of steady but structurally significant expansion, with global revenue projected to grow from approximately $3.25 billion in 2025 to nearly $4.79 billion by 2032, reflecting a compound annual growth rate of 5.9 percent over the forecast period. This trajectory is not merely a continuation of historical growth patterns but rather the result of converging technological, regulatory, and manufacturing shifts that are reshaping how photomasks are qualified, inspected, and deployed across advanced semiconductor workflows. While the headline numbers suggest predictable expansion, the underlying dynamics reveal a market where competitive positioning, technology selection, and geographic exposure are being redefined at an accelerated pace.
The baseline growth is anchored in the relentless scaling of semiconductor production and the corresponding need for higher-fidelity mask qualification. As process nodes shrink and design complexity increases, the margin for error in mask defect detection narrows dramatically. Inspection equipment that once served as a quality gate is now embedded deeper into the manufacturing and merchant mask supply chain, influencing throughput, yield learning cycles, and time-to-tape-out. The market has also benefited from broader capital expenditure cycles that prioritize equipment reliability and defect management over incremental cost optimization. Yet this growth is uneven across technology platforms and applications, and participants that treat inspection as a commoditized ancillary step are increasingly exposed to margin compression and displacement risk.
Three interconnected challenges define the current inflection point. First, the transition toward extreme ultraviolet lithography and advanced multi-patterning workflows has raised the bar for defect sensitivity, pattern placement accuracy, and inspection throughput. Equipment must now resolve sub-wavelength anomalies while maintaining cycle times that do not disrupt high-volume production schedules. Second, the regulatory environment has become a material factor in market access and product deployment. Stored program controlled equipment used for mask, reticle, and pellicle inspection has been designated as a restricted item under the Export Control Reform Act, and certain mask inspection equipment will fall under the Direct Product Rule beginning January 2026. These measures affect cross-border technology transfer, service models, and the strategic calculus of companies operating across multiple jurisdictions. Third, the competitive structure remains relatively fragmented at the top, with the top three players accounting for roughly 24.6 percent of revenue and the top five reaching about 26.2 percent. This moderate concentration suggests room for differentiation, but also indicates that scale advantages, technology leadership, and ecosystem integration will determine which firms can defend pricing power and win premium deployments.
Optical and E-Beam Inspection Redefined by Node Scaling and EUV Readiness
Technological innovation remains the most powerful demand catalyst, but its impact is now concentrated in specific inspection modalities that align with advanced node requirements. Optical mask inspection continues to hold the largest revenue share, reflecting its broad applicability across die-to-die and die-to-database workflows, mature node qualification, and high-throughput review processes. However, the strategic value of optical platforms is shifting from general-purpose defect detection toward systems that combine high sensitivity with faster pattern recognition, better database matching, and tighter integration with mask shop data pipelines. E-beam inspection, while smaller in total revenue, is gaining strategic relevance in EUV mask quality control and reticle analysis, where the ability to detect subtle defects and characterize pattern placement at advanced feature sizes is increasingly non-negotiable. The presence of both optical and e-beam platforms in the market underscores a broader truth: the winning architecture is no longer defined by a single technology but by the ability to match inspection modality to node, volume, and defect criticality.
Recent product activity illustrates how vendors are translating technology roadmaps into commercial positioning. In December 2025, Lasertec Corporation introduced the MAGICS Series M9750 and M9751 mask blank inspection and review systems designed for next-generation leading-edge semiconductors and advanced EUV mask blanks. This launch signals a deliberate push into the mask blank and EUV mask quality control segment, where sensitivity, repeatability, and compatibility with actinic inspection requirements are becoming differentiators. Around the same period, HTL Co., Ltd. reported the first acceptance of its DIONE-CIS photomask inspection system in the United States, with the system introduced into mass production at a major merchant mask shop in July 2025. This milestone is notable not only for expanding the geographic footprint of a Japan-based equipment supplier but also for demonstrating that merchant mask operations are increasingly open to newer inspection platforms when they can demonstrate reliability, throughput, and integration into production workflows. Together, these developments reflect a market where innovation is being validated through real production adoption rather than specification benchmarks alone.
Semiconductor Inspection Equipment Market
Regulation as a Market Reshaping Force, Not Just a Compliance Task
Policy and export control developments are no longer peripheral considerations; they are becoming structural inputs into commercial strategy. The Federal Register listing of stored program controlled equipment for mask, reticle, and pellicle inspection as a restricted item under the Export Control Reform Act introduces new considerations for cross-border sales, localization of support, and technology migration paths. More immediately, the Export Administration Regulations placing certain mask inspection equipment under the Direct Product Rule effective January 2026 create a compliance threshold that affects product classification, customer onboarding, and the ability to serve specific end markets without localized solutions or adjusted service models.
For equipment providers, the regulatory shift amplifies the importance of supply chain transparency, documentation readiness, and regional deployment strategies. Companies that rely heavily on cross-border technology flows or centralized service architectures may need to revisit how they structure manufacturing, software delivery, and field support to remain accessible in restricted or controlled contexts. For buyers, especially merchant mask shops and semiconductor manufacturers operating across multiple regions, the changing rules raise questions about equipment sourcing flexibility, long-term service continuity, and the risk of deployment delays if classification or licensing requirements are not addressed early in procurement cycles. The practical implication is that regulatory alignment is increasingly part of the value proposition, not a separate compliance checkbox. Vendors that can offer predictable deployment pathways and buyers that incorporate export control considerations into technology roadmaps will be better positioned to avoid disruption.
Demand Shifts in Semiconductor and Photomask Manufacturing
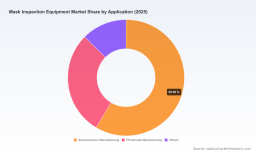
On the demand side, mask inspection growth is being shaped by how semiconductor manufacturers and photomask producers allocate capital and prioritize defect management. In semiconductor manufacturing, inspection equipment supports yield learning, advanced node qualification, and the operational discipline required to sustain high-volume production with tighter process controls. In photomask manufacturing, demand is driven by the need to supply leading-edge masks to multiple downstream customers, where defect rates, turnaround times, and consistency across mask lots directly influence merchant competitiveness. The application split in the market reflects this dual engine: semiconductor manufacturing represents the largest demand pool, while photomask manufacturing remains a critical downstream segment where inspection capabilities influence both quality and speed of mask supply.
Behavioral changes on the demand side are also evident in how buyers evaluate inspection tools. Decision-makers are increasingly focused on total workflow impact rather than isolated inspection performance. This includes integration with existing review and disposition processes, the ability to reduce false positives, alignment with mask shop throughput targets, and the flexibility to handle mixed technology nodes as product portfolios evolve. At the same time, the broader production environment is encouraging a more risk-aware posture. As manufacturers manage complexity across advanced packaging, multi-patterning, and EUV-related workflows, inspection is being treated as a lever for reducing downstream rework and improving predictability in mask qualification. This shift raises the stakes for equipment suppliers to demonstrate production-grade reliability and clear return on operational investment, rather than relying solely on technical specifications.
Cost Structures, Supply Chains, and the Commercial Logic of Differentiation
Cost and supply chain dynamics are reinforcing the move toward differentiated inspection solutions. Inspection equipment is not only a capital purchase; it is part of a broader operating cost structure that includes maintenance, software updates, service access, and production downtime risk. As buyers confront the need to maintain uptime while meeting higher inspection standards, the relative cost of lower-quality inspection or slower disposition workflows becomes more visible. This environment favors vendors that can reduce total cost of ownership through more efficient inspection cycles, stronger system reliability, and services that minimize operational friction. It also favors equipment strategies that align with the buyer's production mix, since one-size-fits-all platforms often struggle to match the nuances of advanced EUV blank review, high-volume optical inspection, or specialized reticle analysis.
Supply chain resilience is increasingly part of the purchasing calculus. Buyers are attentive not only to product capability but also to the predictability of delivery, the stability of software and service support, and the vendor's ability to operate consistently across regions with differing regulatory conditions. This is particularly relevant as export controls and restricted-item classifications introduce new layers of complexity into equipment deployment. In practice, the market is rewarding combinations of technical performance and commercial reliability. Equipment that can be deployed with fewer integration surprises, supported with clear service pathways, and aligned with local compliance realities is gaining an advantage that is difficult for competitors to replicate purely through specification improvements.
Competitive Positioning and the Evolution of Market Structure
The competitive field in mask inspection equipment is anchored by a mix of established semiconductor metrology leaders, specialized mask inspection providers, and regional players expanding their footprint through targeted product acceptance and production deployments. The landscape is characterized less by sudden disruption than by incremental but meaningful differentiation across technology portfolios, application focus, and geographic execution.
Leading Players and Their Strategic Anchors
KLA Corporation remains a central figure in semiconductor metrology and inspection, anchored by a comprehensive portfolio that spans reticle defect inspection systems for mask shops and EUV reticle quality control. Its positioning reflects breadth and integration, with an emphasis on serving mask shops and semiconductor manufacturers that require end-to-end inspection coverage across multiple technology nodes. Applied Materials continues to leverage its mask inspection systems, including optical and e-beam technologies, to support advanced node mask qualification and defect detection. Its strategic advantage lies in the ability to connect mask inspection with broader process and qualification ecosystems, which is increasingly valuable as mask quality becomes more tightly linked to downstream patterning outcomes.
Lasertec Corporation has carved a specialized position in actinic EUV mask inspection and high-sensitivity DUV mask blank and review systems. Its recent launch of the MAGICS Series M9750 and M9751 systems indicates a focus on next-generation mask blank inspection and EUV readiness, areas where sensitivity and process compatibility matter deeply. Camtek Ltd. contributes automated optical inspection capabilities for photomask defect inspection, including die-to-die and die-to-database applications, reinforcing a flexible optical inspection stance that aligns with mask shop review and qualification requirements. Hitachi High-Tech Corporation supports e-beam inspection and CD-SEM solutions targeted at EUV mask defect detection and reticle analysis, adding depth in electron-beam-based characterization where defect sensitivity and pattern analysis are critical. Onto Innovation delivers optical and e-beam inspection tools that support mask and reticle defect and pattern placement analysis, broadening the field of vendors that combine multiple inspection modalities. HTL Co., Ltd. rounds out the competitive set with automatic optical inspection systems for semiconductor photomask defect inspection, and its recent acceptance of the DIONE-CIS system in a U.S. merchant mask shop highlights the growing role of focused AOI providers in production environments.
Differentiation, Integration, and the Shape of Future Competition
The strategic patterns emerging across these companies point to several differentiation pathways. One is technology specialization, where vendors concentrate on particular inspection modalities or workflow segments, such as actinic EUV inspection, mask blank review, or e-beam reticle analysis. A second is integration and portfolio breadth, where the value lies in offering coverage across optical and e-beam platforms and aligning inspection with broader metrology or qualification workflows. A third is execution in production acceptance, where commercial momentum is built through successful deployment in merchant mask shops and semiconductor manufacturing environments, as illustrated by recent milestones in the United States and in advanced mask blank systems.
PW Consulting Automotive & Machinery Research Center
The market structure is likely to evolve through a combination of consolidation pressure and continued differentiation. Moderate concentration at the top suggests that scale alone is not yet decisive, but it also means that competitive advantages must be sustained through technology leadership, reliable production deployments, and strong service and compliance execution. New entrants and regional specialists can still gain traction by solving specific inspection problems well, especially where merchant mask shops and advanced node manufacturers seek alternatives or complementary capabilities. At the same time, the regulatory environment and the increasing complexity of advanced mask workflows may raise the bar for cross-border expansion and long-term support, making it more difficult to compete on price alone without a credible technology and service foundation.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
The next phase of market development is likely to be defined by tighter alignment between inspection technology, regulatory realities, and production economics. Three trends are particularly important for strategic planning.
Trend 1: Inspection Platforms Will Be Selected by Workflow Fit, Not by Technology Category Alone
As advanced nodes and EUV-related mask workflows become more central, buyers will increasingly choose inspection systems based on how well they fit a specific mask shop workflow or semiconductor qualification process. Optical and e-beam platforms will continue to coexist, but the winning deployments will be those that match defect sensitivity, throughput, database matching, and review integration to the actual production mix. This trend creates opportunities for vendors that can clearly map their systems to node-specific requirements and for buyers that evaluate inspection as part of a broader yield and throughput strategy rather than as a standalone purchase.
Trend 2: Export Controls and Restricted-Item Classification Will Influence Sourcing and Deployment Architecture
The regulatory trajectory points toward more deliberate structuring of equipment sales, service, and software delivery across regions. With stored program controlled mask inspection equipment designated as a restricted item and certain equipment placed under the Direct Product Rule beginning in early 2026, market participants will need to account for classification, documentation, and regional deployment feasibility earlier in the buying process. This trend is likely to benefit vendors with strong compliance readiness and clear regional execution models, while raising the cost of complexity for buyers that depend on highly cross-border, centralized procurement or service structures. Commercial opportunities will emerge for solutions that reduce deployment friction and make long-term support predictable across jurisdictions.
SMT Inspection Equipment Market
Trend 3: Merchant Mask Operations and Advanced Node Qualification Will Drive Differentiated Demand Growth
Demand growth will not be uniform. Merchant mask operations seeking to support multiple downstream customers with consistent quality and faster turnaround are likely to push for inspection systems that can handle high-mix, production-grade workloads. At the same time, advanced node qualification will continue to favor systems that provide superior defect sensitivity and pattern analysis for EUV-related mask quality control and reticle review. This divergence opens space for specialized growth in mask blank inspection, EUV mask review, and automated optical inspection platforms that have proven themselves in real production settings. The commercial opportunity lies in aligning product roadmaps and service models with these distinct demand profiles rather than treating mask inspection as a monolith.
Potential risks remain. The regulatory environment could tighten further or create unexpected deployment constraints for certain product configurations or regions. Technology transitions in lithography and mask workflows may shift inspection requirements faster than equipment roadmaps can adapt, particularly if defect sensitivity thresholds or throughput expectations escalate. In addition, competitive pressure from new product acceptances and expanding regional capabilities could compress margins for vendors that rely on legacy platforms without clear workflow differentiation. Market participants should therefore treat flexibility, compliance readiness, and production validation as strategic assets, not optional enhancements.
Strategic Implications for Decision-Makers
For manufacturers and mask shop operators, the priority is to align inspection capability with production objectives and regulatory realities. Investments should be evaluated against workflow fit, defect sensitivity needs, throughput impact, and the ability to sustain long-term service and software support across relevant regions. Preference should be given to platforms that have demonstrated production acceptance and that can reduce false positives, accelerate disposition, and integrate cleanly with existing review processes. Procurement timing also matters: as export control rules take effect and equipment classification becomes more consequential, early engagement with vendors on deployment structure and compliance readiness can reduce the risk of delays or sourcing constraints.
For investors, the market offers growth supported by 5.9 percent CAGR through 2032, but the most valuable exposure will come from understanding where differentiation is real and defensible. Attention should be paid to companies that are expanding into advanced mask blank inspection, EUV-related reticle control, or high-sensitivity review workflows, as well as to those that have secured meaningful production acceptance outside their home regions. Equally important is to assess how each company is positioned for regulatory complexity, since restricted-item classification and the Direct Product Rule may reshape competitiveness across geographies. The market's moderate concentration suggests that leadership is still contestable, but only for firms that can combine technology-edge, execution credibility, and commercial resilience.
For procurement teams and strategic buyers, the practical task is to treat mask inspection equipment as a long-term operational commitment rather than a specification-driven transaction. Evaluation frameworks should incorporate total cost of ownership, service continuity, software and support stability, and alignment with export control expectations. Buyers should also consider supplier diversification where appropriate, especially when multiple inspection modalities or regional deployment scenarios are involved. The more clearly a procurement strategy accounts for both technical fit and regulatory accessibility, the lower the risk of disruption as the market matures and control requirements become more embedded in equipment deployment.
The structural signals in the mask inspection equipment market are clear enough to warrant deliberate planning, but the details matter. Regional exposure, modality fit, regulatory readiness, and production-validated acceptance are increasingly the variables that separate durable positioning from short-lived momentum. For decision-makers who need granular segmentation data, competitive benchmarking, and tailored scenario analysis, the full research report provides the deeper ingredient set needed to translate these strategic trends into concrete investment, procurement, and technology roadmapping decisions.
For detailed analysis of this topic, please visit the official page: Mask Inspection Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com