

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Personal Radiation Dosimeter Market: Why 7.2% CAGR Reshapes Radiation Safety by 2032

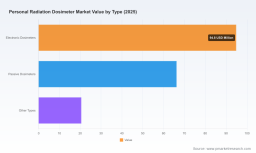
The Personal Radiation Dosimeter Market: Strategic Shifts and Commercial Opportunities (2026–2032)
Market Context and Core Challenges
The personal radiation dosimeter market has settled into a phase of steady expansion, with total revenue projected to grow from approximately $181.5 million in 2025 to over $293 million by 2032, representing a compound annual growth rate of 7.2%. This trajectory reflects a market that has moved past the post-pandemic supply disruptions of the early 2020s and is now anchored by consistent demand from regulated occupational environments. Historical movement from $145.8 million in 2020 through $170.97 million in 2024 shows a market that has successfully stabilized, while the forecast period through 2032 points to accelerating adoption in sectors where real-time exposure tracking is becoming a compliance expectation rather than a discretionary upgrade.
Several structural challenges are shaping how operators navigate this growth. First, the industry is experiencing a capability gap between traditional passive monitoring and the real-time, connected devices that hospitals, nuclear operators, and industrial sites increasingly expect. Passive dosimeters remain essential for legal dose records and accredited processing, but procurement teams are under pressure to supplement them with electronic systems that deliver immediate feedback, wireless telemetry, and integration with existing safety workflows. Bridging this gap requires manufacturers to manage dual product strategies, certification pathways, and service models without diluting quality or margin.
Second, regulatory tightening around dosimetry processing and connected device security is raising the compliance floor. Recent standards updates have clarified performance expectations for active personal dosimeters and periodic evaluation of processing services for X and gamma radiation. At the same time, data-protection requirements are extending into dosimetry registries and service platforms, compelling providers to embed cybersecurity controls into systems that were historically treated as standalone hardware. Companies that treat these requirements as afterthoughts face longer qualification cycles and potential exclusion from regulated contracts.
Third, supply chain resilience remains a strategic vulnerability. Semiconductor availability, sensor calibration consistency, and component traceability all influence lead times and total cost of ownership. Procurement organizations are increasingly evaluating vendors on their ability to guarantee service continuity, processing turnaround, and firmware support over multi-year deployment cycles. In a market where downtime or delayed dose reporting can disrupt operations and compliance documentation, reliability has become a differentiator as important as device performance.
Key Drivers Reshaping Demand and Value Creation
Technology Innovation and Connected Monitoring
A central driver of market expansion is the shift from periodic dose reading to continuous, connected exposure monitoring. Electronic personal dosimeters now increasingly combine real-time radiation detection with temperature, humidity, and location context, feeding data into mobile applications and enterprise safety platforms. This evolution is particularly impactful in healthcare and industrial settings where staff rotate across multiple zones and need immediate awareness of exposure trends. Devices that translate raw measurements into actionable alerts reduce reliance on retrospective review and enable proactive workflow adjustments, such as repositioning personnel or adjusting shielding practices during interventional procedures.
PW Consulting Automotive & Machinery Research Center
The commercial significance lies in the bundle of value these systems create. Buyers are no longer purchasing a badge or a handheld unit in isolation; they are adopting a monitoring ecosystem that includes hardware, software integration, data retention, and reporting interfaces. Manufacturers that design for interoperability, archive compatibility, and user-friendly feedback gain an advantage in repeat procurement cycles. Recent product launches in this space illustrate the direction of travel, with wearable connected devices emphasizing Bluetooth integration and real-time visibility for occupational use. Recognition of these solutions in medical imaging innovation awards further signals that end users are beginning to reward functionality that improves day-to-day safety operations, not just compliance checkbox completion.
Dosimetry Equipment Market
Policy and Regulatory Environment
Regulatory momentum is reinforcing demand for higher-performance dosimetry and more rigorous service oversight. Updated performance criteria for active personal radiation dosimeters are raising expectations for response time, dose rate handling, and reliability in real-time monitoring scenarios. Parallel standards for the periodic evaluation of processors of personal dosimeters introduce clearer benchmarks for processing quality, which matters for organizations that rely on accredited services for legal dose records. In practice, this means procurement teams must align device selection with processing accreditation and service-level commitments, rather than evaluating hardware on technical specifications alone.
Cybersecurity and data governance are also becoming integral to dosimetry procurement. New requirements for technical and methodological risk-management measures for TLD name registries and related service providers indicate that radiation monitoring data is increasingly treated within the broader framework of operational data protection. For vendors, this creates an opportunity to differentiate through secure data handling, auditable access controls, and transparent retention policies. For buyers, it adds a due diligence layer that rewards providers with mature information-security practices and clear contractual commitments.
Demand-Side Changes Across End-Use Sectors
Demand is being reshaped by changes in how organizations manage occupational exposure. In healthcare, growing awareness of cumulative exposure during interventional and diagnostic imaging procedures is driving interest in real-time staff monitoring, especially in high-throughput departments where traditional badge programs provide feedback only after the fact. In the nuclear sector, reactor maintenance, life-extension activities, and restart programs are intensifying the need for reliable personal monitoring with specialized detection capabilities, including algorithms tailored for neutron environments. Industrial and manufacturing users continue to require dependable monitoring for non-destructive testing, radiography, and other source-based operations, but they are increasingly selecting devices that integrate with broader safety systems and minimize administrative friction.
This demand shift is changing purchasing behavior. End users are more likely to evaluate total operational impact—training burden, ease of use, data integration, and processing reliability—alongside unit pricing. Organizations that previously standardized on a single passive solution are now layering electronic devices for high-exposure roles or high-turnover environments, creating hybrid monitoring programs. The result is a more nuanced demand profile in which volume, functionality, and service quality are negotiated together rather than treated as separate line items.
Supply Chain and Cost Structure Evolution
Cost dynamics are influenced by both hardware complexity and service economics. Electronic dosimeters with connected features require more sophisticated sensor integration, firmware management, and post-sales support, which can increase upfront costs but also create opportunities for recurring value through software, calibration, and data services. Meanwhile, passive dosimeter programs remain cost-effective for baseline monitoring, yet their value proposition depends heavily on processing turnaround, badge logistics, and the credibility of accredited dose records. As a result, the cost conversation is moving from unit price to total lifecycle cost, including training, replacement cycles, data management, and compliance risk.
Supply chain considerations further shape cost structures. Long-term availability of critical components, consistency in calibration standards, and the ability to maintain service networks across geographies all affect deployment risk. Buyers are increasingly weighing vendor stability and support capacity alongside product features, especially for multi-site operations where standardized equipment and predictable servicing reduce operational complexity. In this environment, manufacturers with disciplined quality systems and transparent supply planning are better positioned to secure long-term contracts and repeat business.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of specialized dosimetry providers, large scientific instrumentation companies, and regional manufacturers with strong positioning in specific detection technologies. Market concentration reflects a moderately consolidated landscape, where leading players compete on technology integration, service accreditation, and vertical-specific functionality rather than price alone. This structure rewards companies that can combine reliable measurement performance with usable data workflows and recognized processing credentials.
Several strategic patterns are evident among leading companies. Landauer maintains a strong position in occupational monitoring through OSL and TLD-based personal dosimeters, with accredited processing that supports legal dose records. Its differentiation lies in the combination of established detection methods and the service infrastructure required for compliant dose reporting, making it relevant for organizations that prioritize accredited dose of record alongside modern device options. Thermo Fisher Scientific has pushed into connected wearable monitoring with real-time radiation, temperature, and humidity capabilities and Bluetooth/app integration, targeting healthcare and industrial users who want immediate exposure visibility. Its recent wearable launch and recognition in medical imaging innovation categories highlight a strategy centered on usability, connectivity, and workflow integration.
Mirion Technologies offers electronic personal dosimeters for real-time X-ray and gamma monitoring, along with wireless systems for occupational dose tracking. Its approach emphasizes real-time awareness and tracking convenience, which appeals to users seeking to supplement passive programs with active alerting and centralized dose visibility. Polimaster continues to build on electronic personal dosimetry for X-ray and gamma detection in personal monitoring applications, with a focus on practical field usability and specialized detection needs. Fuji Electric has strengthened its relevance in nuclear environments by developing electronic personal dosimeters and exposure management systems that incorporate advanced neutron algorithms, and it has reinforced this positioning through partnership agreements to supply large volumes of dosimeters with neutron capabilities for restarting reactors. Unfors RaySafe contributes a real-time radiation dosimeter option for staff dosimetry in X-ray environments, emphasizing immediate visual exposure feedback and archive integration, which supports operational awareness in imaging settings.
The market is evolving along two reinforcing paths. On one hand, differentiation is increasing as vendors tailor solutions to distinct use cases—healthcare staff monitoring, nuclear applications, industrial radiography, and research environments—each with different detection requirements, usability priorities, and data integration needs. On the other hand, consolidation pressure is growing where buyers prefer fewer vendor relationships that can cover both passive and electronic monitoring, processing services, and data management. New entrants typically need a clear edge in sensor performance, connectivity, cost structure, or regional service capability to gain traction, while incumbent players are investing in firmware updates, app ecosystems, cybersecurity alignment, and partnership networks to defend and expand their positions.
Recent company activities illustrate how this competition is playing out. Innovation recognition for real-time occupational monitoring in medical imaging underscores that end users are rewarding products that improve safety operations in high-exposure clinical settings. Partnership contracts tied to nuclear restart programs show how specialized detection capabilities and supply reliability can translate into sizable deployment opportunities. Product launches emphasizing wearable connectivity and real-time monitoring reflect the broader shift toward devices that fit naturally into daily workflows rather than functioning as standalone compliance tools.
Forward-Looking Trends and Commercial Implications
Hybrid Monitoring Models Become the Norm
Over the next three to five years, the market is likely to move toward hybrid monitoring programs that combine passive dosimeters for accredited legal dose records with electronic devices for real-time awareness in higher-risk roles or high-turnover environments. This model allows organizations to preserve compliance continuity while gaining operational visibility where it matters most. For manufacturers, the opportunity lies in designing product portfolios that interoperate cleanly, supported by consistent data formats, unified reporting, and service arrangements that simplify mixed deployments. For buyers, the strategic task is to define where real-time monitoring delivers enough operational value to justify the added complexity and cost, rather than adopting connected devices uniformly across all roles.
One uncertainty in this trend is the pace at which regulatory guidance and internal safety policies formalize expectations for real-time monitoring. If standards and institutional practices continue to emphasize performance and data reliability for active dosimeters, adoption in healthcare and industrial settings may accelerate more quickly than capacity planning currently anticipates. If implementation remains fragmented, hybrid models may persist longer with uneven feature adoption, creating variability in demand across regions and end-use segments.
Data Integration and Cybersecurity as Purchase Criteria
Data handling is increasingly part of the procurement decision. Real-time dosimeters, app-based feedback, and archive integration create new expectations for data security, access control, retention, and interoperability with existing safety or occupational health systems. As regulatory direction strengthens risk-management expectations for dosimetry-related registries and service providers, organizations will likely evaluate vendors more closely on information-security maturity and contractual clarity. Commercially, this creates a path for providers that can demonstrate secure architectures, reliable data archiving, and transparent service commitments. It also raises the barrier for entrants that offer capable hardware but lack the service and data governance infrastructure needed for regulated environments.
A key risk here is the potential for fragmented standards implementation and differing organizational interpretations of cybersecurity obligations. Buyers may face complexity in comparing vendor claims, while vendors must invest in documentation, validation, and ongoing compliance support. Companies that can simplify this evaluation process—through clear security documentation, standardized integration options, and predictable service terms—will be better positioned to convert technical capability into commercial wins.
Specialized Detection and Vertical-Specific Solutions Gain Importance
As nuclear operations, healthcare imaging, and industrial radiography continue to place distinct demands on personal monitoring, vertical-specific solutions are likely to command greater attention. Devices with advanced neutron algorithms, specialized detection ranges, or integration tailored to imaging workflows can justify premium positioning when they reduce operational risk or improve monitoring accuracy in challenging environments. Large-scale partnership opportunities, such as deployments tied to reactor programs, illustrate how specialized capability combined with supply reliability can unlock volume business that generic solutions cannot easily capture.
The commercial implication is that broad commoditization will be limited to baseline monitoring segments, while differentiated solutions retain pricing power and stronger customer loyalty. The risk is that specialization requires sustained R&D investment and close alignment with operating conditions that may change over time. Vendors must therefore balance deep vertical focus with enough platform flexibility to adapt as applications, regulations, and user expectations evolve.
Strategic Actions for Decision Makers
For Manufacturers and Technology Providers
Build portfolios that connect hardware performance with data usability and service credibility. The most defensible positions will come from offering devices that integrate with existing workflows, support secure data handling, and are backed by reliable processing or service arrangements. Prioritize clear differentiation by end use rather than attempting to compete across all segments with a single general-purpose offering. Invest early in cybersecurity documentation, integration compatibility, and firmware support, since these factors are increasingly part of procurement evaluation in regulated environments. Where specialized detection is relevant, align product development with verified operational needs and secure supply commitments that can support larger deployment programs.
Personal Dosimeter Market
For Investors and Strategic Partners
Focus on companies that demonstrate a credible path to recurring value beyond one-time hardware sales. Models that combine connected devices, software-enabled safety workflows, processing services, and strong compliance credentials are better positioned to capture the operational value driving market growth. Assess exposure to regulatory trends that raise performance and data-security expectations, since these trends can expand demand for higher-quality solutions while also raising the bar for market entry. Pay attention to vertical opportunities where specialized detection or large-scale deployment commitments create meaningful differentiation, and evaluate whether target companies have the service infrastructure to retain customers over multi-year cycles.
For Procurement and Safety Leaders
Define monitoring strategies around actual exposure profiles and operational workflows instead of defaulting to uniform device selection. Hybrid approaches can preserve accredited dose recording while adding real-time visibility where staff face higher variability or cumulative exposure risk. Treat cybersecurity, data retention, integration compatibility, and processing turnaround as core evaluation criteria alongside detection performance. This is also the point where detailed segmentation data, regional dynamics, and vendor-specific capability comparisons become valuable for tailoring specification packages and negotiating service terms. A full market report can support that process by providing structured breakdowns and decision frameworks that match your operating context.
Closing Perspective
The personal radiation dosimeter market is moving from steady compliance-driven growth toward a more capability-led landscape, where real-time monitoring, data integration, and service reliability shape purchasing decisions as much as detection performance. Growth to nearly $293 million by 2032 at a 7.2% CAGR reflects a market that is expanding on the back of regulated occupational demand, technological connectivity, and evolving safety expectations. The organizations that capture the most value will be those that convert these trends into practical solutions for specific end uses, while managing the compliance, cybersecurity, and supply continuity requirements that increasingly define procurement success. For decision makers seeking to act on these dynamics with precision, deeper segmentation detail and customized strategic guidance can sharpen specification, investment, and partnership choices well before the next procurement cycle.
For detailed analysis of this topic, please visit the official page: Personal Radiation Dosimeter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com