

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Zero-Turn Mowers Market: Why 6.92% CAGR Signals Commercial Landscaping Shift

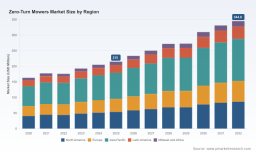
Strategic Trends & Commercial Opportunities in the Zero-Turn Mowers Market
The global zero-turn mowers market has evolved from a specialized commercial tool into a mainstream landscaping solution, driven by labor economics, technological maturation, and shifting regulatory expectations. Over the 2020-2025 period, market revenue expanded from approximately USD 163 million to over USD 215 million, reflecting a compound annual growth rate of 6.92 percent through the 2026-2032 forecast horizon. This trajectory signals a market that is no longer defined by incremental hardware updates but by structural shifts in how turf care is delivered, purchased, and operated. For executives and investors, the opportunity lies not in chasing volume alone but in aligning product strategy, supply chain posture, and commercial models with the forces reshaping the sector.
Market Snapshot & Core Challenges
Zero-turn mowers have consolidated their position as the productivity engine for both commercial landscaping operations and expanding residential user bases. The addressable market spans a wide spectrum of operator profiles, from municipal parks and sports field contractors to homeowners managing larger properties or high-accent turf. Revenue growth has been consistent across cycles, but the pace and composition of demand are increasingly uneven. The market is moving toward higher total value capture, yet that growth is uneven across segments and geographies, reflecting divergent purchasing power, service infrastructure, and regulatory maturity.
Three challenges define the current inflection point. First, talent scarcity is reshaping commercial purchasing behavior. Qualified operators remain difficult to recruit and retain, and the industry’s reliance on skilled labor is becoming a binding constraint on scaling services. Second, emission and noise regulations are no longer regional footnotes; they are becoming design imperatives, particularly in markets where local authorities and large institutional buyers increasingly expect lower-emission equipment fleets. Third, input cost volatility, especially in steel and precision components, is compressing manufacturing margins and forcing companies to reconsider pricing architecture, build-to-order flexibility, and inventory strategies.
These pressures are not isolated. They interact with demand-side expectations for faster cut times, cleaner operation, and lower total cost of ownership. As a result, the market is transitioning from a hardware-centric competition to a system-level contest that includes support networks, operator training, maintenance economics, and compatibility with emerging power sources.
Key Drivers Reshaping the Market
Technology Innovation and Breakthroughs
Product development is increasingly focused on reducing operator fatigue, improving cut consistency, and expanding the applicability of zero-turn platforms beyond traditional turf. Recent model introductions demonstrate a pattern: redesigned cutting decks, suspension and operator-comfort upgrades, and broader width options are being paired with drivetrain refinements that improve maneuverability in tight or irregular sites. These hardware gains are increasingly complemented by options that support autonomous or semi-autonomous operation, particularly in commercial settings where consistent routing and reduced supervision translate into measurable productivity gains.
The significance of this trend goes beyond feature checklists. For commercial users, productivity gains directly offset labor constraints; a machine that reduces mowing time per acre or minimizes rework increases the revenue potential of each operator hour. For residential users, comfort and ease of use influence purchase decisions, especially as ownership replaces rental or service-based models in expanding suburban lots and estate properties. Companies that can translate engineering improvements into demonstrable time savings and lower operating friction are positioned to capture premium demand and reduce price sensitivity.
Policy and Regulatory Environment
Regulatory momentum around small off-road engines is accelerating the shift toward lower-emission and zero-emission platforms. Jurisdictions have moved beyond advisory guidance to enforceable standards, and the implications are cascading through procurement cycles, dealer readiness, and product roadmaps. For manufacturers and commercial fleet operators, compliance is no longer a backward-looking cost center; it is a forward-looking competitive lever that can shape customer preference, service expectations, and site access.
PW Consulting Automotive & Machinery Research Center
At the same time, emission standards are interacting with public-sector and institutional purchasing. Large parks, school campuses, and corporate grounds increasingly align equipment choices with sustainability targets, which makes cleaner-power options commercially relevant even where total acquisition cost remains higher. The result is a bifurcated market dynamic: buyers in regulated or sustainability-sensitive environments are willing to absorb transition costs, while other segments remain highly price-aware. This divergence creates both opportunity and planning risk for suppliers that must manage multiple product pathways without fragmenting their service support.
Automatic Lawn Mower Market
Demand-Side Shifts in Consumer and Business Behavior
Demand is being reshaped by two reinforcing behaviors. On the commercial side, landscape contractors are prioritizing equipment that improves throughput and reduces reliance on large crews. The broader landscape services market’s scale underscores why this matters: mowing remains a high-frequency, labor-intensive activity, and any equipment that increases acres covered per shift directly improves margin potential in a labor-constrained environment. On the residential side, buyers are increasingly treating zero-turn mowers as long-term capital assets rather than discretionary purchases, weighing storage feasibility, maintenance burden, and resale value alongside cutting performance.
Lawn Mower Market
This shifting behavior has strategic implications. Commercial buyers are more willing to invest in higher-upfront equipment if it reduces recurring labor costs and improves scheduling reliability. Residential buyers, meanwhile, are becoming more selective about width, storage footprint, and comfort features, especially where property layouts are irregular or smaller than the widths traditionally favored by commercial setups. The practical takeaway is that “one size fits most” strategies are losing ground to segment-specific value propositions that address time savings, operator experience, and total cost of ownership.
Supply Chain and Cost Structure Dynamics
Input costs remain a persistent source of uncertainty. Steel pricing, in particular, has repeatedly shown up in financial disclosures as a meaningful factor in production expenses, and the sensitivity is heightened because zero-turn mowers incorporate substantial structural steel in decks, frames, and reinforcement points. This cost backdrop is encouraging a more disciplined approach to bill-of-materials design, sourcing diversification, and margin management.
Beyond raw materials, the supply chain conversation is increasingly about responsiveness and modular design. Companies that can offer broader width configurations, interchangeable deck options, and simplified service architectures may reduce fulfillment complexity while improving dealer and operator satisfaction. At the same time, geographic concentration in manufacturing and component sourcing continues to create exposure to logistics disruptions and regional input shocks. For buyers and investors, the key signal is whether suppliers are building cost structures that can absorb volatility without eroding product availability or after-sales support quality.
Competitive Landscape and Leading Strategies
The market is characterized by a mix of broad-portfolio incumbents and specialized commercial manufacturers, each pursuing distinct strategic positions. Deere & Company maintains a comprehensive residential and commercial lineup, emphasizing integrated attachments, hydrostatic drives, and commercial productivity in the ZTrak family. Toro Company has built a strong commercial identity with TimeCutter and Titan series products that prioritize transmission durability, structural reinforcement, and operator comfort features tailored to professional workflows. Husqvarna Group continues to broaden its residential and commercial presence with series focused on comfort upgrades, durability, and consistent cutting performance, reflecting an emphasis on repeatable operator experience across segments.
Honda Power Sports & Products has pushed into battery-powered zero-turn platforms with ProZision models in both manual and autonomous configurations, signaling a strategic emphasis on professional durability combined with cleaner-power options. Exmark Manufacturing Company remains highly focused on commercial zero-turn products, leveraging patented deck designs, suspension systems, and productivity-oriented configurations for professional use. Scag Power Equipment pursues a similar commercial orientation but with an explicit emphasis on dealer-supported service and durability as core differentiators. Cub Cadet targets residential and small commercial applications with wide cutting widths and hydrostatic drives, while Ariens Company balances residential and commercial offerings with an emphasis on comfort and professional-grade durability. Kubota Corporation adds another dimension with commercial zero-turn platforms built around engine and deck systems aimed at professional landscaping and turf applications.
The competitive differentiation is becoming less about brand presence and more about ecosystem fit. Leading players are distinguishing themselves through three overlapping advantages: product architecture that matches segment-specific productivity needs, dealer and service networks that reduce downtime risk, and portfolio breadth that allows customers to standardize across multiple site types. Companies that can deliver consistent performance across varied terrain while maintaining manageable maintenance complexity are gaining trust in commercial procurement cycles, where equipment failure directly affects revenue.
The market structure is evolving along two paths. Consolidation pressure exists where scale, parts commonality, and dealer reach create advantages in cost management and service coverage. At the same time, segmentation is intensifying as manufacturers tailor products to width preferences, power-source choices, and usage intensity. New entrants and technology-forward initiatives are most likely to succeed by targeting specific pain points—autonomous assistance, battery-platform readiness, or specialized commercial deck performance—rather than attempting to compete broadly on price alone. The practical implication is that competitive advantage will increasingly depend on matching product roadmaps to operator economics and purchasing criteria, not simply launching more models.
Future Trends and Commercial Opportunities
Broader Adoption of Lower-Emission and Battery-Ready Platforms
Over the next few years, the share of new zero-turn mowers designed with reduced-emission or battery-compatible architectures is likely to keep rising, particularly in regions with stricter engine standards and among large commercial buyers with sustainability targets. This trend creates opportunities for manufacturers that can offer credible product transitions without sacrificing commercial productivity. Battery-ready platforms, improved energy management, and support infrastructure for charging or battery swap workflows can become differentiators in fleet sales and institutional procurement.
The commercial opportunity lies in designing for transition, not just compliance. Buyers want equipment that can scale with changing site requirements and operator expectations, and suppliers that can offer clear power-option pathways will be better positioned to capture replacement cycles. The risk is that premature standardization or limited charging infrastructure could slow adoption in segments that remain highly sensitive to operating flexibility and runtime.
Productivity-Dominant Purchase Logic
As labor scarcity persists in many service markets, commercial purchasing will increasingly prioritize machines that deliver measurable time savings, simpler operation, and reduced rework. Wider cutting options, improved deck designs, and comfort-focused operator interfaces will be judged against acres covered per shift, fuel or energy efficiency, and ease of maintenance. This productivity-first logic favors suppliers that can quantify operational benefits and support them with training, service, and parts availability.
For investors and manufacturers, the opportunity is to frame product value around site economics. The more clearly a machine reduces total labor dependency per acre or improves scheduling reliability, the more defensible its position in a demand environment where service providers are trying to grow output without proportionally expanding headcount. The uncertainty lies in how quickly autonomous or assisted features will move from niche demonstrations to mainstream commercial workflows, and whether customers will accept the associated training, integration, and liability considerations.
Segmented Width and Platform Strategies
Demand for width options is likely to remain fragmented because site geometry, storage limits, and operator experience vary widely across residential and commercial use. Rather than converging on a single dominant width, the market may continue to support differentiated platforms that target high-productivity commercial layouts on one end and access-sensitive residential or estate properties on the other. Manufacturers that manage width platforms efficiently—through shared components, flexible decking, and modular reinforcement—can reduce complexity while still serving distinct customer needs.
This trend creates an opportunity for portfolio discipline. Companies that can connect multiple width and deck configurations to a common service and parts ecosystem may lower lifecycle costs and improve dealer economics. The risk is overextension: maintaining too many distinct configurations without sufficient volume in each can erode margins and complicate inventory planning, especially when steel and component costs fluctuate.
Actionable Guidance for Decision-Makers
For Manufacturers and Product Strategists
Invest in product architectures that support multiple power options and width configurations without fragmenting service support. The combination of emission momentum, labor constraints, and width diversity makes modularity a strategic asset. Prioritize deck and drivetrain refinements that deliver measurable time savings in commercial use, and ensure that operator-comfort improvements are validated under real service conditions rather than treated as cosmetic enhancements. Pricing and cost strategies should assume continued steel and component volatility, so build flexibility into sourcing, bill-of-materials design, and dealer inventory planning.
For Investors and Corporate Strategists
Focus on companies that combine commercial productivity with credible service and parts ecosystems. In a labor-constrained market, equipment value is increasingly determined by uptime, ease of maintenance, and dealer responsiveness as much as by feature sets. Monitor the pace of battery and lower-emission adoption in commercial fleets, since procurement cycles and replacement timing will shape demand in ways that are not always visible in headline shipments. Be cautious about exposure to suppliers that rely on narrow product mixes or inconsistent after-sales support, as these weaknesses become more apparent when buyers prioritize total cost of ownership.
For Landscaping Operators and Procurement Teams
Evaluate zero-turn mowers against site-specific economics rather than generic feature lists. For commercial operations, prioritize machines that reduce acres-per-labor-hour and simplify maintenance workflows, and assess dealer support as part of the purchase decision because downtime directly affects revenue. For residential and estate use, balance width, storage constraints, and comfort features with long-term ownership costs, including parts availability and servicing complexity. Where emission or sustainability expectations are rising, consider power-option pathways early so equipment choices can align with future procurement requirements without forcing rushed replacements.
Next Steps for Deeper Market Intelligence
The zero-turn mowers market is entering a phase where competitive advantage will be defined by how well companies align product design, service support, and commercial models with labor economics, regulation, and segmentation realities. Broad trends provide direction, but the execution details—width strategy, power-platform timing, cost-structure resilience, and dealer ecosystem strength—determine whether a company captures value or simply participates in growth. Decision-makers who need granular segmentation data, competitive benchmarking, and scenario-based guidance for specific regions or applications will benefit from a fuller market assessment that extends beyond macro trajectory and headline dynamics. A deeper evaluation can help translate these strategic shifts into investment priorities, product roadmaps, and procurement decisions that are calibrated to the market’s next phase of development.
For detailed analysis of this topic, please visit the official page: Zero-Turn Mowers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com