

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: IT & Electronics
DX Strategy and Consulting Market: Why the 12.5% CAGR Through 2032 Reshapes Enterprise Spending
By pmarketresearch, 2026-09-18
Navigating the DX Strategy and Consulting Market: Strategic Trends and Commercial Opportunities Through 2032
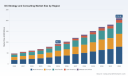
The Digital Transformation (DX) strategy and consulting market has matured beyond the early adoption hype cycle into a structural growth phase. Over the past five years, the sector has expanded from a niche advisory service into a core operational imperative for enterprises worldwide. Current market valuations place the overall industry at approximately $92.5 billion as of 2025, with a projected compound annual growth rate of 12.5% extending through 2032. This trajectory points to a market that will nearly double in size over the forecast period, reaching levels that reflect not only increased spending but also a fundamental shift in how organizations approach technology integration, operational redesign, and workforce transformation.
Worldwide Digital Business Transformation Market
Behind these headline figures lies a more complex reality. The market is no longer driven solely by technology adoption for its own sake. Enterprises are grappling with a series of interconnected challenges that define the current inflection point. First, the gap between investment and outcomes has widened. A significant majority of operations leaders report that technology investments in digital transformation have not fully delivered expected results, signaling a breakdown in execution rather than a lack of funding. This execution shortfall is compounded by fragmented operating models, where strategy, implementation, and change management often operate in silos. Second, the talent landscape has become increasingly constrained. Organizations face persistent shortages in digital skills and AI expertise, driving premium compensation costs and making it difficult to build digital-ready workforces internally. Third, regulatory and policy volatility has introduced new layers of complexity. Data privacy requirements, evolving compliance standards, and shifting trade regulations are forcing companies to rethink DX roadmaps that were designed under more stable conditions.
These challenges are not isolated friction points. They represent structural shifts that are reshaping how value is created in the DX consulting space. The market is moving away from generic transformation playbooks toward more targeted, outcome-driven engagements that account for organizational readiness, regulatory constraints, and measurable performance indicators. Enterprises that recognize this shift early are repositioning their consulting budgets accordingly, while those that continue to treat DX as a technology procurement exercise risk compounding inefficiencies.
Key Drivers Shaping the Market Trajectory
Several interconnected forces are accelerating demand for DX strategy and consulting services. Understanding these drivers is essential for executives and investors evaluating where the market is heading and which segments will capture disproportionate value.
Technology Innovation and the AI Inflection Point
The rapid maturation of artificial intelligence, particularly generative and agent-based systems, has altered the baseline expectations for digital transformation. AI is no longer a standalone initiative; it is becoming embedded in operating models, decision workflows, and customer engagement layers. This shift has created a new category of consulting demand focused on AI integration, data architecture, and organizational rewiring. Enterprises are increasingly seeking partners who can translate AI capabilities into measurable business outcomes rather than experimental pilots. The pressure to move from proof-of-concept to production-scale deployment is driving firms to engage strategic advisors who can align technology roadmaps with operational realities, governance frameworks, and change management requirements.
Worldwide Analytical and Technical Consulting Service Market
At the same time, cloud modernization and hybrid infrastructure strategies continue to serve as foundational enablers. Organizations are restructuring legacy systems to support more agile, data-driven operations, and this process requires coordinated strategy across technology, process design, and workforce capabilities. The convergence of AI and cloud transformation is creating integrated consulting engagements that span strategy, implementation, and ongoing managed services, blurring the lines between traditional advisory work and long-term delivery partnerships.
Regulatory and Compliance Pressures
Regulatory complexity is emerging as a significant catalyst for DX consulting demand. Data privacy frameworks, evolving compliance requirements, and cross-border regulatory standards are increasing the cost and risk of transformation initiatives. Organizations operating in multiple jurisdictions must navigate overlapping legal standards while modernizing their digital infrastructure, a task that requires specialized advisory support. Regulatory and policy volatility is already impacting a majority of operations leaders, particularly in areas related to resilience and trade compliance, prompting adjustments to DX strategies that were designed under more predictable conditions.
This dynamic is pushing consulting engagements toward more compliance-aware transformation models. Firms that can integrate regulatory navigation, data governance, and risk management into their DX strategy offerings are gaining traction with enterprises that view compliance not as a constraint but as a design parameter for transformation. The demand for specialized consulting to manage these complexities is growing as regulatory environments become more fragmented and enforcement more rigorous.
Workforce Transformation and Talent Economics
Demographic shifts and AI adoption are reshaping workforce needs at a pace that many organizations are struggling to match. The need for upskilling, new talent strategies, and digital-ready organizational designs is becoming a central component of DX strategy. Labor cost pressures are intensifying as demand for digital skills and AI expertise outpaces supply, and companies are increasingly turning to external partners to help design workforce transformation plans, training programs, and operating models that can absorb new technologies effectively.
This driver is particularly relevant for mid-sized enterprises and regional players that lack the internal capacity to build comprehensive digital talent pipelines. Consulting engagements are expanding beyond technology strategy to include human capital integration, change management, and capability-building frameworks. The organizations that succeed in this environment are those that treat workforce transformation as a core pillar of DX rather than a secondary implementation concern.
Demand-Side Shifts in Enterprise Behavior
Enterprise buyers are becoming more sophisticated in how they evaluate and procure DX consulting services. The earlier pattern of large, undifferentiated transformation programs is giving way to more modular, outcome-focused engagements. Companies are prioritizing measurable business outcomes, shorter time-to-value, and clearer accountability structures. This shift is reflected in the growing emphasis on performance-driven digital transformations, where strategy consulting is tied closely to execution metrics, operating model redesign, and continuous improvement frameworks.
At the same time, private equity and growth-focused investors are driving demand for DX strategy services that can accelerate value creation in portfolio companies. The focus on results, operational efficiency, and scalable growth models is pushing consulting firms to develop frameworks that can be deployed rapidly across multiple entities while maintaining consistency in execution quality. This investor-driven demand is adding a new dimension to the market, particularly in sectors where digital maturity varies widely across portfolio assets.
Competitive Landscape and Strategic Positioning
The DX strategy and consulting market is characterized by a mix of global integrators, strategy-focused consultancies, and specialized technology implementation firms. Market concentration remains moderate, with the top players holding a combined share that leaves substantial room for regional specialists, niche providers, and new entrants. This fragmentation is both a challenge and an opportunity, as enterprises increasingly seek partners with specific industry expertise, regional capabilities, or differentiated delivery models.
Strategic Positioning of Leading Players
Several firms have established distinct positioning within the market, reflecting different approaches to DX strategy and delivery:
- Accenture has built a comprehensive end-to-end model that spans DX strategy, technology transformation, AI, cloud, and digital operating model design. Its strength lies in scale, industry coverage, and the ability to integrate strategy with large-scale implementation. Recent partnerships, such as its selection as a business and technology consulting partner for major global sports organizations, illustrate its focus on multi-year digital transformation engagements that combine AI, data insights, and infrastructure upgrades.
- Deloitte emphasizes comprehensive DX strategy consulting with strong integration of human capital, technology implementation, and measurable business outcomes. Its approach reflects an understanding that transformation success depends as much on organizational readiness and people integration as on technology selection.
- McKinsey & Company positions itself in the high-end strategy segment, with emphasis on AI integration, organizational rewiring, and performance-driven transformations. Its model targets enterprises seeking strategic clarity and executive alignment before scaling execution.
- Boston Consulting Group (BCG) blends technology strategy with human capabilities, innovation frameworks, and industry-specific roadmaps. Its differentiation centers on aligning digital transformation with broader business strategy and innovation agendas.
- Capgemini focuses on DX consulting across cloud transformation, AI, cybersecurity, and intelligent industry solutions. Its positioning appeals to enterprises looking for technology-heavy transformation with strong implementation depth.
- IBM Consulting leverages its background in hybrid cloud, AI, and enterprise systems modernization to offer DX strategy and implementation services. Its value proposition is strongest for organizations modernizing complex legacy environments.
- PwC delivers DX strategy with emphasis on operations, AI-driven performance, and regulatory compliance. Its approach integrates transformation with risk management and operational execution.
- ABeam Consulting has strengthened its technology consulting delivery capabilities in India and expanded support for the establishment, operation, and advancement of Global Capability Centers (GCCs). Recent recognition, including regional SAP Partner Awards, highlights its focus on execution frameworks, SAP integration, and Asia-Pacific market expertise. The firm has also highlighted the persistent challenge of turning AI investments into measurable business value, reflecting a broader industry concern.
- Bain & Company provides strategy-led digital transformation consulting focused on results, private equity, and growth acceleration. Its positioning is particularly relevant for investors and enterprises seeking outcome-driven engagements with clear value creation metrics.
- Cognizant specializes in digital experience, application modernization, and cloud-enabled DX strategy services. Its strength lies in bridging digital front-end experiences with backend modernization.
- Infosys Consulting delivers AI-first cloud and digital transformation strategy and implementation services, positioning around integrated technology and strategy delivery.
- Tata Consultancy Services (TCS) provides comprehensive DX strategy, consulting, and large-scale technology transformation services globally, with scale and breadth across industries and regions.
Market Evolution and Structural Shifts
The competitive landscape is evolving along several dimensions. Integration is occurring as large firms expand their capabilities across strategy, implementation, and managed services to capture more of the transformation value chain. At the same time, specialization is increasing as enterprises seek partners with deep industry expertise, regional delivery capabilities, or focused technology competencies. The growth of Global Capability Centers is reshaping delivery models, with firms like ABeam expanding support for GCC establishment and operation, reflecting a broader trend toward distributed talent and cost-optimized delivery structures.
New entrants and regional players are gaining traction by offering niche expertise, faster engagement models, or stronger local market knowledge. The market is not consolidating into a single dominant model; rather, it is differentiating into layers of strategy advisors, implementation partners, managed services providers, and capability builders. Enterprises are increasingly combining multiple partners to address different aspects of transformation, which is pushing consulting firms to clarify their value propositions and avoid overlap.
Future Trends and Commercial Opportunities (2026–2032)
Looking ahead, several trends are likely to define the next phase of growth in the DX strategy and consulting market. These trends carry direct implications for commercial strategy, partnership models, and investment allocation.
From Strategy to Outcome Accountability
The gap between DX investment and realized outcomes will drive demand for more accountable consulting models. Enterprises are increasingly expecting strategy engagements to include clear execution pathways, performance metrics, and governance structures. Consulting firms that can bridge strategy and measurable results will capture greater share of wallet, while those that remain confined to advisory-only models may face pricing pressure and reduced differentiation. This trend creates opportunities for firms that integrate strategy, implementation oversight, and change management into cohesive delivery frameworks.
AI-Embedded Transformation as a Standard Engagement Layer
AI integration will become a baseline component of DX strategy rather than a separate workstream. Consulting engagements will increasingly address data readiness, AI governance, workflow redesign, and workforce adaptation as interconnected elements of transformation. Firms that can offer structured approaches to AI adoption, including risk management, compliance alignment, and value measurement, will be better positioned to serve enterprises navigating the transition from pilot activity to scaled deployment. The commercial opportunity lies in helping organizations convert AI investment into operational impact, a challenge that remains broadly unmet across industries.
Regional Capability Centers and Distributed Delivery Models
The expansion of Global Capability Centers and distributed delivery models is reshaping how DX services are structured and priced. Organizations are seeking partners who can support the establishment, operation, and advancement of capability centers that combine cost efficiency with local market knowledge and technology expertise. This trend is creating opportunities for consulting firms with strong regional footprints, talent development capabilities, and experience in setting up sustainable delivery structures. The firms that can help clients build long-term internal capacity, rather than relying solely on external delivery, will benefit from deeper relationships and recurring engagement potential.
Risk and Uncertainty Factors
Several variables could shape the pace and direction of market growth. Regulatory fragmentation may increase compliance costs and slow certain transformation initiatives, particularly in sectors with heavy data and privacy requirements. Talent shortages could constrain execution capacity, forcing firms to invest more heavily in training, automation, and delivery innovation. Economic volatility may lead some enterprises to delay large-scale transformation programs, shifting demand toward smaller, faster engagements with clearer near-term returns. Finally, the risk of AI investment failing to produce measurable value remains a persistent concern, and organizations that cannot demonstrate tangible outcomes may reduce spending or reallocate budgets to alternative priorities.
PW Consulting Information & Electronics Research Center
Strategic Implications for Decision-Makers
The DX strategy and consulting market is entering a phase where differentiation depends on execution clarity, outcome accountability, and the ability to navigate regulatory and workforce complexities. Decision-makers across different roles should consider the following priorities:
- For enterprises and manufacturers : Treat DX strategy as an operating model redesign effort rather than a technology procurement exercise. Prioritize engagements that link AI, cloud, and process transformation to measurable performance indicators, and ensure that change management and workforce upskilling are embedded from the outset. Evaluate partners based on their ability to connect strategy to execution accountability, not just advisory breadth.
- For investors and private equity stakeholders : Focus on DX consulting providers and portfolio companies that demonstrate clear value creation frameworks, scalable execution models, and alignment between strategy and operational outcomes. The growing emphasis on results-driven transformation and GCC-enabled delivery models offers opportunities to identify assets with stronger long-term transformation capacity.
- For procurement and sourcing leaders : Move beyond price-based selection toward capability-based evaluation. Assess consulting partners on their proficiency in regulatory navigation, AI integration, workforce transformation, and regional delivery infrastructure. Structured sourcing that accounts for compliance, talent availability, and execution track record will reduce the risk of transformation underperformance.
The dynamics shaping this market are evolving quickly, and the window for strategic positioning is narrowing. Enterprises and investors that deepen their understanding of segment-level demand, regional capability shifts, and emerging engagement models will be better equipped to allocate resources, select partners, and capture value as the market expands. For those seeking a more detailed view of segmentation patterns, regional breakdowns, and customized strategic guidance, the full research report provides a comprehensive foundation for planning and execution decisions.
For detailed analysis of this topic, please visit the official page: DX Strategy and Consulting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Pyrogenicity Testing Market: Why 8.25% CAGR and Regional Shifts Redefine Strategy
By pmarketresearch, 2026-09-18
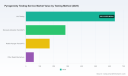
Strategic Shifts in the Pyrogenicity Testing Service Market: Navigating Growth, Regulation, and Innovation
Market Overview and Core Challenges
The pyrogenicity testing service market has evolved from a compliance-driven niche into a strategically important segment within the broader biopharma and medical device testing landscape. Over the past five years, the sector has demonstrated consistent expansion, reflecting the growing complexity of biologic development, the proliferation of implantable and advanced medical devices, and a gradual but decisive shift away from animal-based testing paradigms. The trajectory suggests a market that is maturing in terms of technical capability and regulatory alignment, while still navigating structural friction around method adoption, capacity planning, and cross-regional harmonization.
From a macroeconomic standpoint, the market has moved past the volatility associated with early-stage diagnostic and testing disruptions and entered a phase of more predictable growth. Demand is now anchored by expanding drug pipelines, increasingly stringent safety requirements for novel modalities, and the ongoing modernization of quality control workflows. Yet, beneath the headline growth, several operational and strategic challenges are reshaping how service providers, manufacturers, and regulators interact with pyrogen testing. One persistent tension lies in the pace of regulatory acceptance for non-animal methods. While monocyte activation testing and other in vitro alternatives have gained substantial scientific credibility, implementation timelines, validation requirements, and regional differences in end-user expectations continue to introduce complexity into product registration strategies. Companies developing biologics or devices for multiple markets must balance the scientific advantages of newer methods against the practical realities of parallel qualification pathways.
A second challenge centers on capacity and specialization. As demand for pyrogen testing broadens beyond traditional endotoxin screening, laboratories are under pressure to support a wider range of analytes, matrices, and product categories. This is especially relevant for advanced therapies, combination products, and device-drug hybrids, where material-mediated responses and non-endotoxin pyrogens require more nuanced assessment. Service providers that cannot scale specialized assays, interpret complex biological signals, or offer regulatory-ready documentation may find themselves squeezed between highly specialized niche players and large global testing organizations with broader service portfolios.
A third structural challenge involves the alignment of supply-side capabilities with evolving demand-side expectations. Manufacturers are increasingly looking for testing partners that can integrate pyrogenicity assessment earlier in development, reduce iteration cycles, and provide data that support both safety evaluation and regulatory submission. At the same time, cost pressures in pharmaceutical and device development are pushing organizations to optimize testing strategies without compromising compliance or patient safety. This environment favors providers that can deliver method flexibility, predictable turnaround, and consultative support for test selection, rather than offering testing as a purely transactional service.
For decision-makers, these challenges translate into a clear operational message: pyrogen testing is no longer a standardized checkpoint but a strategic variable in development planning, regulatory positioning, and partner selection. The organizations that respond effectively will be those that treat method choice, testing timeline, and vendor capability as integrated components of product strategy rather than isolated laboratory tasks.
Key Drivers Shaping Market Dynamics
The growth and transformation of the pyrogenicity testing service market are being driven by a combination of scientific advancement, regulatory momentum, evolving product complexity, and changing procurement expectations. These forces do not operate in isolation; rather, they reinforce one another and create a market environment where method innovation and service capability increasingly determine competitive advantage.
Pharmaceutical Testing Services Market
Scientific and Methodological Innovation
One of the most significant drivers is the maturation of non-animal testing methods. Monocyte activation testing, in particular, has moved from an emerging alternative to a credible, increasingly adopted approach for detecting both endotoxin and non-endotoxin pyrogens using human-derived blood cells. This capability addresses a long-standing limitation of methods focused primarily on bacterial endotoxin, offering a broader view of pyrogenic risk. For manufacturers, that broader coverage can support more comprehensive safety evaluation and reduce dependence on methods that are increasingly misaligned with institutional goals to minimize animal use.
The growing emphasis on in vitro alternatives also reflects a wider shift in testing philosophy: from reactive detection toward more mechanistically informative assessment. As assay systems improve and validation frameworks mature, service providers are better positioned to offer MAT and related alternatives in a way that is both scientifically robust and regulatory-compatible. This evolution is especially important for biologics, vaccines, and complex medical devices, where pyrogenicity concerns may not be fully captured by a single endpoint or method.
Regulatory and Policy Momentum
Regulatory developments are accelerating the transition toward non-animal pyrogen testing and reshaping compliance expectations across regions. In Europe, pharmacopoeial standards have increasingly favored replacement of the rabbit pyrogen test with non-animal approaches for applicable products, creating a clear directional signal for manufacturers and testing laboratories alike. Parallel validation strategies and regulatory discussions have also supported broader acceptance of MAT as a practical alternative to traditional rabbit-based testing in certain contexts, helping reduce uncertainty around method substitution.
At the same time, device and drug authorities continue to set expectations for pyrogen limit specifications, particularly for implants and products contacting sensitive biological systems or marketed with non-pyrogenic claims. These requirements do not simply mandate testing; they influence test selection, study design, and documentation standards. The cumulative effect is a environment in which compliance is still essential but is increasingly interpreted through the lens of method suitability, risk coverage, and alignment with modern quality systems.
Expanding Demand From Complex Products
Demand-side changes are also a major driver. Pharmaceutical and biotechnology companies continue to advance a broader range of biological products, and medical device manufacturers are developing increasingly sophisticated implantable, interventional, and combination technologies. These products raise more complex questions about material compatibility, immune response, and pyrogen-related risk. Testing requirements therefore expand not only in volume but also in technical breadth, as manufacturers seek data that account for both endotoxin and non-endotoxin pyrogens, different contact pathways, and device-specific exposure scenarios.
In parallel, research and academic institutions contribute to demand through product development, method validation, and translational projects. While their purchasing patterns differ from commercial manufacturers, these organizations support the broader ecosystem by generating evidence, refining assay applicability, and training the next generation of quality and regulatory professionals. The combined effect is a diversified demand base that strengthens market resilience while also raising expectations for methodological flexibility.
Operational and Capacity Considerations
Finally, the market is being shaped by supply-side dynamics around laboratory capacity, regional service networks, and the economics of specialized testing. As method portfolios expand, laboratories must invest in trained personnel, controlled biological materials, and quality systems capable of supporting reproducible performance. This creates a barrier to rapid entry for less specialized providers, while rewarding organizations that can integrate pyrogen testing into broader microbiology, biocompatibility, and quality assurance services.
Pyrometers Market
Cost structures are also influenced by the need to support multiple methods across regions and product types. Companies that rely on a single testing approach may face higher risk if that method is restricted, delayed, or deemed unsuitable for a specific product category. Conversely, service providers with multi-method capability and strong documentation support can offer greater predictability, which becomes a valuable commercial differentiator in a market where development timelines and regulatory submissions are tightly managed.
Competitive Landscape and Leading Strategies
The pyrogenicity testing service market is characterized by a mix of global testing organizations, specialized life science service providers, and focused suppliers with deep expertise in endotoxin and pyrogen detection. Market concentration remains moderate, meaning that while leading players hold meaningful share, there is still room for differentiation through method capability, regional reach, and application-specific expertise. In this environment, competitive advantage is less about scale alone and more about the ability to offer credible, compliant, and flexible testing solutions across a changing regulatory and product landscape.
Strategic Positioning of Leading Providers
Several established companies illustrate different strategic paths within the market. Charles River Laboratories has built a broad contract testing presence that spans MAT, RPT, and LAL-based endotoxin testing across global laboratories, with service coverage relevant to biologics and medical devices. Its positioning emphasizes breadth, global delivery, and the ability to support multiple testing needs within a single organization, which can be attractive to manufacturers managing complex development programs across regions.
Eurofins BioPharma Product Testing has focused on integrating MAT, rFC, and LAL endotoxin services within a global network that supports regulatory compliance, while also aligning with the transition toward non-animal methods. This approach reflects a broader strategy of combining method flexibility with compliance-oriented service design, which helps address manufacturer concerns about method substitution and multi-market registration.
PW Consulting Information & Electronics Research Center
NAMSA has carved out a distinctive role through its emphasis on biocompatibility and microbiology testing for medical devices, including material-mediated pyrogenicity assessment aligned with ISO 10993-11 and USP expectations. For device manufacturers, this specialization is strategically important because pyrogen testing cannot always be separated from broader biocompatibility evaluation, especially for products where material contact and systemic exposure must be assessed together.
Lonza occupies a distinct position through its provision of MAT systems and related pyrogen testing solutions that support replacement of rabbit-based approaches. Its relevance in the market stems not only from service provision but also from its association with equipment and assay infrastructure that enable consistent in vitro testing. This creates a linkage between product enablement and service delivery, which can strengthen long-term engagement with laboratories and manufacturers seeking standardized non-animal workflows.
SGS contributes through a broad pharmaceutical and medical device testing portfolio that includes pyrogen and endotoxin services such as MAT. Its advantage lies in the integration of pyrogen testing into a wider analytical and compliance framework, allowing customers to consolidate testing needs and reduce coordination friction across multiple evaluation domains.
Associates of Cape Cod, Inc. represents a more focused model, centering on LAL-based endotoxin and pyrogen detection products and services. This specialization supports customers with strong endotoxin-related needs and illustrates how a narrower portfolio can remain competitive when it delivers deep technical credibility and consistent assay performance.
Market Evolution Trends
Looking across this competitive set, several trends are shaping the market’s evolution. First, differentiation is increasingly tied to method flexibility. Providers that can support MAT alongside LAL and other alternatives are better positioned to serve customers navigating transition periods, multi-region submissions, and product-specific method suitability questions. Second, service integration is becoming more valuable. As manufacturers seek efficiency, they often prefer partners who can connect pyrogen testing with biocompatibility, microbiology, and quality support rather than treating it as an isolated service line. Third, geographic reach and local regulatory familiarity remain important. Even as non-animal methods gain momentum, operational realities differ by region, and providers with established laboratory networks and regional compliance knowledge can respond more effectively to customer requirements.
The market also appears open to further consolidation and to entry by organizations that can combine scientific credibility with strong service execution. Larger testing platforms may pursue expansion through capability acquisition or network broadening, while specialized players may strengthen their position by deepening expertise in device-related pyrogenicity, non-animal methods, or specific therapeutic categories. In either case, the winners are likely to be those that can translate technical capability into predictable, regulatory-ready outcomes for customers.
Future Outlook and Strategic Opportunities
Over the next three to five years, the pyrogenicity testing service market is likely to be defined by deeper adoption of non-animal methods, broader integration of pyrogen assessment into early development, and continued regional differentiation in regulatory implementation. These trends create opportunities for organizations that can align method strategy with product development timing and compliance planning.
One key trend is the increasing normalization of MAT and related in vitro approaches as primary options for many applications. As validation experience accumulates and regulatory expectations continue to evolve, non-animal testing is expected to become less of a transitional choice and more of a default consideration for appropriate product categories. This shift will likely increase demand for providers with robust MAT capability, reliable human blood cell sourcing, and documented performance across relevant matrices and product types. For manufacturers, the opportunity lies in designing development and submission strategies that take advantage of broader pyrogen coverage earlier, rather than treating non-animal testing as a late-stage alternative.
A second trend is the growing importance of application-specific testing strategies. Medical devices, biologics, and combination products will continue to create distinct pyrogenicity questions, and service providers that can tailor methods to material type, exposure scenario, and regulatory target will have a competitive edge. This favors a model in which testing is embedded into product risk assessment and quality planning, not treated as a stand-alone compliance step. Companies that can guide test selection, interpret results within a broader safety context, and produce submission-ready documentation will be particularly valuable.
A third trend is the continuing influence of regional regulatory timing. Even when scientific consensus moves in one direction, practical adoption can lag in certain markets or product contexts. That means multi-market manufacturers and global testing providers must maintain method portfolios that can accommodate differing expectations without creating unnecessary duplication or delays. The commercial opportunity here belongs to organizations that can manage regional variability while preserving efficiency and consistency in overall testing strategy.
Potential risks include uneven regulatory implementation, validation complexity for specialized products, and the possibility that some applications remain dependent on traditional methods for longer than anticipated. Supply chain constraints for biological reagents, training requirements for specialized assays, and the need for strong quality systems may also limit how quickly new capacity can be deployed. Decision-makers should therefore consider not only which methods are scientifically preferable, but also which partners can deliver them consistently under real-world compliance conditions.
Strategic Recommendations for Decision-Makers
For pharmaceutical and biotechnology manufacturers, the priority should be to incorporate pyrogen testing method strategy into development planning earlier. Selecting and validating appropriate methods before late-stage programs can reduce rework, support smoother regulatory interactions, and improve alignment with non-animal testing direction where applicable. Companies should also evaluate testing partners on the basis of method breadth, documentation quality, and ability to support product-specific risk assessments, rather than on price alone.
For medical device manufacturers, the emphasis should be on integrating pyrogenicity evaluation with biocompatibility and material selection processes. Because device-related pyrogen risk can depend on material behavior, contact pathway, and intended use, a fragmented testing approach may create gaps in evidence or delay design decisions. Engaging service providers with device-focused expertise and clear familiarity with relevant standards can help ensure that testing supports both safety and regulatory readiness.
For investors and strategic planners, the opportunity lies in identifying organizations that combine multi-method capability with strong compliance infrastructure and regional delivery capacity. The market’s growth is unlikely to be evenly distributed; value will increasingly accrue to providers that can support transition to non-animal methods, serve complex product categories, and maintain predictable quality across expanding demand. Assessing these capabilities in detail requires segmentation-level data, customer-side demand patterns, and provider-level operational comparisons that go beyond aggregate market figures.
In a market shaped by simultaneous scientific progress, regulatory transition, and product complexity, timely and granular intelligence is a practical asset. Detailed segmentation data, provider benchmarking, and region-specific regulatory mapping can sharpen strategy during periods when method choice and partner selection have outsized impact on development speed and compliance outcomes. Readers seeking a more detailed breakdown of segments, competitive dynamics, and forward-looking scenario analysis may find value in reviewing the complete PW Consulting market report for pyrogenicity testing services.
For detailed analysis of this topic, please visit the official page: Pyrogenicity Testing Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Crowd Management Solution Market: Why 8.5% CAGR and Software Analytics Reshape 2032 Trajectories
By pmarketresearch, 2026-09-18
Crowd Management Solution Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
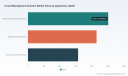
The global crowd management solution market has established itself as a critical infrastructure sector, valued at approximately USD 2.5 billion in 2025 and projected to expand at a compound annual growth rate of 8.5 percent through 2032. This trajectory reflects more than incremental growth; it signals a structural shift in how organizations approach public safety, operational efficiency, and visitor experience. Over the past five years, the market has evolved from a fragmented collection of manual security practices into a technology-enabled discipline that integrates real-time analytics, automated monitoring, and coordinated personnel deployment. Trade show venues, sports stadiums, transportation hubs, and urban public spaces now treat crowd flow as a measurable operational variable rather than an unpredictable risk factor.
Despite this momentum, the industry faces a set of interconnected challenges that will shape competitive positioning over the coming years. The first challenge revolves around regulatory tension between advanced monitoring capabilities and privacy expectations. As operators deploy video analytics, sensor networks, and behavioral detection tools, they must navigate evolving data protection frameworks that restrict personal data collection and automated profiling in public environments. Compliance has shifted from a legal checkbox to a strategic design constraint, forcing vendors and end users to architect solutions that deliver visibility without compromising individual privacy.
The second challenge lies in the persistent reliance on large-scale human staffing alongside technology. High-profile events and dense public venues still require thousands of trained personnel to manage access, queueing, emergency response, and guest services. Labor availability, training consistency, and wage inflation create operational volatility that pure software deployments cannot fully absorb. Organizations are now pressured to determine where technology can reduce headcount dependency versus where human judgment remains indispensable, particularly during unplanned surges or incidents.
A third challenge concerns integration complexity. Crowd management no longer exists in isolation; it intersects with access control, video surveillance, communication systems, and venue operations platforms. Buyers frequently encounter fragmented vendor ecosystems, incompatible data streams, and uneven maturity across solution components. The organizations that succeed will be those that can standardize data flow across hardware, analytics, and staffing coordination while maintaining scalability across multiple sites or event types. These challenges do not diminish the market's growth outlook; rather, they define the criteria by which differentiated solutions will win demand.
Key Drivers Shaping Market Evolution
Technology Innovation and Behavioral Analytics
The most transformative driver is the maturation of AI-powered crowd behavior analysis and non-intrusive sensing technologies. Advanced video analytics now enable congestion detection, dwell-time measurement, anomaly recognition, and directional flow mapping in real time. These capabilities move crowd management beyond reactive security toward predictive operational control. At the same time, privacy-first sensing modalities such as LiDAR-based people flow analytics are gaining traction in airports, transport hubs, and event venues. By focusing on aggregate density, queue progression, and movement patterns rather than identifiable personal data, these solutions align operational insight with increasingly stringent privacy norms.
This technological shift has practical commercial implications. Venue operators can optimize staffing allocation, reduce bottleneck-related revenue loss, and improve safety outcomes without relying solely on manual observation. For solution providers, the value proposition is expanding from hazard prevention to operational efficiency and visitor experience enhancement. Companies that combine behavioral analytics with intuitive dashboards and actionable alerting are positioning themselves as operational partners rather than purely security vendors.
Regulatory Environment and Compliance as a Design Discipline
Regulatory developments are actively reshaping solution architecture. Data protection regimes and emerging AI governance frameworks are pushing vendors toward anonymized data processing, transparent data handling, and controls on automated decision-making in public spaces. This environment elevates privacy-by-design from a technical feature to a competitive requirement. Solutions that can demonstrate anonymized flow analytics, limited data retention, and clear usage boundaries are better positioned for public-sector procurement and multinational deployments.
For buyers, regulatory compliance introduces both risk and guidance. It restricts indiscriminate monitoring but also provides a clearer framework for evaluating vendor claims. Procurement teams are increasingly scrutinizing data pipelines, storage practices, and algorithmic transparency before committing to long-term deployments. This dynamic rewards suppliers that can document compliance rigorously and build flexibility into their platforms to accommodate jurisdiction-specific requirements.
PW Consulting Information & Electronics Research Center
Demand-Side Shifts in Visitor Experience and Safety Expectations
Crowd management is increasingly viewed through a dual lens of safety and experience. Event organizers, transport authorities, and commercial venue operators face rising expectations from visitors who expect seamless entry, predictable wait times, and responsive service during peak periods. Simultaneously, risk awareness has increased across public infrastructure, driven by higher attendance volumes, complex event programming, and heightened media scrutiny following operational disruptions.
This demand evolution is changing purchasing behavior. Organizations are investing in integrated crowd management that links flow analytics with access control, guest communication, and staffing dispatch. The goal is not only to prevent incidents but to smooth throughput, reduce friction points, and maintain brand reputation during high-traffic periods. As a result, solution value is being measured by operational continuity and visitor satisfaction alongside traditional security metrics.
Cost Structure and Labor Dynamics
The economics of crowd management continue to be influenced by labor intensity and staffing scalability. Major providers deploy large teams for high-profile events, and the availability of trained personnel remains a constraint in many markets. Wage pressures and turnover intensify the need for tools that improve staff efficiency, enhance situational awareness, and reduce manual coordination overhead.
These cost dynamics encourage a hybrid operating model. Technology handles repetitive monitoring, density threshold alerts, and flow optimization, while human teams focus on exception handling, guest assistance, and incident response. The commercial opportunity lies in solutions that demonstrably improve labor productivity without eroding service quality. Vendors that can connect analytics to staffing dispatch, route guidance, and real-time communication are better aligned with operator economics.
Competitive Landscape and Leading Strategies
Strategic Positioning Across the Value Chain
The competitive field spans traditional security and staffing providers, technology developers, and analytics specialists, each pursuing distinct strategic positioning. Large integrated security firms leverage scale, venue relationships, and multi-service offerings that combine personnel deployment with access control and command-center coordination. Their advantage lies in trusted relationships with event organizers and the ability to deliver end-to-end operational support during complex events. Technology-focused players differentiate through AI-driven behavior analysis, real-time monitoring, and sensor-based flow measurement. Their strength is in converting raw observation into predictive insight, enabling operators to intervene earlier and manage congestion more efficiently.
A distinct segment of entrants emphasizes privacy-preserving analytics and smartphone-sensor-based visitor flow analysis. These approaches attract buyers who need visibility across dense environments while minimizing personal data exposure. The strategic appeal is twofold: they satisfy compliance-sensitive procurement requirements and offer a lighter integration footprint for venues that want flow intelligence without full infrastructure replacement.
Differentiation Through Partnerships and Venue Networks
Recent commercial activity highlights how partnerships are becoming a decisive growth lever. Strategic alliances with large venue networks can dramatically expand deployment reach and standardize solution adoption across multiple sites. Partnerships with specific sports franchises or stadium operators also create high-visibility reference points that validate performance under demanding matchday or event conditions. These collaborations signal a shift from standalone product sales toward embedded operational relationships, where crowd management becomes part of the venue's ongoing service model rather than a one-off implementation.
The commercial implication is clear: distribution advantage increasingly depends on access to venue networks, event calendars, and operational procurement cycles. Providers that can align with venue operating rhythms and demonstrate measurable improvements in flow, safety, and guest service are more likely to secure multi-year relationships.
Market Structure and Evolution Trends
The market remains moderately concentrated, with leading players collectively holding meaningful share but far from dominating the entire ecosystem. This structure leaves room for specialization, particularly in analytics, privacy-first sensing, and vertical-specific deployments. Over the next several years, three patterns are likely to intensify. First, consolidation may accelerate as larger security and technology firms acquire niche analytics capabilities to broaden their offerings. Second, fragmentation may persist in verticals where specialized flow analytics, venue-type expertise, or regional compliance knowledge create durable differentiation. Third, new entrants will continue to emerge around non-intrusive sensing and real-time operational intelligence, especially where privacy expectations and integration simplicity are prioritized.
Content Moderation Solution Market
Competitive success will depend on more than feature breadth. Vendors will be judged on deployment speed, data governance clarity, interoperability with existing access and surveillance assets, and the ability to translate analytics into staffing and operational decisions. The firms that can connect technology outputs to day-to-day venue execution will capture the strongest positioning.
Future Outlook: Trends and Commercial Implications
Convergence of Analytics, Access Control, and Staffing Coordination
Over the next three to five years, crowd management solutions are expected to move toward tighter integration across analytics, access systems, and personnel dispatch. Standalone monitoring will increasingly give way to coordinated workflows where density thresholds trigger staffing adjustments, entry pacing, and guest communication automatically or with minimal manual intervention. This convergence creates commercial opportunity for platforms that can orchestrate multiple functions without requiring full rip-and-replace of existing infrastructure. Vendors that offer modular integration and clear operational playbooks will be better positioned to scale across diverse venues.
Privacy-First Sensing as a Default Expectation
Privacy-preserving technologies are likely to transition from niche alternatives to baseline expectations in many public-facing deployments. As enforcement and public sensitivity increase, solutions that rely on anonymized flow measurement, aggregated density metrics, and minimal personal data capture will gain preference in both public-sector and commercial procurement. This trend opens opportunities for sensor-based analytics and software layers that can retrofit or complement existing environments while maintaining compliance comfort. The risk lies in solutions that depend on data practices requiring continuous legal interpretation or that struggle to demonstrate transparent data handling.
Operational Experience as a Growth Battleground
Crowd management will increasingly be evaluated through its impact on visitor throughput, queue management, and event-day reliability. The commercial narrative is expanding from safety alone to overall venue performance, where smoother crowd flow contributes to revenue protection, reduced congestion complaints, and stronger repeat attendance. Organizations that can quantify these benefits will have stronger justification for investment and expansion. At the same time, uncertainty remains around labor market stability, regulatory evolution, and the pace at which venues standardize integrated platforms. Buyers and suppliers alike will need to manage implementation risk while building evidence of operational ROI.
Implications for Decision-Makers
For technology manufacturers and analytics providers, the priority is to build solutions that combine predictive crowd insight with privacy-conscious data handling and practical integration paths. Differentiation will come from reducing deployment friction, supporting interoperability with access control and existing video assets, and proving that analytics translate into staffing efficiency and throughput improvements. Companies that can package these capabilities into repeatable deployment models will be better positioned to expand across venues and event types.
People Counting System Market
For investors, the market's growth trajectory is supported by durable demand drivers, but value creation will likely concentrate among providers with clear compliance posture, scalable venue partnerships, and credible operational outcomes. Due diligence should assess not only technology sophistication but also data governance, integration complexity, and the ability to move beyond pilot deployments into multi-site contracts. Vertical specialization and privacy-first positioning may offer defensible niches, while broader platforms may win through partnership networks and service integration.
For procurement leaders and venue operators, the most effective approach is to evaluate crowd management as an operational system rather than a discrete security purchase. Criteria should include anonymized data practices, real-time actionability, staffing coordination support, and compatibility with current access and communication infrastructure. Multi-site standardization, vendor responsiveness during live events, and measurable improvements in flow and guest experience should carry significant weight in selection decisions.
Given the speed of regulatory change, technology maturation, and venue-level adoption patterns, detailed segmentation data and customized scenario planning can materially improve investment and procurement decisions. The full research report provides deeper breakdown across solution types, application contexts, regional dynamics, and competitive moves, along with tailored guidance for specific business objectives. For decision-makers seeking to act on these trends with greater precision, the complete analysis offers the level of detail needed to translate market direction into execution.
For detailed analysis of this topic, please visit the official page: Crowd Management Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electronic Logbook Software Market: Why a 9.15% CAGR and Cloud Shift Reshape the Industry
By pmarketresearch, 2026-09-18
Electronic Logbook Software Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
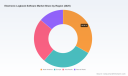
The electronic logbook software market has entered a phase of sustained expansion, driven by the convergence of digital transformation mandates and stringent operational compliance requirements. Starting from a valuation of USD 1,065.2 million in 2020, the market grew to USD 1,650.0 million by 2025, reflecting a compound annual growth rate of 9.15 percent. Projections indicate the market will surpass USD 3,000 million by 2032, underscoring the structural shift away from paper-based documentation toward integrated digital platforms. This trajectory is not merely a reflection of incremental technology adoption; it represents a fundamental re-architecture of how regulated industries capture, store, and audit operational records.
Despite the favorable growth outlook, the market faces several critical inflection points that will shape competitive outcomes over the next five years. First, legacy system integration remains a persistent barrier. Many industrial facilities and regulated manufacturers operate alongside decades-old operational technology and enterprise resource planning systems that were never designed to interoperate with modern cloud-native logbook solutions. The friction involved in migrating historical records, aligning data formats, and ensuring continuous uptime during transition periods creates hesitation among procurement teams, particularly in environments where downtime carries significant financial or safety consequences.
Second, the compliance burden continues to intensify rather than stabilize. Regulatory frameworks across pharmaceutical manufacturing, energy production, and transportation now demand real-time auditability, tamper-resistant record-keeping, and adherence to principles such as ALCOA+ and 21 CFR Part 11. Organizations that delay digitization expose themselves to inspection findings, including FDA Form 483 observations tied to documentation errors, while those that rush implementation without robust validation protocols risk introducing new compliance vulnerabilities. The tension between speed of adoption and rigor of validation is a defining challenge for the market.
Third, the market is undergoing a concentration dynamic that warrants attention. While the competitive field remains relatively fragmented, the top three players collectively account for approximately 22.45 percent of revenue, and the top five reach 34.12 percent. This distribution suggests that scale advantages are beginning to materialize for established vendors with broad deployment footprints, yet significant room remains for specialized entrants targeting niche compliance scenarios or vertical-specific workflows. Companies that fail to articulate a clear differentiation strategy risk being squeezed between enterprise-scale platforms and highly focused point solutions.
Key Drivers of Market Transformation
Technological Innovation and Data Integrity Architecture
The most immediate catalyst for adoption is the maturation of cloud-based architectures that natively embed compliance and traceability capabilities. Early electronic logbook solutions often functioned as digital replacements for clipboard entries, requiring manual validation and offering limited interoperability. Modern platforms, by contrast, are engineered as data integrity layers that automatically enforce electronic signature workflows, generate immutable audit trails, and align with regulatory expectations out of the box. This shift transforms the logbook from an administrative burden into a strategic asset for operational visibility.
Worldwide Meeting Minutes Software Market
Browser-based deployment models have accelerated this transition by reducing the technological barriers for field operators and shift supervisors. Solutions such as InfoLog 4.0 demonstrate how manufacturing and GMP environments can capture operator activity, task completion, and shift-handoff data without requiring specialized client installations. The removal of infrastructure overhead allows regulated facilities to scale adoption across multiple sites more rapidly, while also simplifying IT governance. Furthermore, the integration of drag-and-drop template customization enables organizations to align log structures with internal standard operating procedures without sacrificing compliance safeguards.
Regulatory Pressure and the Cost of Non-Compliance
Regulatory expectations have moved from periodic documentation reviews to continuous, inspection-ready readiness. In pharmaceutical and life sciences manufacturing, adherence to 21 CFR Part 11 for electronic records and signatures is now a baseline requirement, not a differentiator. The same is true for EU GMP Annex 11, which emphasizes traceability, system validation, and data integrity principles that effectively disqualify many paper-based processes from modern compliance standards. Organizations that continue to rely on manual logs face escalating risk, not only in the form of regulatory observations but also in operational inefficiencies tied to error correction, version control, and retrospective audit preparation.
The healthcare segment illustrates how regulation can spawn entirely new product categories within the broader logbook ecosystem. The recent launch of electronic narcotic log software targeting DEA compliance highlights how specialized regulatory demands create opportunities for vendors to build audit-ready, tamper-resistant tracking systems with inspection-ready reporting capabilities. This pattern is likely to repeat across other regulated domains where documentation precision carries legal and operational weight. On a broader geographic scale, national transport authorities such as Kenya's NTSA are phasing out paper logbooks in favor of centralized electronic systems, reinforcing the global direction toward digitized record-keeping as a regulatory default rather than an optional upgrade.
Demand-Side Shifts and Operational Resilience
Beyond compliance, end-user demand is being reshaped by the need for operational resilience and real-time situational awareness. Power and utilities operators, for example, increasingly depend on electronic rounding and maintenance logs to detect anomalies before they escalate into service disruptions. In industrial manufacturing, shift-to-shift communication gaps have historically led to duplicated efforts, missed handoff notes, and delayed incident response. Cloud-based logbook platforms that provide live dashboards, searchable history, and structured handoff protocols directly address these pain points, making them attractive not only to compliance officers but also to operations leaders focused on throughput and safety.
The end-user mix reflects this broadening value proposition. Industries with high regulatory density and complex operational workflows, including oil and gas, maritime operations, and chemical and pharmaceutical manufacturing, continue to anchor demand. At the same time, the addressable base is expanding as organizations in adjacent sectors recognize that digital log management can reduce error rates, shorten audit cycles, and improve cross-functional visibility. The result is a market where the value narrative has evolved from "replace paper" to "enable continuous operational intelligence."
Supply-Side Dynamics and Integration Economics
Supply-side factors are also influencing the pace of adoption. Cloud-based deployment now represents the dominant revenue stream, reflecting both buyer preference for lower upfront capital expenditure and vendor incentives to build recurring, subscription-oriented revenue models. This structural shift pressures vendors to continuously deliver feature updates, security enhancements, and integration connectors that justify ongoing subscription costs. At the same time, consolidation activity is beginning to reshape the supply landscape. Strategic acquisitions, such as the acquisition of Informetric Systems by Datacor, signal a move toward bundling electronic logbook capabilities with broader manufacturing intelligence and data aggregation platforms. For customers, this trend creates both opportunities and trade-offs: integrated platforms can reduce vendor fragmentation, but they may also limit flexibility for organizations that prefer best-of-breed components.
Cost structures are further affected by the growing expectation that logbook software should interoperate with existing enterprise systems rather than operate as a silo. Vendors that invest in open APIs, configurable data export pathways, and validation-ready documentation packages are better positioned to reduce the total cost of ownership for customers navigating complex IT environments. Conversely, solutions that require heavy customization or manual data reconciliation risk longer implementation timelines and higher hidden costs, which can slow procurement decisions in cost-conscious sectors.
Competitive Landscape and Strategic Positioning
The competitive field in the electronic logbook software market is defined by a blend of specialized compliance vendors, vertically focused platforms, and emerging entrants targeting niche regulatory scenarios. Incumbents have built defensible positions by aligning product architecture with the documentation standards most critical to their target segments. For example, vendors serving life sciences manufacturing emphasize data integrity, electronic signature compliance, and template flexibility to meet the expectations of quality assurance and regulatory affairs teams. Platforms built around drag-and-drop configuration and customizable templates reduce the friction of adapting log structures to site-specific procedures, which is often the difference between rapid adoption and prolonged pilot stagnation.
Other players have carved out advantages through secure, audit-ready log management designed for regulated environments that demand traceability and electronic signatures. These solutions typically focus on reducing the time and cost associated with audit preparation while ensuring that records withstand regulatory scrutiny. In industrial settings, cloud-based logbook tools aimed at shift work and operational awareness prioritize real-time communication, operator activity capture, and shift-to-shift continuity. This differentiation matters because the buying committee in industrial contexts often includes operations managers and plant supervisors who evaluate usability and workflow fit as heavily as compliance features.
A distinct competitive vector has emerged around highly specialized regulatory use cases. In healthcare, electronic narcotic log software built for DEA compliance illustrates how targeted functionality, real-time tracking, tamper-resistant audit trails, and inspection-ready reporting can create a strong value proposition in a narrow but high-stakes segment. Similarly, browser-based logbooks engineered for manufacturing and GMP environments have gained traction by addressing the practical needs of operator rounds, task tracking, and shift data capture without imposing heavy IT requirements. These focused approaches allow vendors to compete on depth rather than breadth, appealing to organizations that prioritize rapid compliance alignment over expansive feature sets.
Strategic positioning also increasingly depends on demonstration of real-world adoption and integration credibility. Customer transitions to electronic logging for operational data in utility environments, for instance, serve as reference points that validate the feasibility of deployment in live operational settings. When a regulated or public-utility organization moves from paper to digital logs, it signals to prospective buyers that the solution can handle the practical demands of day-to-day data capture while maintaining compliance integrity. Such adoption stories are becoming essential currency in a market where perceived implementation risk still slows many procurement decisions.
The market is evolving through a combination of consolidation, specialization, and selective new entry. Acquisition activity suggests that larger industrial intelligence and data management providers view electronic logbook capabilities as a natural extension of their platforms, particularly when log data can feed into broader analytics, validation, or manufacturing execution workflows. At the same time, the relatively fragmented share structure indicates that smaller, agile vendors can still win by solving a specific compliance or workflow problem exceptionally well. New entrants are likely to continue appearing where regulatory requirements are tightening faster than incumbent platforms can adapt, especially in segments where documentation precision carries direct legal or operational consequences. The most successful players will be those that balance compliance rigor with operational usability, while also building credible integration pathways that reduce long-term total cost of ownership.
Forward-Looking Trends and Strategic Implications
Over the next three to five years, the electronic logbook market is likely to be shaped by three interconnected trends. The first is the shift from standalone logbook tools toward integrated compliance and operational data platforms. As organizations accumulate structured log data across shifts, sites, and processes, the value of that data will increasingly be measured by its usefulness in downstream analytics, audit automation, and operational decision-making. Vendors that enable log data to flow securely into broader enterprise workflows will capture more sustained relevance than those that treat the logbook as an isolated repository.
Electronic Flight Bag Market
The second trend is the deepening of compliance-by-design as a market expectation rather than a premium feature. Regulatory scrutiny around electronic records, signatures, audit trails, and data integrity is not receding; it is becoming more prescriptive and more enforced across jurisdictions. Solutions that can demonstrate validation readiness, configurable control frameworks, and inspection-ready reporting will be preferred, especially in pharmaceutical, healthcare, and energy contexts where documentation failures carry disproportionate consequences. This trend will also accelerate geographic expansion where national authorities are mandating electronic systems, creating new demand waves that early movers can capture if they adapt to local regulatory nuances.
The third trend is the growing premium on usability and field-level adoption. A logbook platform can be fully compliant on paper yet fail in practice if operators find it cumbersome, slow, or disconnected from their daily routines. Interfaces that reduce data entry burden, support mobile and browser-based access, and provide clear handoff and search capabilities will differentiate in competitive evaluations. The commercial opportunity here lies in reducing the human friction that often undermines digitization initiatives, thereby improving data quality and adoption rates simultaneously.
Potential risks should not be underestimated. Implementation complexity in heterogeneous IT environments can delay value realization, particularly where legacy systems and heavy validation requirements coexist. Vendor consolidation may also create uncertainty for customers who value flexibility or who fear migration friction if platforms are deprecated or rebranded. Finally, regulatory divergence across regions and sectors can complicate global rollouts, requiring vendors and buyers alike to navigate differing expectations without sacrificing core data integrity principles. Organizations that approach these risks with disciplined vendor evaluation, phased deployment, and clear compliance mapping will be better positioned to convert market momentum into durable operational gains.
PW Consulting Information & Electronics Research Center
Actionable Recommendations for Decision-Makers
For manufacturers and regulated operators, the priority should be to evaluate electronic logbook solutions through a dual lens of compliance assurance and operational fit. Selection criteria must go beyond feature checklists to include validation support, integration pathways with existing enterprise systems, and evidence of field usability in environments similar to your own. A phased rollout that starts with high-impact use cases, such as operator rounds, shift handoffs, or audit-sensitive documentation, can reduce risk while building internal confidence in digital workflows.
For investors and strategic buyers, the market offers opportunities in vendors that combine credible compliance architecture with clear deployment economics and expanding integration capabilities. Particular attention should be paid to companies that have demonstrated real-world adoption in regulated settings, developed defensible positions in specialized compliance niches, or strengthened their platforms through acquisitions that add manufacturing intelligence or data aggregation functionality. Monitoring where consolidation is likely to occur can also reveal valuation signals and partnership possibilities before the broader market fully prices in those shifts.
For procurement and IT leaders, the focus should be on total cost of ownership rather than initial license or subscription pricing. Solutions that require extensive customization, manual reconciliation, or prolonged validation cycles can erode projected savings and extend time-to-value. Prioritizing platforms with configurable templates, robust audit-ready documentation, and transparent integration options will help ensure that logbook investments support both compliance objectives and broader operational efficiency goals. Businesses seeking detailed segmentation data, vendor scorecards, and tailored implementation pathways can gain further clarity by reviewing the full PW Consulting market research report, which provides a deeper breakdown of regional dynamics, deployment trends, and end-user adoption patterns.
For detailed analysis of this topic, please visit the official page: Electronic Logbook Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Digital Signage Design Services Market: How 7.5% CAGR Redefines Revenue Trajectories to 2032
By pmarketresearch, 2026-09-18
The Digital Signage Design Services Market: Navigating Growth Amid Structural Shifts
Market Overview and Core Challenges
The global digital signage design services market has demonstrated steady expansion over the past five years, growing from approximately $1.57 billion in 2020 to an estimated $2.25 billion in 2025. This trajectory reflects a compound annual growth rate of 7.5 percent, with forecasts projecting further acceleration through 2032 as organizations across sectors increasingly treat in-store and in-facility visual communication as a strategic capability rather than a decorative afterthought. The baseline revenue expansion, when mapped against evolving deployment patterns, points to a market that is maturing but far from saturated at the design and content layer. Hardware commoditization has lowered entry barriers for screen deployment, yet the value capture has progressively shifted toward creative strategy, motion design, interactive architecture, and content management integration—the very service components that determine whether a digital display resonates or simply occupies wall space.
Beneath these headline figures, three structural tensions are reshaping how service providers compete and how buyers evaluate formats. First, the industry is confronting a demographic and talent bottleneck in specialized design labor. A significant share of professional sign designers in developed markets is over fifty years old, intensifying talent scarcity and placing upward pressure on project costs and turnaround times. This demographic reality is colliding with demand for more sophisticated visual storytelling, interactive wayfinding, and multi-screen content orchestration, creating a supply-demand imbalance that favors firms with structured design operations or scalable creative outsourcing models.
Second, regulatory complexity is rising across wireless emissions, data privacy, workplace safety, and accessibility. Deployments that incorporate wireless components must navigate radio-frequency compliance, while interactive screens processing personal data face consent and minimization requirements under privacy frameworks. Workplace and public-facing displays are also subject to visibility and accessibility standards that influence both content placement and system architecture. These obligations are not merely legal checkboxes; they shape design workflows, content governance, and the commercial terms of service engagements, particularly for enterprises operating across multiple jurisdictions.
Third, the market is experiencing a functional split between commodity display installation and differentiated content design. As networks scale into hundreds or thousands of nodes, buyers increasingly expect design services to be tightly coupled with content strategy, template governance, and platform integration. Providers that only deliver visual assets without strategic planning or CMS alignment are seeing margin compression, while those that unify creative, technical, and operational capabilities are capturing more durable engagements. The challenge for decision-makers is distinguishing between providers that can produce compelling visuals and those that can sustain brand consistency, compliance, and performance across entire screen estates.
Key Drivers Shaping Market Dynamics
Technological Innovation and Content Sophistication
A defining driver of current growth is the convergence of advanced display technologies with more capable content creation and management workflows. LED formats, high-brightness outdoor panels, touch-enabled interfaces, and cloud-based CMS platforms have expanded the creative palette, but the real commercial impact comes from how design services translate these capabilities into coherent visual experiences. Providers are increasingly expected to deliver motion graphics, templated content kits, and interactive wayfinding that can be updated at scale without losing brand integrity. The ability to design once and deploy consistently across multiple locations has become a decisive competitive dimension, especially for retail chains, hospitality groups, and large corporate campuses.
Recent industry activity underscores this shift toward design-plus-management offerings. In early 2026, a major retail operator implemented a platform to control digital signage screens across more than 900 stores, integrating content design and centralized management into a single operational workflow. This kind of deployment signals that buyers are no longer purchasing isolated design projects; they are investing in repeatable content systems that reduce localized production burden while maintaining visual quality. As creative teams adopt more modular design approaches—templates, motion libraries, localized variants—the service market is being reshaped around scalability, governance, and rapid iteration rather than one-off bespoke production.
Policy and Regulatory Influence on Design Practice
Regulatory expectations are becoming embedded into design processes rather than treated as post-deployment contingencies. Wireless connectivity requirements, privacy obligations for interactive kiosks, workplace visibility standards, and accessibility guidelines all influence how content is structured, where screens are positioned, and what data flows are permissible. For international operators, the challenge is multiplied by uneven regulatory expectations across regions, which can affect template design, consent mechanisms, and compliance documentation.
This environment favors providers that build compliance into the design stage. Firms that offer ADA-aligned visual considerations, privacy-aware interactive design, and documentation supporting workplace safety visibility can reduce retrofit risk for clients and create stronger differentiation. At the same time, regulatory attention raises the importance of content governance: who can update what, how personalization is handled, and how audit trails are maintained. Design services are therefore evolving from aesthetic production toward governed visual communication systems, a transition that expands the scope of professional engagements and raises the strategic stakes for buyers selecting partners.
Demand-Side Shifts in Consumer and Enterprise Behavior
End-user expectations are a powerful force behind service demand. In retail and hospitality, customers increasingly expect dynamic, context-aware visuals that support navigation, promotions, and experience design. In corporate and education environments, digital displays serve internal communication, wayfinding, and brand reinforcement functions that must feel consistent with broader identity systems. Healthcare and transportation settings add another layer of complexity, where clarity, accessibility, and real-time information accuracy can directly affect user experience and operational outcomes.
PW Consulting Information & Electronics Research Center
These demand patterns are pushing buyers toward service models that combine strategy, visual design, and platform integration. A display without a content plan tends to underperform, while a well-orchestrated visual system can improve engagement, reduce staff workload, and support localized messaging at scale. The commercial implication is clear: design services are being evaluated less on isolated creative quality and more on their contribution to operational efficiency, brand consistency, and user experience across multiple touchpoints. This is why enterprises are gravitating toward providers with in-house creative teams, reusable content structures, and proven deployment track records.
Supply-Side and Cost Structure Considerations
On the supply side, the maturation of fabrication networks, installation capabilities, and outsourced design models is altering cost structures and delivery models. Large national networks can bundle design, production, and installation, while specialized outsourcing firms offer flexibility for concept development, LED layout planning, and compliance-oriented signage solutions. This combination expands access to design capacity but also increases the importance of vendor management, quality control, and coordination between creative and technical teams.
Labor scarcity and demographic concentration in the design workforce add another layer of cost pressure. As experienced designers retire and demand rises for more complex interactive and multi-screen work, firms that can institutionalize design assets, build reusable libraries, and integrate production with clear technical specifications are better positioned to manage cost and turnaround. For buyers, this means total project economics increasingly depend on how well design services are structured for repeatability and how effectively providers balance creative quality with operational discipline.
Worldwide Product Design Service Market
Competitive Landscape and Leading Strategies
The competitive field is populated by organizations with distinct strategic anchors. Some providers compete through end-to-end capability, pairing in-house creative teams with installation and management services to deliver branded visual experiences across retail and hospitality environments. Others emphasize software-enabled visual communication with dedicated design support, offering custom signage designs, content kits, templates, and interactive wayfinding for enterprise clients. A further cluster of players operates as national or regional production networks, specializing in custom design, fabrication, and installation for menus, directories, promotions, and dynamic displays. Alongside these, architectural and urban integration specialists focus on landmark-scale experiences, while outsourced design firms provide concept development, LED layouts, and compliance-aware signage solutions.
This diversity produces clear differentiation paths. End-to-end providers gain advantage from integrated delivery, where creative, technical, and operational responsibilities are coordinated under one relationship, reducing fragmentation for multi-site clients. Software-centric players leverage repeatable content structures and enterprise visual communication expertise, making them attractive to organizations that need governance across many screens. Production networks differentiate through scale, localized execution, and speed to install, which matters for time-sensitive rollouts or distributed locations. Architectural integrators command premium positioning by linking digital displays to physical environments and experiential design, a niche that can be highly valuable for landmark projects but less applicable to broad-based deployments.
The market is evolving through both consolidation and specialization. Larger operators are expanding service portfolios and partnership networks to cover more of the value chain, while niche specialists deepen expertise in areas such as interactive design, accessibility, or outdoor durability. At the same time, recent partnership activity shows how installation-focused players are layering in custom design integration to strengthen their offerings. For example, a major signage network partnered to support digital signage installations in hospital environments with tailored design integration, illustrating how healthcare deployments are pushing providers to combine technical reliability with context-sensitive creative work.
Strategic positioning is increasingly defined by three questions: can the provider unify design strategy with content management, can it scale creative output without losing consistency, and can it navigate regulatory and accessibility requirements as part of the design process? Firms that answer these convincingly are building moats around recurring content operations rather than one-off projects. Buyers, in turn, are rewarded for selecting partners based on delivery discipline, content governance, and the ability to adapt creative assets across locations and use cases.
Forward-Looking Trends for the Next Three to Five Years
Design-as-a-System Becomes the Standard
Over the next several years, design services are likely to be judged increasingly on systemization rather than isolated creative output. Expect broader adoption of templated motion libraries, localized content variants, and governance frameworks that let enterprises update large screen networks efficiently. This trend will create opportunities for providers that can deliver modular design assets, clear style rules, and integration with CMS platforms, while also increasing the value of partners who can train internal teams and manage content workflows over time.
Interactive and Data-Rich Experiences Will Expand, With Guardrails
Interactive wayfinding, touch-enabled directories, and personalization-enabled displays will continue to grow in high-traffic and service-oriented environments. However, privacy expectations and compliance requirements will shape how these experiences are designed, particularly where personal data is processed. The commercial opportunity lies in building interactive experiences that are compelling without over-collecting data, supported by consent design and transparent data handling. Providers that can balance engagement with compliance will be better positioned for enterprise and public-sector work.
Integration with Physical Environments and Multi-Channel Identity Will Deepen
Digital signage will increasingly be treated as part of a broader environmental and brand identity system, not a standalone medium. Architectural integration, lighting considerations, and coordination with broader communication channels will matter more as deployments seek to reinforce cohesive experiences across spaces. This creates opportunities for specialists who can bridge design, physical installation, and operational planning, but it also raises execution risk where coordination is weak. Projects that treat design, installation, and content management as separable silos are likely to face more rework, inconsistent results, and slower time to value.
Potential risks include talent constraints that slow creative delivery, regulatory changes that add compliance overhead, and price competition in commoditizing segments that pressure margins. Market participants that depend heavily on manual, bespoke workflows may find it harder to scale, while those that invest in reusable assets, structured processes, and integration-ready design will be better equipped to manage volatility.
Strategic Implications for Decision-Makers
For enterprises evaluating digital signage design services, the priority is to define the engagement around content systems rather than individual displays. This means specifying how strategy, visual design, localization, accessibility, and CMS integration will work together before scoping individual projects. Buyers should assess providers on repeatability, governance, and the ability to maintain brand consistency across multiple locations, not only on creative quality in isolation.
For investors and strategic planners, the most durable value appears to be linked to providers that combine creative capability with operational scale and integration-ready workflows. Businesses that can institutionalize design assets, support compliance-by-design practices, and deliver content across distributed networks are more likely to secure recurring engagements. Market observers should watch for consolidation among service providers, deeper partnerships between fabrication/installation networks and creative teams, and growing demand for interactive experiences that meet privacy and accessibility expectations.
For manufacturers and technology suppliers, the opportunity is to support design-led deployments with tools and specifications that make content creation, management, and compliance easier. Clearer technical standards, interoperability with common CMS platforms, and guidance on accessibility and visibility can help reduce friction between creative teams and installation operations. In a market where screens are increasingly commoditized, the differentiator is often how smoothly the surrounding design and management ecosystem functions.
Digital Signage Market
For all of these audiences, the strategic value lies in understanding where the market is heading before committing to large-scale deployments or partnership decisions. Detailed segmentation data, regional dynamics, end-user patterns, and provider-level benchmarks can sharpen planning significantly, especially when aligning investment or procurement choices with the likely trajectory of the market through the end of the decade and into the early 2030s.
For detailed analysis of this topic, please visit the official page: Digital Signage Design Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Commercial Encryption Products Market: Why 13.5% CAGR and 15B Scale Redefine Security Strategy by 2032
By pmarketresearch, 2026-09-18
The Commercial Encryption Products Market: Strategic Trends and Commercial Opportunities
The commercial encryption products market has evolved from a niche cybersecurity concern into a foundational layer of digital infrastructure. By 2025, the market has reached an estimated 6.5 billion USD in revenue, with consistent compound annual growth of 13.5 percent projected through 2032. Over the five-year historical window from 2020 to 2025, revenue expanded by nearly 87 percent, reflecting a structural shift rather than a temporary surge. The trajectory ahead points to continued acceleration, with forecasts suggesting the market will exceed 15.7 billion USD by the end of the forecast period. This growth is not evenly distributed across product types or sectors, but the overall magnitude signals that encryption has moved from compliance-driven procurement to strategic investment.
Several characteristics define the current market landscape. The ecosystem remains moderately concentrated, with the top three players capturing roughly a third of total revenue and the top five accounting for just under 43 percent. This concentration leaves substantial room for specialization, regional differentiation, and niche innovation, particularly in segments where performance, assurance, and integration matter more than price. At the same time, the market faces a pivot point driven by certification transitions, quantum readiness expectations, and the growing mismatch between legacy architectures and cloud-native workloads.
Hardware Encryption Devices Market
Key Challenges and Inflection Points
One of the most consequential challenges is the regulatory transition from FIPS 140-2 to FIPS 140-3. The formal move of FIPS 140-2 certificates to a historical list in September 2026 forces commercial encryption products and the systems that embed them to adopt validated modules under the newer standard. For vendors, this is not a simple recertification exercise; it requires re-architecting validation footprints, aligning engineering roadmaps, and addressing procurement cycles that may stall until compliance is confirmed. For buyers, the risk is procurement inertia: legacy deployments that were once acceptable may face audit exposure or sourcing constraints, while new projects must specify FIPS 140-3 from the outset.
A second inflection point is the post-quantum cryptography transition. NIST finalized post-quantum standards in 2024, and CISA published product categories to support adoption in commercial technologies in early 2026. The market is not yet in full implementation mode, but the direction of travel is clear: organizations are beginning to inventory cryptographic dependencies, assess migration paths, and evaluate vendor roadmaps. The challenge is twofold. First, the technical complexity of hybrid deployments and crypto-agility introduces integration risk. Second, the absence of mature commercial tooling and testing frameworks means early movers must navigate uncertainty around interoperability, performance, and total cost of ownership.
A third challenge lies in workload dispersion. Encryption is no longer confined to perimeter networks or on-premises storage. Data protection requirements now span distributed cloud environments, hybrid identity architectures, edge devices, and payment ecosystems that must balance assurance with latency and throughput. Suppliers that cannot offer scalable key management, integration with cloud services, and modular assurance profiles will find themselves squeezed by both performance requirements and procurement expectations. The markets leading players are responding with certification breadth, cloud-optimized hardware, and software-centric data protection, but the structural tension between assurance depth and deployment agility remains unresolved.
Key Drivers Shaping Market Momentum
Market growth is being propelled by a convergence of technical, regulatory, and demand-side forces. The most visible driver is cryptographic assurance modernization. The shift toward FIPS 140-3 and the emergence of post-quantum standards are reshaping specification language and procurement requirements. Recent vendor activity makes this acceleration tangible. Utimaco achieved FIPS 140-3 Level 3 certification for its u.trust GP HSM Se-Series in May 2026, positioning the company as the only vendor with full FIPS 140-3 coverage across general-purpose and payment HSM portfolios. In December 2025, Thales secured NATO Secret classification for its Luna Network HSM 7 alongside FIPS 140-3 Level 3 validation. These milestones illustrate how high-assurance certification is becoming a competitive differentiator, especially in environments where data sensitivity spans commercial, government, and defense-adjacent use cases.
Demand-side behavior is changing in parallel. Enterprise data protection strategies are shifting from perimeter-based controls to pervasive, identity-aware encryption integrated with broader data security platforms. Regulatory exposure in financial services, healthcare, and public-sector operations continues to raise the baseline for key management and data-at-rest protection. At the same time, business leaders are pressing for faster deployment cycles, cloud-native integration, and reduced operational friction. The result is a market that values not only cryptographic strength but also manageability. Certification becomes a proxy for trust, and trust becomes a procurement gate.
Supply-side dynamics are increasingly shaped by cloud adoption and partnership models. Hardware security modules are no longer treated as standalone appliances in every context. Cloud-optimized HSM families are being selected to support managed cloud HSM services, extending encryption capabilities into elastic environments while maintaining key isolation. Marvell's LiquidSecurity HSM family, chosen by Microsoft for Azure Cloud HSM services in August 2025, reflects this pattern. The broader implication is that encryption infrastructure is being embedded into platform ecosystems, not simply layered as an independent product. For commercial encryption providers, this opens opportunities in integration design, attestation, and managed key services, but it also requires tighter alignment with cloud vendor roadmaps and operational expectations.
Emerging Influences Across the Ecosystem
Three additional dynamics are reinforcing these drivers. First, crypto-agility is moving from a technical aspiration to a procurement criterion. Buyers are increasingly interested in architectures that can adapt to evolving algorithms without wholesale replacement, especially as post-quantum migrations are planned. Second, product certification breadth is expanding beyond traditional enterprise and financial use cases into IoT and connectivity domains. The April 2026 announcement of FIPS 140-3 validation for cryptographic modules on Digi Accelerated Linux-based IoT and connectivity solutions signals that assurance requirements are reaching edge and embedded environments where security has historically been harder to standardize. Third, geopolitical and sector-specific assurance needs are creating differentiated demand. Classification achievements such as NATO Secret for select HSM products illustrate that high-assurance commercial encryption can unlock adjacent markets where data sensitivity and supply-chain trust are paramount.
PW Consulting Information & Electronics Research Center
Together, these drivers are pushing the market toward a more layered structure: certified hardware for high-assurance root operations, software and platform capabilities for data protection and key lifecycle management, and cloud-integrated services for scalability. Growth will be determined not only by how many organizations buy encryption products, but by how many can absorb them into workflows without compromising performance, compliance, or operational continuity.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a handful of established players with strong certification portfolios and a growing emphasis on integration with enterprise and cloud ecosystems. Thales Group maintains a broad commercial encryption and key management position through Luna Network HSMs, payShield payment HSMs, and CipherTrust data security solutions, with recent validation activity reinforcing its high-assurance credentials. Utimaco has concentrated on full-portfolio FIPS 140-3 coverage across general-purpose and payment HSMs, a differentiating posture in markets where procurement teams want a single, consistently validated vendor footprint. Entrust continues to anchor its commercial position in nShield HSMs for key protection, code signing, and enterprise encryption, appealing to organizations that value high-assurance key use cases within broader identity and data protection strategies.
Homomorphic Encryption Market
Futurex occupies a manufacturing-centric positioning with FIPS 140-2 Level 3 and PCI HSM validated products produced in the United States, an advantage in contexts where supply-chain provenance and domestic manufacturing are evaluation factors. IBM brings encryption software, Guardium data protection, and HSM offerings into the enterprise commercial data protection conversation, leveraging platform adjacencies and data security integration. Microsoft competes in a different layer of the stack, with Azure Key Vault and encryption services that incorporate HSM-backed key management for cloud data protection, effectively embedding encryption into a broader cloud platform. Marvell contributes cloud-optimized HSMs, notably through its selection for Azure Cloud HSM services, aligning hardware capability with hyperscale deployment requirements.
Strategic Positioning and Differentiation
Across these players, differentiation is emerging along several axes. Certification scope is one of the most visible. Vendors that can demonstrate consistent FIPS 140-3 validation, payment HSM validation, or elevated classification may secure preference in regulated environments where audit confidence is directly tied to specification language. Product breadth is another axis: players offering both general-purpose and payment HSMs, or hardware combined with software data protection, can address multiple procurement categories within a single relationship. Integration capability is becoming equally important. The ability to connect key management to cloud services, enterprise identity, and data security platforms reduces operational friction and strengthens the value proposition beyond raw cryptographic assurance.
Manufacturing origin and supply-chain narrative also matter in specific segments. Domestic manufacturing, transparent validation histories, and clear product category alignment can influence procurement decisions in government-adjacent, critical infrastructure, and payment environments. At the same time, cloud-native deployments are rewarding providers that can offer modular, scalable hardware or managed services that fit into elastic architectures rather than rigid appliance models.
Structural Evolution in the Market
The market is likely to evolve through both consolidation and niche differentiation. Larger platforms with broad data security, identity, and cloud ecosystems may expand their encryption footprint through product integration or selected partnerships. At the same time, specialized vendors with focused certification portfolios, strong payment or HSM credentials, and clear supply-chain value can thrive by serving high-assurance segments that are less price-elastic. New entrants are unlikely to displace incumbents through pure scale, but they may carve out positions in specific use cases such as cloud-optimized key services, modular assurance for hybrid deployments, or crypto-agility tooling that simplifies transition planning. The real contest will be over specification influence: vendors that help buyers translate compliance requirements into operational architectures will shape demand more than those that compete solely on feature parity.
Future Trends to Watch
Over the next three to five years, three trends are likely to shape the commercial encryption market most directly. First, FIPS 140-3 compliance will become a default procurement baseline rather than a differentiator, and the competitive advantage will shift toward breadth, speed of validation, and the ability to support hybrid and cloud-native deployments. Vendors with completed portfolios and clear migration support will gain preference in regulated sectors, while late movers risk exclusion from specification lists.
Second, post-quantum readiness will move from policy direction to operational planning. Migration inventories, crypto-agility architectures, and hybrid key management approaches will increasingly appear in enterprise and public-sector roadmaps. Commercial opportunity will emerge for providers that can simplify transition paths, support hybrid modes, and offer clear documentation and testing for algorithm flexibility. The associated risk is fragmentation: without common deployment patterns or interoperability expectations, early implementations may require expensive integration work and create vendor lock-in concerns.
Third, encryption will continue to converge with platform services. Managed cloud HSM, integrated key protection, and data security platforms will become the primary consumption model for a growing share of commercial workloads. This trend favors players that can embed security into workflows and reduce operational overhead, but it also raises questions about long-term control of cryptographic assets, audit visibility, and portability across environments. The opportunity lies in architectures that preserve assurance while making protection easier to consume; the risk lies in over-reliance on opaque or tightly coupled services that complicate governance.
Strategic Actions for Decision-Makers
For manufacturers and product vendors, the near-term priority is to align certification roadmaps with procurement reality. Completing FIPS 140-3 validation, clarifying payment and general-purpose coverage, and communicating migration support can influence specification outcomes in regulated demand channels. Vendors should also invest in integration and cloud compatibility, because assurance alone is unlikely to win deals where operational fit is weak. Differentiation should be expressed through portfolio consistency, deployment flexibility, and clear guidance for post-quantum transition planning.
For investors and strategic partners, the most informative signals are certification milestones, ecosystem partnerships, and evidence of adoption in cloud or platform services. Companies that combine validated hardware with usable key management and data protection integration are better positioned to capture recurring commercial demand than those competing primarily on price. Portfolio exposure should be assessed not only by product footprint but by the ability to serve regulated, high-assurance, and cloud-scale segments simultaneously.
For procurement and security leaders, the practical move is to treat encryption as a lifecycle decision rather than a point purchase. Early specification of FIPS 140-3 requirements, evaluation of crypto-agility options, and review of vendor support for post-quantum transition planning will reduce downstream risk. Buyers should also assess integration fit with existing cloud, identity, and data security environments to avoid new operational bottlenecks. Where demand is complex or region-specific, detailed segment intelligence can shorten evaluation cycles and improve specification accuracy. The broader market dynamics, segment differentiation, and vendor-level developments can be explored in depth through a complete market study that provides the detailed segmentation, competitive tracking, and scenario-based guidance needed for tailored planning.
For detailed analysis of this topic, please visit the official page: Commercial Encryption Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Educational and Training Software Market: Why 15.12% CAGR Reshapes Strategy
By pmarketresearch, 2026-09-18
Navigating the EdTech Inflection Point: Strategic Trends in the Educational and Training Software Market
Market Landscape and Core Challenges
The global educational and training software market has firmly entered a phase of accelerated expansion. Revenue climbed from approximately 175.4 billion USD in 2020 to 355.6 billion USD by 2025, reflecting sustained institutional adoption and shifting learning paradigms. Projections indicate the market will continue compounding at a 15.12 percent CAGR through 2032, reaching an estimated 952.84 billion USD. This trajectory is not merely a post-pandemic normalization but a structural reallocation of how organizations invest in knowledge delivery, skill development, and academic infrastructure.
Cloud-based deployment has become the dominant architecture, reflecting broader enterprise preferences for scalability, remote accessibility, and reduced on-premise maintenance overhead. The sector is broadly distributed across K-12 education, higher education, and corporate training, with each segment driving distinct procurement cycles, compliance requirements, and user experience expectations. In terms of application, learning management systems, student information systems, assessment and testing software, and content creation and simulation tools occupy significant portions of the value chain. Geographic adoption remains led by North America, followed by Europe and Asia Pacific, while Latin America and the Middle East and Africa represent faster-growing but still earlier-stage commercialization environments.
Despite this momentum, the market faces three structural challenges that will shape competitive outcomes over the next decade. First, integration fragmentation continues to burden end users. Institutions and enterprises frequently operate disjointed platforms for administration, instruction, assessment, and corporate skill tracking. Without interoperable data standards, organizations struggle to create unified learner profiles, measure continuous competency development, or automate cross-platform workflows. This friction raises total cost of ownership and slows the realization of analytics-driven decision making.
Second, data privacy and AI governance are becoming decisive procurement filters. Educational software now routinely processes sensitive demographic, performance, and behavioral data. Simultaneously, generative AI capabilities are embedded into tutoring, assessment design, content summarization, and administrative automation. Buyers are increasingly scrutinizing model transparency, data retention practices, bias mitigation, and compliance with emerging regulatory frameworks. Vendors that cannot articulate clear governance positions risk exclusion from RFPs, particularly in public sector and higher education procurement.
Third, the market is reaching a saturation inflection in mature segments. Base-level learning management and content delivery tools are becoming table stakes, pressuring vendors to differentiate through outcomes rather than feature lists. Buyers are asking harder questions about whether platforms demonstrably improve completion rates, skill transfer, instructor efficiency, or workforce readiness. This shift rewards vendors that can connect software deployment to measurable organizational impact, while exposing those that rely on perception-based marketing or fragmented point solutions.
For executives and investors, the implication is clear. Growth alone will not guarantee durable advantage. The winners will be organizations that navigate interoperability demands, embed responsible AI into product design, and prove value through outcome metrics rather than platform breadth alone.
Key Drivers Reshaping Demand and Value Creation
Four interconnected forces are driving the market’s next phase of expansion, each reshaping how software is designed, sold, and valued.
Technology Innovation and AI-Infused Learning Workflows
Generative AI has moved from experimental feature to core product architecture. Platforms are now integrating AI-assisted lesson planning, adaptive tutoring, automated rubric generation, multilingual content localization, and intelligent summarization of dense learning materials. These capabilities reduce the manual workload of educators and corporate trainers while enabling more personalized learning paths at scale. The shift is most visible in tools that support test preparation, workplace compliance training, and skills-based upskilling, where rapid content iteration and individualized pacing create tangible efficiency gains.
Equally important is the move toward AI-supported instruction rather than AI replacement. Educational institutions and employers are exploring tools that augment human facilitation, provide real-time feedback, and help managers identify skill gaps earlier in the learning journey. This balanced positioning is becoming a design principle for platforms seeking wide adoption across risk-averse and pedagogy-sensitive environments.
Policy, Regulation, and Institutional Standardization
Regulatory and policy environments are increasingly shaping procurement behavior. Public agencies and multilateral organizations are publishing guidance on responsible AI use in education, emphasizing transparency, age-appropriate design, and safeguards around student data. In parallel, regional frameworks are beginning to classify certain AI applications as higher-risk, particularly where biometric or emotion-recognition technologies intersect with learning environments. These developments do not slow adoption outright, but they do raise the bar for compliance, documentation, and vendor accountability.
At the same time, policy-driven workforce initiatives are expanding demand for accessible training tools. Government-backed literacy and AI readiness programs are surfacing as new adoption channels, especially when delivered through lightweight, mobile-friendly, or text-based formats that can reach workers outside traditional classroom settings. Such initiatives create downstream demand for content authoring, assessment, and tracking capabilities that can plug into broader skills infrastructure.
Demand-Side Shifts in Learning Behavior and Workforce Expectations
Learner expectations are changing faster than many legacy platforms can accommodate. Students, professionals, and managers increasingly expect seamless mobile experiences, modular microlearning, and visible connections between training and career progression. In corporate environments, learning is no longer treated as a separate HR function but as part of continuous performance enablement. This is driving demand for platforms that connect learning activity to role readiness, internal mobility, and compliance tracking.
In academic settings, there is growing emphasis on hybrid instruction models, credit-bearing digital credentials, and tools that reduce administrative load without compromising instructional quality. The line between formal education and professional training is blurring, encouraging platforms that can serve both contexts with consistent identity, assessment, and reporting experiences.
Education Software Market
Cost Structure and Deployment Economics
Economic pressures are reinforcing cloud-first adoption while also changing how organizations justify software spend. Budget holders want platforms that lower IT maintenance burdens, scale across campuses or enterprise units, and reduce content production costs through reusable templates, automated localization, and AI-assisted authoring. The economics of content creation are especially relevant in fast-moving technical fields where courseware can become outdated quickly. Vendors that shorten content update cycles and enable non-specialist staff to maintain materials are gaining an operational advantage.
At the same time, the cost of switching is rising as programs deepen their dependency on integrated ecosystems. Once a platform becomes the system of record for enrollment, assessment, or compliance, migration becomes politically and operationally difficult. This dynamic is strengthening retention for incumbents with broad deployment footprints, while making it harder for new entrants to displace established workflows without a clearly superior value proposition.
Competitive Landscape and Leading Strategies
The market remains comparatively fragmented at the top, with no single vendor holding dominant share. Industry concentration is moderate, with the top three players accounting for roughly 19.45 percent of revenue and the top five reaching about 29.8 percent. This structure leaves substantial room for differentiation, niche specialization, and regional expansion, but it also intensifies pressure on vendors to define a sharp strategic position rather than compete across every segment simultaneously.
Customer Support Training Software Market
Several strategic archetypes are emerging among leading players. Broad online learning platforms continue to scale by pairing content breadth with credentialing and professional signaling. Their advantage lies in audience reach, employer partnerships, and the ability to connect learning to career outcomes. Gamified and mobile-first learning apps occupy a different position, using engagement mechanics to lower barriers to entry and expand into adjacent subjects beyond their original focus. Their growth increasingly depends on converting casual users into sustained learning habits and leveraging platform ecosystems for cross-subject expansion.
Learning management system providers remain central to institutional adoption, competing on usability, integration depth, and support for diverse teaching and training models. Their differentiation often comes from how well they serve blended environments, simplify instructor workflows, and connect with student information or assessment systems. In parallel, corporate and skills-focused platforms compete on personalized learning paths, compliance coverage, leadership development, and technology skills curricula. These vendors are positioning learning as an operational capability rather than a one-off training event.
Large technology providers are layering educational capabilities onto existing productivity and cloud ecosystems. Their strategy typically emphasizes AI-enabled tools, identity and collaboration infrastructure, and low-friction adoption through familiar interfaces. By embedding learning assistance, content summarization, and classroom or workforce support tools into broader software environments, they aim to reduce switching costs and increase platform stickiness. Eu-based and multi-regional regulatory considerations are also shaping how these providers design data handling and AI features for education use cases.
Recent product and program activity illustrates how quickly the landscape is evolving. Major providers have launched educator-focused programs that bundle AI-supported teaching tools, content creation features, and improved access controls for instructional workflows. Other vendors have expanded personalized learning journeys and acquired AI content capabilities to speed creation and adaptation of training materials. In parallel, public-sector workforce initiatives are pairing free AI literacy resources with accessible delivery formats, expanding the reach of digital training beyond traditional buyers. The OECD’s recent exploration of generative AI design principles in education further underscores the growing expectation that learning tools should be effective, transparent, and context-aware.
The competitive trend points toward both consolidation and specialization. Larger platforms are likely to pursue integrations that cover identity, content, assessment, analytics, and administrative workflows in a more unified stack. At the same time, specialized providers will continue to thrive by solving narrow problems exceptionally well, such as high-stakes assessment, simulation-based training, language acquisition, or compliance-heavy corporate programs. New entrants are most likely to succeed where they can address underserved segments, offer superior UX for specific user groups, or provide interoperable tools that reduce integration burdens for existing ecosystems.
Future Trends and Commercial Opportunities
Over the next three to five years, three trends are likely to define where value concentrates. First, AI will become a standard layer across learning workflows, but differentiation will shift from “having AI” to “using AI responsibly and effectively.” Platforms that demonstrate measurable improvements in instructor efficiency, learner completion, and assessment quality will command stronger positioning than those that merely showcase automation features. Commercial opportunities will arise for vendors that can package AI capabilities as trustworthy, auditable, and aligned with institutional governance requirements.
Second, interoperability and unified learner data will become strategic purchasing criteria. Buyers will increasingly favor solutions that can exchange data cleanly across administrative, instructional, and workforce systems. This creates openings for middleware, analytics layers, and platforms designed with open integration as a core architectural choice. Companies that reduce the integration tax for schools, universities, and enterprises will be better placed to expand within accounts and cross-sell adjacent modules.
Third, the boundary between education and workforce training will keep eroding, especially in skills-based hiring and internal mobility programs. Organizations will look for tools that support continuous credentialing, competency mapping, and scenario-based simulation. This trend favors platforms that can serve both academic and corporate audiences with adaptable content models and reporting frameworks. There is also opportunity in lightweight, high-reach training formats that support large-scale literacy and upskilling initiatives, especially where accessibility and low friction matter more than feature density.
Risks remain significant. Regulatory uncertainty around AI in education could alter procurement requirements or limit certain use cases, particularly where sensitive data or high-stakes decisions are involved. Overreliance on automation may trigger pushback if learners or instructors perceive quality degradation or excessive surveillance. Macroeconomic pressure could also compress discretionary budgets, making outcome proof and total cost of ownership more important than novelty. Vendors and buyers alike will need to balance innovation with governance, integration, and measurable impact.
Strategic Actions for Decision-Makers
For platform builders and product leaders, the priority is to design for interoperability and governance from the start. Products should make it easy to exchange learner data, support modular content creation, and provide transparent controls for AI-assisted features. Differentiation should be anchored in workflows that reduce instructor or administrator burden while improving learning outcomes, not simply in the presence of advanced features.
For investors, due diligence should focus on retention economics, integration depth, and evidence of outcome-based value. The most durable opportunities are likely to sit in segments where software becomes embedded in daily operations, compliance, or credentialing, rather than in discretionary point tools. It is also important to assess how prepared portfolio companies are for evolving AI regulation and data-handling expectations, since these factors will increasingly influence procurement velocity.
For procurement and strategy teams, selection criteria should expand beyond feature checklists. Evaluations should include data portability, integration effort, AI governance documentation, and the vendor’s ability to demonstrate measurable improvements in efficiency or learner performance. Pilots should be structured to test whether a platform can reduce administrative load, support personalized learning or training paths, and fit within broader systems already in use.
Given the speed of product launches, regulatory updates, and adoption shifts across regions and sectors, high-level market narratives are no longer sufficient for planning. Decision-makers benefit from detailed segmentation data, company-level benchmarking, and scenario analysis that connects technology roadmaps with procurement realities. Those seeking a fuller view of segmentation dynamics, regional demand patterns, and vendor positioning can use the complete PW Consulting market research report to inform investment, product, and procurement decisions with greater precision.
PW Consulting Information & Electronics Research Center
For detailed analysis of this topic, please visit the official page: Educational and Training Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
8-bit Automotive MCU Market: The 2026–2034 Growth and Concentration Dynamics
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the 8-bit Automotive Microcontrollers Market
Market Landscape and Core Challenges
The 8-bit automotive microcontroller market represents a stable yet evolving segment within the broader automotive electronics ecosystem. Valued at $850.0 million in 2025, the market has demonstrated resilience, growing from $810.0 million in 2023. The trajectory projects a steady climb to approximately $1010.38 million by 2032, reflecting a compound annual growth rate (CAGR) of 2.5 percent over the forecast period from 2026 to 2032.
IoT Microcontroller (MCU) Market
This growth trajectory underscores a specific market dynamic: 8-bit architectures are not being displaced by higher-bit alternatives but are instead maintaining a critical niche. The market remains highly concentrated, with the top three companies commanding 68.5 percent of revenue, while the top five control 82.4 percent. This consolidation indicates high barriers to entry and established trust relationships between semiconductor suppliers and automotive OEMs.
Despite the steady numbers, the industry faces significant inflection points. The primary challenge lies in the tension between legacy reliability and modern functional requirements. As vehicles incorporate more complex electronic control units (ECUs), the expectation for 8-bit devices to interface with advanced networks while maintaining cost efficiency creates architectural pressure. Manufacturers must balance the proven stability of 8-bit cores with the need for enhanced security and processing capabilities.
Secondly, supply chain normalization following previous volatility is beneficial, but geopolitical factors are reshaping production footprints. There is increasing momentum toward localizing automotive MCU production, including 8-bit variants, within Asia to serve regional OEM supply chains. This shift requires existing players to adapt their manufacturing strategies to remain competitive in localized markets while managing global cost structures.
Finally, qualification standards remain a rigid gatekeeper. The requirement for AEC-Q100 Grade 0 qualification, ensuring operation from -40°C to 150°C, and ISO 26262 functional safety compliance for ASIL B applications sets a high bar for component selection. Any disruption in meeting these standards can disqualify a supplier from new design wins, making compliance a non-negotiable strategic priority.
Key Drivers of Market Dynamics
Several core factors are propelling the demand and evolution of 8-bit automotive MCUs. Understanding these drivers is essential for stakeholders looking to navigate the market effectively.
Technological Innovation and Integration
Innovation in 8-bit MCUs is focusing on integration rather than raw processing power. Modern automotive applications require devices to handle multiple functions within a single chip to save space and cost. Recent developments highlight this trend, such as the continued active support and availability of STM8AF/STM8AL automotive series with enhanced packages and ecosystem tools. These updates provide designers with greater flexibility in board layout while maintaining the reliability expected in automotive environments.
Similarly, Microchip Technology has highlighted the PIC18-Q83/84 and AVR DA/DD families for ongoing automotive applications. These devices support CAN FD and touch applications with functional safety certifications. The integration of communication protocols like CAN FD into 8-bit architectures allows these lower-cost controllers to remain relevant in vehicle body networks, bridging the gap between basic control and modern connectivity requirements.
Regulatory and Compliance Environment
Regulatory frameworks continue to shape product development cycles. The mandate for functional safety compliance, specifically ISO 26262 for ASIL B applications, remains a critical driver for processor selection. Automotive manufacturers cannot compromise on safety, meaning 8-bit MCUs must maintain certification throughout their lifecycle.
Furthermore, environmental and operational standards dictate performance. The requirement for operation from -40°C to 150°C ensures that components can withstand the harsh conditions of engine compartments and exterior modules. Companies that can demonstrate consistent compliance across temperature ranges and safety protocols gain a significant competitive advantage in the qualification process.
Demand-Side Shifts in Vehicle Electronics
Consumer and enterprise behavior is shifting toward more robust body electronics and safety features. While powertrain electrification often grabs headlines, body electronics remain a volume driver for 8-bit MCUs. Applications such as lighting control, window actuators, and sensor interfaces rely on cost-effective, reliable processing.
The demand for high-temperature operation up to 150°C is particularly pronounced in these areas. As vehicle designs become more compact and thermal loads increase, the ability of an MCU to operate reliably at elevated temperatures without degradation is a key selection criterion for engineering teams.
Supply Chain and Cost Structures
Economic factors play a substantial role in MCU selection. 8-bit solutions offer a cost-effective alternative for applications where 32-bit processing power is unnecessary. With semiconductor supply chain lead times for MCUs normalizing in 2026 following earlier volatility, production stability has returned. This stability allows automotive manufacturers to plan production runs with greater confidence, sustaining demand for established 8-bit parts.
However, cost pressures persist. Automotive OEMs continuously seek to reduce bill-of-materials costs. Suppliers that can offer integrated solutions—such as devices with built-in ADCs or memory—that reduce the need for external components provide value beyond the unit price of the MCU itself.
Competitive Landscape and Leading Strategies
The competitive environment is defined by established players leveraging long-standing relationships and specific technical capabilities. The market's high concentration indicates that incumbents hold significant leverage, but differentiation remains key to securing design wins.
Strategic Positioning of Key Players
Microchip Technology maintains a strong position through its focus on functional safety and connectivity. By offering AEC-Q100 Grade 0 certified PIC and AVR 8-bit MCUs with CAN/CAN FD support, they address the need for reliable communication in body and HMI applications. Their emphasis on ISO 26262 ASIL B compliance and high-temperature operation up to 150°C aligns directly with the rigorous demands of modern automotive designs.
STMicroelectronics competes through reliability and series expansion. The STM8AF and STM8AL series are positioned as high-reliability solutions for automotive body and powertrain applications. With features like data EEPROM, operation up to 150°C, and support for LIN and CAN, they cater to engineers seeking proven stability. Their continued investment in ecosystem tools and enhanced packages demonstrates a strategy of sustaining legacy architectures while improving usability.
NXP Semiconductors leverages its extensive automotive heritage. Supplying S08 and legacy HC05/HC08/HC11 8-bit MCUs with automotive qualification provides a pathway for cost-effective control applications. Their support for CAN in these legacy lines ensures compatibility with existing vehicle networks, making them a viable option for industrial control and automotive applications where upgrade costs must be minimized.
Silicon Laboratories focuses on integration and form factor. Their C8051F52x and C8051F5xx series offer high integration, including 12-bit ADCs, within small packages. This makes them suitable for industrial and automotive sensor and control applications where space is constrained. Their strategy centers on providing dense functionality in a compact footprint, appealing to designs with strict size limitations.
Renesas Electronics utilizes its power efficiency strengths. The RL78 family offers 8/16-bit low-power MCUs with automotive qualification. Targeting body control, lighting, and sensor applications, Renesas emphasizes energy efficiency, which is critical for battery-powered systems and overall vehicle energy management.
Infineon Technologies maintains a presence through established legacy lines. Offering the XC800 A-family 8-bit automotive MCUs for demanding applications, they rely on the trust associated with their broader automotive portfolio. Their strategy involves supporting proven architectures that meet rigorous quality standards for challenging environments.
PW Consulting Information & Electronics Research Center
Market Evolution and Consolidation Trends
The market structure suggests continued consolidation among top-tier suppliers. With the top five companies controlling over 80 percent of revenue, new entrants face significant hurdles in displacing established relationships. Automotive qualification cycles are long, and once a component is validated in a vehicle platform, switching costs are high.
However, differentiation opportunities exist in niche areas. Suppliers that can offer unique value propositions—such as superior integration, specific temperature ranges, or enhanced security features within the 8-bit constraint—can carve out sustainable positions. The trend toward localizing production in Asia also opens avenues for regional players to capture share by offering supply chain proximity to OEMs, provided they can meet global quality standards.
Future Trends and Commercial Opportunities
Looking ahead to the next 3-5 years, several trends will define the trajectory of the 8-bit automotive MCU market. Stakeholders should prepare for these shifts to capitalize on emerging opportunities.
Sustained Niche Dominance
Despite the rise of 32-bit and 64-bit processors in high-performance computing and ADAS, 8-bit MCUs will maintain dominance in specific body electronics and sensor applications. The cost-performance ratio for simple control tasks remains unbeatable. Commercial opportunities lie in optimizing these legacy architectures for modern interfaces, ensuring they remain compatible with evolving vehicle network standards without increasing cost.
Supply Chain Localization
Geopolitical tensions are accelerating the localization of automotive MCU production. Manufacturers may find opportunities in establishing or expanding regional production capabilities in Asia to serve local OEMs. This shift reduces logistics risks and aligns with government incentives for domestic semiconductor manufacturing. Companies that can guarantee regional supply stability will be preferred partners for OEMs seeking to de-risk their supply chains.
Enhanced Functionality in Legacy Cores
Expect to see continued updates to 8-bit portfolios, focusing on functional safety and connectivity. As regulatory requirements tighten, even lower-end controllers must support necessary safety mechanisms. Suppliers that proactively update their 8-bit lines to meet emerging safety and communication standards will secure long-term design wins. The commercial opportunity here is in providing support services and software ecosystems that make integrating these updating parts easier for engineering teams.
Potential Risks
Risks include the potential for stringent safety regulations to increase compliance costs, squeezing margins on cost-sensitive parts. Additionally, if geopolitical localization efforts fragment the market too severely, it could lead to inefficiencies in global supply chains. There is also a risk that rapid advancements in low-cost 32-bit alternatives could eventually erode the price advantage of 8-bit solutions in certain applications, necessitating careful monitoring of technology substitution trends.
Microcontrollers (MCU) Market
Actionable Insights for Decision Makers
For manufacturers, investors, and procurement teams, navigating the 8-bit automotive MCU market requires a balanced approach that respects legacy stability while anticipating change.
-
For Semiconductor Manufacturers: Focus on extending the lifecycle of proven 8-bit architectures through functional safety updates and enhanced integration. Invest in regional supply chain capabilities to meet localization demands in Asia. Prioritize customer support and ecosystem tools to differentiate beyond unit price, ensuring design wins stick through qualification cycles.
-
For Investors: Evaluate companies based on their ability to maintain compliance with evolving safety standards while managing cost pressures. Look for suppliers with strong regional presence in Asia to capitalize on localization trends. Monitor the balance between legacy revenue streams and investment in next-generation low-power interfaces that keep 8-bit relevant.
-
For OEMs and Procurement Teams: Diversify supplier bases where possible to mitigate geopolitical supply risks, while maintaining the stability required for long-term vehicle platforms. Engage early with suppliers regarding availability and qualification timelines for 8-bit parts, as lead times may fluctuate with regional production shifts. Prioritize components with robust functional safety certifications to streamline your own validation processes.
Detailed segmentation data, country-specific forecasts, and customized strategic recommendations are available in the comprehensive research report. Accessing granular insights allows stakeholders to validate assumptions and refine strategies based on precise market volumes and competitive positioning. For a deeper dive into the specific dynamics shaping this sector, refer to the full study for exhaustive data and analysis.
For detailed analysis of this topic, please visit the official page: 8-bit Automotive Microcontrollers (MCU) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Integrated Workforce Mobility Market: Why the 10.25% CAGR Reshapes Global Strategy
By pmarketresearch, 2026-09-18
The Integrated Workforce Mobility Market: Strategic Trends and Commercial Opportunities in a Hyperconnected Era
The integrated workforce mobility market has evolved from a niche compliance function into a central pillar of global talent strategy. Valued at 14.5 billion USD in 2025, the market has expanded consistently over the past five years, reflecting a fundamental shift in how organizations deploy, manage, and retain international talent. Looking ahead to 2032, the trajectory points toward sustained expansion, with a compound annual growth rate of 10.25 percent positioning the sector well above many legacy enterprise software categories. This growth is not merely a function of rising cross-border assignments; it signals a deeper restructuring of work itself, where mobility platforms, compliance infrastructure, and digital work environments converge to support distributed, hybrid, and remotely hosted teams.
PW Consulting Information & Electronics Research Center
Yet the market operates at a structural inflection point. Organizations are increasingly caught between the operational imperative to move talent quickly and the regulatory reality of tightening border controls, data privacy mandates, and social security scrutiny. At the same time, the technology stack supporting workforce mobility is fragmenting across device management, application governance, content security, and identity controls, forcing enterprises to reconcile point solutions with integrated platforms. A third tension lies in talent economics: companies must balance cost discipline with the need to offer seamless relocation, cultural integration, and digital onboarding experiences that actually retain high-value assignees. These challenges do not signal market weakness; rather, they define where value will concentrate over the next cycle.
Market Definition and Structural Realities
The integrated workforce mobility market encompasses the technologies, advisory services, and managed programs that enable organizations to deploy employees across borders, manage remote workforces, and comply with immigration, tax, and data security requirements. Historically anchored by global assignment administration, the category has broadened to include digital platforms that orchestrate compliance workflows, payroll alignment, device provisioning, and employee experience touchpoints. The revenue base of 14.5 billion USD in 2025 reflects a market that has moved beyond cyclical assignment volumes and now captures recurring platform usage, managed services, and enterprise-grade security tooling that supports distributed work.
North America remains the largest demand center, reflecting the depth of multinational headquarters, the scale of technology-driven talent strategies, and the maturity of compliance and mobility service ecosystems. Europe follows as a substantial market, shaped by cross-border labor frameworks, high assignment density, and increasingly complex social security coordination. Asia Pacific has emerged as a fast-growing region, driven by intra-Asia talent flows, expanding shared services hubs, and the rapid digitization of HR and mobility operations. Latin America and the Middle East and Africa represent smaller but strategically important pools, often tied to regional headquarters relocation, nearshoring initiatives, and specialized project deployments. The regional mix underscores a clear reality: demand is global, but compliance intensity, infrastructure readiness, and talent availability vary widely enough to require localized execution even within unified platforms.
Deployment patterns further illustrate the market’s direction. Cloud-based delivery now dominates, favored for its scalability, faster integration with HR and identity systems, and ability to support rapid policy updates across jurisdictions. On-premises deployments persist in environments with stringent data residency, legacy infrastructure, or highly regulated operational requirements, but their relative share highlights the broader shift toward cloud-native architectures that can absorb new compliance rules and remote work scenarios without heavy re-engineering. On the solution side, mobile device management continues to anchor the market, given its role in securing endpoints and enabling secure access for distributed staff. Mobile application management and mobile content management extend that foundation by governing which tools employees can use and how sensitive information is stored, shared, and audited. Identity and access management, while smaller in absolute terms, is increasingly critical because cross-border mobility is only as reliable as the authentication, provisioning, and access governance that sit beneath it.
Core Challenges and Inflection Points
Several structural challenges are reshaping how organizations approach workforce mobility. The first is compliance fragmentation. Digital border systems, tax coordination, and social security scrutiny are intensifying, making it harder to treat mobility as a simple HR workflow. Assignees and remote workers increasingly move through environments where eligibility, withholding, and data handling rules change frequently, and organizations that rely on manual processes face higher compliance risk and slower deployment timelines.
A second challenge is the technology integration gap. Many enterprises still operate disjointed stacks for device management, application security, content controls, and identity governance. This fragmentation creates blind spots in visibility, slows provisioning, and complicates audit readiness. The more distributed the workforce becomes, the more acute the operational penalty of disconnected systems. Integrated platforms that unify policy execution, access controls, and user experience are gaining relevance precisely because they reduce the friction between compliance and productivity.
A third challenge involves talent experience and retention. Cross-border mobility has historically been managed as a cost and risk function, but competitive labor markets are forcing a reframe. Employees expect clear onboarding, supportive relocation experiences, and digital tools that make remote or mobile work seamless. Programs that overemphasize compliance at the expense of user experience risk higher assignment dropout, lower engagement, and weaker long-term workforce planning outcomes. The market is therefore shifting from transactional mobility administration toward experience-led, data-informed talent deployment.
Strategic Drivers Reshaping the Market
The market’s expansion is being propelled by a convergence of technology, policy, and demand-side dynamics. The most consequential driver is the maturation of cloud-native mobility architectures and the broader enterprise tooling ecosystem that supports distributed work. Secure device enrollment, policy-driven application distribution, content encryption, and identity verification are now expected capabilities rather than optional enhancements. These building blocks allow organizations to scale mobility programs without proportionally scaling administrative overhead, and they make it feasible to extend secure work environments to contingent staff, remote hires, and short-term cross-border deployees.
Policy and regulatory evolution is equally influential. Public infrastructure initiatives focused on advanced networks and broadband expansion are reinforcing the connectivity base that distributed work depends on. As legacy copper systems transition toward fiber-based and wireless capacity upgrades, organizations can rely on more consistent data transport for mobility applications, video collaboration, remote access, and location-aware compliance workflows. Alongside infrastructure modernization, regulatory attention on digital border processes and tax/social security coordination is increasing. This does not slow mobility so much as reshape it: programs must be designed with built-in compliance checks, jurisdictional logic, and audit trails, which in turn raises demand for platforms and advisory services that can operationalize those requirements at scale.
Demand-side behavior is shifting as well. Organizations are increasingly treating internal mobility, international assignments, and remote work as interconnected levers in talent strategy rather than separate programs. The rise of hybrid work models has expanded the definition of mobility to include employees who remain in one country but operate across borders digitally, consuming content, collaborating with international teams, and accessing systems that require consistent security and governance. At the same time, employers are seeking better visibility into workforce deployment patterns so they can balance tax efficiency, talent access, and employee experience. Payroll and HR data are increasingly used to optimize mobility program design, helping organizations identify where assignments are underutilized, where compliance costs can be reduced, and where policy adjustments can improve retention.
Cost structure and supply-side dynamics also play a meaningful role. Mobile workforce environments require ongoing management of devices, licenses, security policies, and support workflows. Companies that can consolidate these functions into integrated platforms gain operating leverage, especially when they face high assignment volumes or frequent policy changes across jurisdictions. Managed services further extend this advantage by offloading specialized immigration, tax, and relocation coordination to providers that maintain current regulatory knowledge and operational capacity. In a market where compliance mistakes and employee dissatisfaction both carry real costs, the economic case for integrated mobility solutions is growing stronger.
Competitive Landscape and Differentiation
The competitive environment blends advisory-led service providers, platform-focused specialists, and large technology firms whose tools underpin secure mobility at scale. This mix is one reason the market is both competitive and rapidly evolving: different players compete on service depth, technology breadth, geographic coverage, and employee experience, and the lines between them are increasingly blurred as platforms absorb compliance workflows and service providers invest in digital delivery.
EY occupies a strong position by combining tax, immigration, global compensation, and mobility pathway capabilities with a platform orientation that connects mobility to broader business strategy. Its recent emphasis on trust infrastructure and strategic integration signals a move beyond assignment administration toward the idea that mobility programs must be trusted, transparent, and aligned with enterprise priorities. That positioning matters because cross-border mobility increasingly depends on data governance, employee confidence, and executive sponsorship, not just operational execution.
Vialto Partners differentiates through globally integrated service design, covering immigration, tax, managed services, business travel, and remote work compliance, supported by digital tools such as its myMobility platform. Visibility in industry recognition and published insights on payroll-driven mobility optimization highlights an emphasis on practical program improvement and partnership-driven delivery. In a market where clients want both compliance rigor and user-friendly execution, that combination is a meaningful value proposition.
Mercer continues to leverage its scale in talent mobility services, policy benchmarking, and global mobility program support. Its comparative advantage lies in data-rich benchmarking and structured program design for international assignments and workforce strategy, which helps organizations calibrate policies against peer practice while maintaining compliance and cost discipline.
On the technology side, Microsoft provides the collaboration, cloud, security, and identity foundation that many mobility programs rely on, making it an important enabler of hybrid and remote work at enterprise scale. IBM contributes enterprise mobility management and workforce transformation capabilities, including device and application management tools designed for mobile workforce environments. VMware, now part of Broadcom, offers enterprise mobility management through its workspace and device management solutions, helping organizations secure access across endpoints and applications. Cartus rounds out the field with relocation and global talent mobility services that emphasize employee experience, policy design, and strategic program execution.
The landscape is moving toward tighter integration. Service providers are investing in digital platforms and data-driven insights to improve speed, consistency, and transparency, while technology firms continue to deepen the security, identity, and management layers that make mobility viable at scale. At the same time, new entrants and niche specialists can gain traction by focusing on specific pain points, such as remote work compliance, regional assignment complexity, or employee experience design. The result is a market that is consolidating around integration, yet still open to differentiation by specialty, geography, and service model. Market concentration remains moderate, with a meaningful share held by leading firms but enough fragmentation to reward focused capabilities and strong execution.
Healthcare Workforce Management System Market
Forward Outlook: Trends That Will Shape the Next Cycle
Over the next three to five years, the most consequential trend will be the emergence of mobility as an integrated control plane rather than a set of disconnected workflows. Platforms that combine compliance logic, identity and access governance, device and application management, and employee experience will become the default architecture for organizations managing distributed talent. This matters commercially because it shifts value from manual coordination toward scalable orchestration, where faster provisioning, stronger audit readiness, and better policy consistency become competitive advantages.
A second trend is the increasing use of workforce data to optimize mobility strategy. Payroll, assignment history, compliance outcomes, and employee feedback will be used more systematically to refine policy design, predict cost exposure, and improve assignment success rates. Organizations that treat mobility data as strategic rather than operational will be better positioned to balance talent access, cost control, and retention. This creates opportunities for advisory and technology capabilities that can translate raw data into program decisions.
A third trend is the continuing realignment of compliance expectations around digital borders, data handling, and cross-border employment rules. Rather than reducing mobility, this dynamic will likely accelerate demand for systems and services that embed jurisdictional logic, automate documentation, and support ongoing monitoring. The commercial implication is that mobility programs will need to be designed for adaptability, with policy engines and platform configurations that can absorb regulatory change without full rebuilds.
These trends carry uncertainty. Regulatory direction may diverge by region, technology integration may prove more complex in organizations with legacy systems, and talent expectations may evolve faster than program budgets. Companies that anticipate these variables by building flexible platforms, maintaining compliance visibility, and investing in employee experience will be better placed to convert change into advantage.
Strategic Actions for Decision Makers
For enterprise executives and strategic planning teams, the priority is to treat integrated workforce mobility as a structural capability rather than a periodic administrative need. That means consolidating device, application, content, and identity management into a coherent architecture, aligning mobility programs with broader talent strategy, and using benchmarking and internal data to refine policy design. Organizations that do this early will reduce compliance exposure, improve deployment speed, and strengthen retention in competitive talent markets.
For investors, the opportunity lies in identifying providers and technology layers that can sustain recurring value as mobility programs become more digital and data-driven. Attention should focus on platforms with strong integration potential, clear compliance and security differentiation, and the ability to support both managed services and self-serve enterprise usage. Given ongoing consolidation and specialization, selective exposure to capability leaders and enabling technologies is likely to outperform broad, undifferentiated exposure.
Integrated Smart Toilet Market
For procurement and mobility program owners, the practical task is to evaluate solutions based on integration depth, jurisdictional coverage, employee experience, and operational transparency. Procurement decisions should weigh not only initial cost but also the downstream impact on compliance risk, assignment success, and administrative burden. Detailed segmentation data, vendor comparisons, and tailored program recommendations can materially improve those decisions, especially when the market is changing this quickly.
For detailed analysis of this topic, please visit the official page: Integrated Workforce Mobility Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Leadership Due Diligence Market: Why 6.82% CAGR Redefines Private Equity Strategy
By pmarketresearch, 2026-09-18
Leadership Due Diligence Market: Strategic Trends and Commercial Opportunities Through 2032
The leadership due diligence market has evolved from a peripheral consideration in transaction advisory to a central component of investment decision-making. By 2025, the market reached an estimated $450.0 million in revenue, expanding from $321.45 million in 2020. This trajectory reflects a compound annual growth rate of 6.82 percent across the forecast period extending to 2032, with projected revenue climbing toward $708.68 million by the end of the outlook window. The growth pattern indicates sustained demand rather than cyclical fluctuation, driven by structural shifts in how capital allocators and corporate acquirers evaluate human capital risk.
Several structural challenges define the current inflection point. First, the field remains fragmented, with a top three concentration of 38.5 percent and a top five concentration of 48.2 percent. This level of concentration suggests that while established players hold meaningful share, significant room exists for specialized entrants and niche methodologies to capture targeted segments. Second, standardization gaps persist across assessment protocols, creating variability in how leadership risk is quantified, communicated, and integrated into deal pricing or post-close integration planning. Third, the market faces a credibility test: leadership due diligence must move beyond checkbox compliance and demonstrate measurable influence on deal outcomes, retention metrics, and value realization timelines. Buyers and investors increasingly question whether assessments translate into actionable intelligence or merely confirm pre-existing assumptions.
The stakes have risen because leadership and cultural misalignment are now widely recognized as material contributors to transaction failure. Industry analysis indicates that leadership and culture factors surface as key drivers in deal success or failure rates ranging from 70 to 90 percent, while weak succession readiness or elevated leadership turnover can compress enterprise value by up to 20 percent in M&A contexts. These figures reframe leadership due diligence from a soft advisory service into a risk mitigation and value preservation function. For executives and investors, the implication is clear: the market is growing because the cost of ignoring leadership risk has become too visible to overlook.
Key Demand Drivers Reshaping the Landscape
Technology-enabled assessment methodologies are accelerating the sophistication of leadership due diligence. Practitioners increasingly combine psychometrics, structured interviews, cross-feedback loops, and reference verification into integrated diagnostic models. This 360-degree approach helps identify blind spots, leadership bench strength, and cultural friction points that traditional financial or legal due diligence often miss. The shift toward multi-source evidence gathering reduces reliance on self-reported narratives and improves the defensibility of conclusions for investment committees and boards. As assessment tools become more refined, the value proposition moves from identifying obvious red flags to surfacing nuanced risk-and-opportunity profiles that inform retention planning, integration design, and post-deal governance.
Regulatory and standards-based expectations are also shaping service design. The adoption of recognized assessment standards, such as ISO 10667-2 in certain leadership evaluation workflows, signals a broader push toward consistency, documentation rigor, and auditability. While the market does not operate under a single mandated framework, the trend toward standardized protocols responds to buyer demands for repeatable methods that can withstand internal scrutiny and external challenge. For deal teams, this means leadership due diligence is increasingly expected to produce structured outputs that align with broader transaction documentation, risk registers, and integration roadmaps rather than standalone narrative reports.
Demand-side behavior is shifting as capital becomes more selective and post-deal execution risk receives greater attention. Private equity and investment firms represent the largest end-user cohort, followed by corporate M&A departments and venture capital investors. These stakeholders are placing heavier emphasis on human capital risk because leadership quality and team cohesion directly affect synergy realization, customer retention, and operational continuity. The buy-side conversation has moved toward practical questions: Does the leadership team have the depth to execute the business plan? Are there succession vulnerabilities? Will cultural integration create friction that slows value creation? These questions have elevated leadership due diligence from a pre-close formality to a continuous consideration that can influence offer structuring, earn-out design, and leadership retention agreements.
Cost and value dynamics further reinforce demand. Organizations are scrutinizing where diligence spending generates defensible returns, and leadership due diligence is increasingly positioned as a lever for protecting enterprise value rather than an additive expense. The logic is straightforward: identifying leadership gaps early can reduce post-close turnover, accelerate integration, and preserve customer and employee trust during transition periods. Conversely, overlooking leadership risk can lead to expensive corrective actions, delayed synergy capture, and reputational damage. As a result, buyers are more willing to invest in structured leadership assessment when it is tied clearly to deal rationale and integration planning.
Competitive Landscape and Strategic Positioning
The competitive arena blends specialized boutique providers with large professional services networks, each pursuing distinct positioning. Specialized firms tend to emphasize dedicated leadership due diligence work-streams embedded within M&A processes, often focusing on leadership structure, culture, human capital risk, retention planning, and post-deal integration. Their differentiation frequently rests on deep transactional context, repeatable assessment architecture, and close alignment with investor and deal team workflows. By operating as focused work-streams rather than broad human capital add-ons, these providers aim to make leadership insights directly usable in investment committee discussions and integration planning.
Directors and Officers (D&O) Insurance Market
Other providers distinguish themselves through methodological breadth and investor-centric design. Some deploy multi-source diagnostic models that combine psychometrics, interviews, surveys, and cross-feedback to identify risks, blind spots, and value creation levers across pre-investment, post-investment, and turnaround scenarios. This approach appeals to investors seeking a comprehensive view of leadership dynamics rather than isolated executive assessments. A separate segment of high-end providers emphasizes bespoke frameworks tailored to private equity, venture capital, strategy advisors, and law firms, with science-based assessments aligned to strategic objectives and cultural integration analysis. These firms often position quality, customization, and strategic alignment as their core advantages, targeting complex transactions where leadership evaluation must connect directly to value creation assumptions.
Large global advisory and consulting networks meanwhile integrate leadership due diligence into broader M&A, transaction advisory, and human capital offerings. Their strength lies in scale, cross-service coordination, and the ability to link leadership assessment with financial, tax, legal, and operational work-streams. For many corporate and institutional clients, this integration reduces coordination friction and supports a unified diligence narrative. At the same time, executive assessment and leadership advisory firms contribute deep competency modeling, bench strength analysis, and fit-for-role evaluation, particularly where post-deal value creation depends on leadership capability and succession readiness. The presence of multiple service models creates choice but also complexity for buyers seeking the right fit for transaction size, industry context, and internal capability.
Assessment Services Market
Market evolution is shaping up as both consolidation and specialization. On one hand, larger advisors continue to absorb human capital and leadership capabilities into integrated transaction practices, which can improve end-to-end consistency. On the other hand, specialized providers are deepening their methods, expanding their transactional relevance, and increasingly articulating leadership due diligence as a de-risking tool rather than a compliance step. Recent industry commentary reflects this shift: leadership due diligence is being reframed as a boardroom priority for building trust in senior leadership appointments, while practitioner guidance emphasizes practical techniques to spot strengths and risks before buy-side decisions. Specialized providers have also reinforced the message that leadership due diligence should function as a core de-risking mechanism in M&A, not a checkbox exercise. The net effect is a market that is professionalizing while still leaving room for differentiated methodologies, sector focus, and regional expertise.
Future Trends and Commercial Implications (2026–2032)
Over the next three to five years, leadership due diligence is likely to become more integrated into transaction workflows rather than treated as a standalone report. As deal teams seek faster, more defensible insight, assessment outputs will increasingly connect to integration planning, retention agreements, and governance design. This integration creates commercial opportunity for providers that can translate leadership diagnostics into practical post-deal actions, such as role design, succession planning, and cultural harmonization roadmaps. Providers that bridge pre-close assessment and post-close execution will be better positioned to demonstrate value beyond the diligence phase.
PW Consulting Information & Electronics Research Center
A second trend is the continued elevation of human capital risk in deal valuation and structuring. As leadership and culture factors are more frequently cited in deal success or failure discussions, investors and corporate acquirers may embed leadership considerations into pricing assumptions, earn-out structures, and management retention terms. This creates opportunities for advisors who can quantify leadership risk in ways that are understandable to financial and legal stakeholders. The commercial implication is that leadership due diligence may increasingly influence not only whether a deal proceeds, but how it is structured and managed after signing.
A third trend is methodological maturation and greater expectation of consistency. As standards-based practices gain visibility and buyers become more sophisticated, the market will likely reward providers with transparent assessment logic, documented processes, and clear linkage between findings and recommended actions. At the same time, uncertainty remains. The market could face pressure if economic conditions slow transaction volume, if buyers reduce discretionary diligence spending, or if overly generic assessments erode trust in the category. There is also a risk that inconsistent quality across providers makes it harder for buyers to compare offerings, slowing adoption in segments where leadership due diligence is not yet standard practice.
Strategic Actions for Decision-Makers
For private equity and investment firms, the priority is to treat leadership due diligence as an integral part of deal risk assessment rather than an optional enhancement. Structuring leadership evaluation around clear transaction hypotheses—such as synergy dependence on management continuity, scalability of the leadership bench, and cultural compatibility with integration plans—can improve the practical utility of findings. Investors should also define how leadership insights will inform retention planning, incentive design, and post-close governance before diligence begins, so that assessment outputs feed directly into execution planning.
For corporate M&A departments, leadership due diligence should be aligned with the strategic rationale for the acquisition. When deals depend on preserving customer relationships, retaining key talent, or integrating distinct operating cultures, leadership evaluation should be scoped early enough to influence deal architecture and integration design. Corporate buyers can benefit from clear criteria that distinguish between leadership gaps that can be addressed through restructuring or external hires and those that pose deeper strategic risk to value realization.
For venture capital and growth-stage investors, leadership assessment should focus on scalability, decision-making quality, and succession resilience as companies move through expansion phases. Early identification of leadership constraints can shape board involvement, recruitment strategy, and governance evolution. Across all buyer types, the most effective use of leadership due diligence comes when it is tied to specific decisions: whether to proceed, how to price risk, whom to retain, and what integration steps to prioritize. Given the range of methodologies, service models, and regional specialties available, obtaining detailed segmentation data and tailored guidance can help organizations match diligence scope to transaction context and internal capability. The full research report provides more granular segmentation, company-level comparisons, and actionable recommendations for selection and deployment.
For detailed analysis of this topic, please visit the official page: Leadership Due Diligence Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com